Water developers adopt selective stance
19 September 2024

UAE-based utility Sharjah Electricity & Water Authority (Sewa) and Saudi water offtaker Saudi Water Partnership Company (SWPC) each received a single bid for their recently tendered independent water producer (IWP) projects.
An all-local team comprising Acwa Power, Haji Abdullah Alireza & Company (Haaco) and AlSharif Contracting & Commercial Development submitted the sole proposal for the contract to develop the Jubail 4 and 6 IWP schemes in Saudi Arabia.
This is a far cry from the four bids SWPC received in 2020 for a contract to develop and operate the Jubail 3B IWP.
However, the fact that SWPC received only two bids for the contract to develop the smaller Ras Mohaisen IWP in April this year indicates that utility or water developers and investors have increasingly adopted a more selective stance when it comes to bidding for new projects.
"Combined, Jubail 4 and 6 is a large project and most developers are tied up with other ones, as there are many IWPs under way at the moment, not only in Saudi Arabia but throughout the GCC," says Robert Bryniak, CEO at Dubai-based Golden Sands Management (Marketing) Consulting.
The Jubail 4 and 6 seawater reverse osmosis (SWRO) plants will have a total combined capacity of 600,000 cubic metres a day (cm/d) and will be developed under one contract.
In comparison, the Ras Mohaisen IWP has a capacity of 300,000 cm/d, while Sewa's Hamriyah IWP will have a capacity of 410,000 cm/d.
Bryniak says that many developers are at, or near, their capacity and this makes it difficult to make short-term commitments without paying significantly more for skilled workers and key equipment component parts.
"Developers may be shying away from some of the larger projects because of this, especially knowing that tariffs need to be competitive to win.
"Developers have to spend significant amounts just to bid on a project and, if unsuccessful, this sunk cost needs to be eventually recouped on future projects. And I think this is resulting in developers being more selective in terms of the projects they go after, focusing more on those where they believe they have a good chance of winning."
The case is slightly different for the Hamriyah IWP, which is Sharjah's first major SWRO project to be procured on a public-private partnership (PPP) basis.
Acwa Power submitted the sole proposal for the contract to develop the project in December last year.
"This is Sharjah’s first IWP and, unlike other jurisdictions such as Oman, Abu Dhabi and Saudi Arabia, the emirate has yet to establish a track record with PPPs, especially in power and water," explains Bryniak
Given several false starts and issues with past PPPs, it is likely that developers will shy away and focus their efforts on more established – and financially stronger – offtakers elsewhere in the region.
Known for its strong risk appetite, Acwa Power signed the water procurement agreement with Sewa earlier in September and a team of France's Sidem and its parent company Veolia has been selected as the project's engineering, procurement and construction contractor.
This means discussions with banks and financial institutions could be nearing their conclusion, leading to the start of the project's construction.
Once the Hamriyah IWP reaches financial close and commercial operations, Bryniak says Sewa should be able to attract more developers for future IWPs.
Going forward, procurers could also consider adopting new or additional measures to attract more developers to their future IWP projects and avoid incurring higher tariffs.
A UAE-based executive with an international developer says that in some cases the quality of the request for proposals (RFPs) being issued can be improved.
MEED understands some of the recent RFPs lack comprehensive information or details, which leads contractors to add higher contingency costs to cover risks.
Bryniak concurs, adding that going forward, procurers throughout the GCC will need to spend more time and effort marketing and promoting their IWPs, and will need to be more selective in terms of timing, in order to optimise competition.
"They may also need to consider modifying their procurement processes to attract more bidders. Otherwise, they might continue to realise only one or just a few bidders, with likely higher tariffs in the near term."

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Developers prepare bids for 1GW Oman bess scheme
12 October 2026
-
 Frontrunner emerges for Saudi Arabia’s GCC rail link design
12 October 2026
-
 Houthi escalation targets Saudi airports
12 October 2026
-
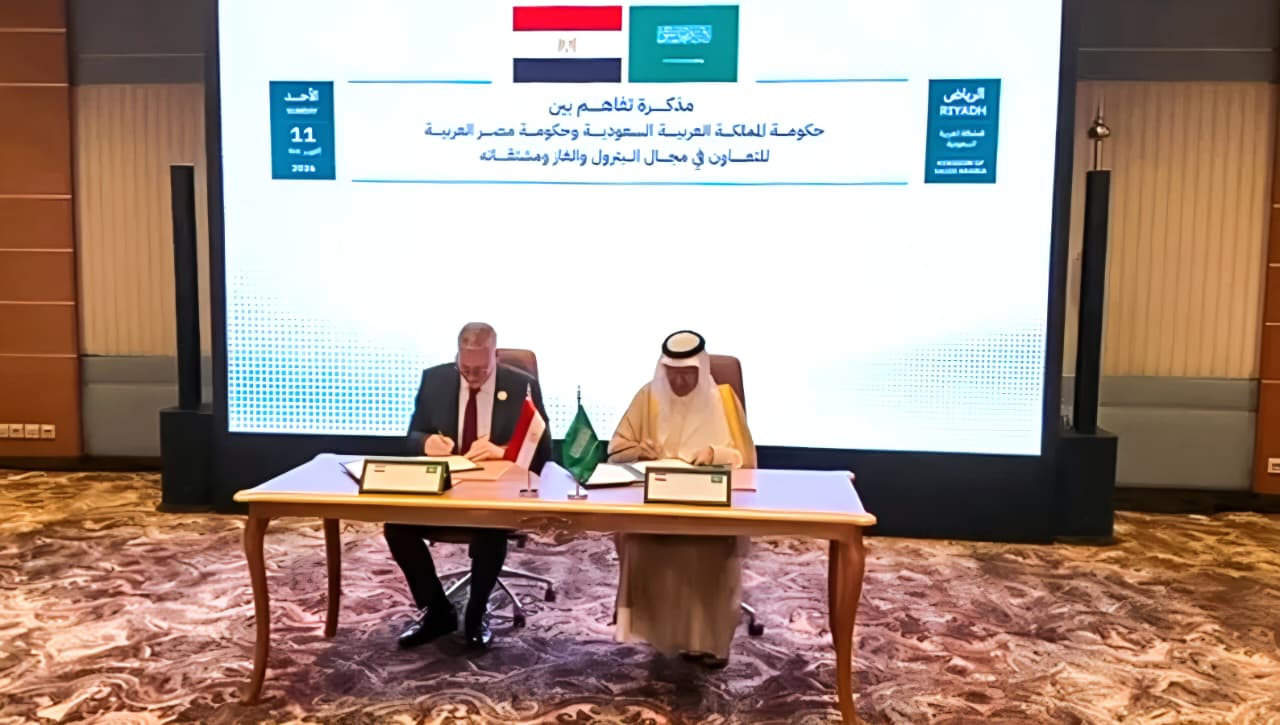 Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
-
 JGC yet to return evacuated workers to Basra refinery
12 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Developers prepare bids for 1GW Oman bess scheme
12 October 2026
Developers are preparing to submit bids for almost 1GW of standalone battery energy storage (bess) projects in Oman, a source close to the project has confirmed to MEED.
The independent power producer (IPP) scheme includes the installation of five bess facilities with a combined power capacity of 950MW and storage capacity of 3,800MWh. Nama Power & Water Procurement Company (PWP) is procuring it.
According to sources close to the project, a developer’s tender was floated in the summer. An initial bid submission deadline has since been extended, with bids expected to be submitted in the coming weeks.
The largest project is a 500MW facility in Sohar, Al-Batinah North governorate, with a storage capacity of 2,000MWh. The Sohar facility is expected to connect to the grid at 220kV. The site covers approximately 149,535 square metres.
Four further installations are planned at Al-Mabellah in Muscat governorate, Ayjah in South Al-Sharqiyah, the Jalan Bani Bu Ali wind farm site in South Al-Sharqiyah, and Sadah in Dhofar.
The Al-Mabellah and Ayjah facilities are each planned to have a capacity of 100MW and storage capacity of 400MWh. Both are expected to connect to the grid at 132kV.
The Jalan Bani Bu Ali installation is planned to have a capacity of 150MW and storage capacity of 600MWh. It is expected to connect to the Sadah wind farm and Jalan Bani Bu Ali wind farm substations.
The Sadah installation is planned to have a capacity of 100MW and storage capacity of 400MWh. It is expected to connect to the Sadah wind farm substations at 132kV.
US/India-based Synergy Consulting is the financial adviser for the procurement; Germany’s Fichtner is the technical adviser; and Germany-headquartered CMS is the legal adviser.
Utility-scale storage
In May, Oman’s Authority for Public Services Regulation (APSR) opened technical bids for a consultancy contract supporting a planned 1,000MW/four-hour bess project.
As previously reported, APSR issued the request for proposals in April as part of wider plans to increase the share of renewable energy in the sultanate.
The sultanate’s first utility-scale solar photovoltaic (PV) plant integrated with battery energy storage (Ibri 3) entered construction at the beginning of the year, comprising a 500MW solar PV plant and a 100MWh bess system.
Also in May, state offtaker Nama Power & Water Procurement Company signed a power purchase agreement with local firm O-Green for Oman’s first round-the-clock renewable energy project.
Renewable energy is expected to increase from 4% of the generation mix in 2024 to 30% by 2030, driving the push for more utility-scale storage projects.
Over roughly the same period, demand is forecast to double, reaching 10 terawatt-hours by 2031.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20511976/main.jpg -
Frontrunner emerges for Saudi Arabia’s GCC rail link design
12 October 2026
French engineering firm Systra has emerged as the frontrunner to provide design consultancy services for the Saudi Arabian section of the GCC railway network, which is intended to link all six member states.
The tender covers the concept, preliminary and issued-for-construction design stages. Saudi Arabia Railways (SAR) requires the selected consultant to review, update and complete the existing preliminary design.
Consultants submitted proposals on 14 July, as MEED reported.
The consultants who submitted bids included:
- AtkinsRealis with Khatib & Alami
- Deutsche Bahn with ARX
- Egis with Sener
- Idom with Dar Al-Handasah
- Systra
Saudi Arabia’s section of the railway will start at Al-Khafji in the Eastern Province, near the border with Kuwait, and end at Al-Batha, on Saudi Arabia’s border with the UAE. The route in Saudi Arabia will be about 672 kilometres (km) long.
Tendering is also ongoing for a separate contract involving design management and review to oversee engineering works on the GCC railway network.
The tender was issued on 9 September, with a submission deadline of 18 October, as MEED exclusively reported.
The tender seeks a consultant to manage, audit and verify deliverables produced by SAR’s separately appointed design services consultant, rather than carry out the design itself.
Construction will be tendered separately through competitive bidding once designs are approved.
The GCC railway will run for about 672km inside Saudi Arabia, linking the kingdom’s existing network to Kuwait, Qatar, the UAE and Bahrain, with four sections of about 141km, 200km, 151km and 21km, respectively.
The line is planned as a single-track, non-electrified corridor for mixed freight and passenger traffic, with a maximum axle load of 32.4 tonnes and passing loops for bidirectional working.
GCC railway line
Under the overall plan, the railway will run from Kuwait, pass through Dammam in Saudi Arabia, reach Bahrain via a planned causeway, and continue from Dammam to Qatar, the UAE and, ultimately, Muscat via Sohar in Oman. The railway is reported to cover about 2,186km in total.
The route length within each member state is as follows:
- UAE – 684km
- Saudi Arabia – 672km
- Oman – 306km
- Qatar – 283km
- Kuwait – 145km
- Bahrain – 36km
The railway is designed for passenger trains travelling at 220 kilometres an hour (km/h) and freight trains operating at 80km/h–120km/h.
With high levels of project activity, governments in spending mode and renewed cooperation under the Al-Ula Declaration, the latest efforts to restart the GCC railway project may make more progress than previous attempts. If completed, the railway could prove transformational for a region that is globally connected but still divided by national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20510318/main.gif -
Houthi escalation targets Saudi airports
12 October 2026
Yemen’s Houthis have placed Saudi Arabia’s civil aviation infrastructure at the centre of their campaign against the kingdom. Two strikes on King Khalid International airport in Riyadh over the weekend killed 13 people and injured 320.
The deadlier attack hit a passenger terminal on the afternoon of 10 October. The General Authority of Civil Aviation (Gaca) said it killed 12 people, including four Saudi citizens, and injured 309. Airport operations were suspended pending a damage assessment.
A second strike hit Terminal 4 on the afternoon of 11 October, sparking a fire that killed a Pakistani resident and injured 11 others, according to Gaca. The Saudi-led coalition reported intercepting a cruise missile near the airport that afternoon. Gaca also reported an attack on King Fahd International airport in Dammam that evening, following a coalition report of a projectile falling near the facility the previous night.
The weekend strikes followed attacks on Abha International airport on 6 October and on King Khalid International airport on 7 and 8 October, the last of which included a strike on a Saudia aircraft. Gaca figures put the toll from the week’s attacks on Saudi airports at 19 dead and more than 350 injured.
The Houthis said they would continue operations inside the kingdom and that all Saudi airports were potential targets, with the exception of those serving the holy cities. The group says it is acting in response to Riyadh’s support for Yemeni government forces and a Saudi air strike on Sanaa airport. It has also claimed attacks on Saudi oil facilities, which Saudi authorities have not confirmed.
Aviation exposure
The attacks strike a sector central to the kingdom’s diversification plans. King Khalid International airport’s existing terminals are to be absorbed into King Salman International airport (KSIA), a 57-square-kilometre development with six parallel runways targeting a capacity of 120 million passengers by 2030 and 185 million by 2050.
Procurement on KSIA has gathered pace this year. In July, a joint venture of China Civil Engineering Construction Corporation and Dammam-based Mofarreh AlHarbi & Partners won an estimated SR800m ($213m) contract for enabling and substructure works on Terminal 6, which will add capacity for 40 million passengers. Turkish contractor IC Ictas and Saudi Arabia’s Al-Rashid Trading & Contracting recently secured a SR800m ($213m) contract for the airport’s Private Aviation Terminal.
Government-owned Saudi Royal Aviation set 8 October as the bid deadline for an estimated SR3bn ($800m) contract to build an aviation complex within the KSIA masterplan, the same day the Houthis struck King Khalid International airport and a Saudia aircraft.
Airlines have already adjusted. Flydubai cancelled flights to Riyadh and Yanbu up to 10 October and to Abha up to 11 October, and Etihad Airways reported extended delays on its Abu Dhabi to Riyadh service after the airport closed on 8 October. The UK Foreign Office has advised against all travel to areas within 10km of the Yemeni border.
Market reaction
The Saudi stock market’s response has been muted so far. The Tadawul main index fell 15.54 points to close at 10,360.74 on 11 October, the first trading session after the Saturday attack, with turnover of SR2.6bn ($693m). The session closed before the second strike on King Khalid International airport and the attack on Dammam, and Monday’s trading will be the first to reflect the full weekend.
The weekend also brought a separate maritime incident. UK Maritime Trade Operations said an oil tanker was struck by an unidentified projectile in the Strait of Hormuz on 11 October, with its crew reported safe.
Diplomatic response
The coalition described the 10 October attack as a war crime and said it would respond decisively. It said on 10 October that it had destroyed 136 military targets in Houthi-controlled areas and was working to dismantle the group’s ballistic missile network.
Egypt, Pakistan and Turkiye joined Saudi Arabia in an R4 group statement condemning the attacks and supporting measures taken by the kingdom in response. The Arab League also voiced its support for Saudi Arabia. On 11 October, Iran’s foreign minister spoke by telephone with his Saudi counterpart, Prince Faisal Bin Farhan, to discuss the escalation. The US and UK have also signalled the possibility of further support for the kingdom.
The escalation comes against the backdrop of the regional conflict, which has drawn Saudi Arabia into a renewed Yemen front after several years of relative calm following the 2022 ceasefire. The extent of the damage at King Khalid International airport, which Gaca is still assessing, and the speed at which international carriers resume full schedules will determine how far the attacks disrupt the kingdom’s aviation programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20505600/main.gif -
Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
Egypt and Saudi Arabia have signed an agreement to strengthen cooperation in the oil, natural gas and petrochemicals sectors, according to a statement from Egypt’s Ministry of Petroleum & Mineral Resources.
The memorandum of understanding (MoU) was signed in Riyadh by Karim Badawi, Egypt’s minister of petroleum and mineral resources, and Abdulaziz Bin Salman, Saudi Arabia’s minister of energy.
Under the agreement, both sides will enhance cooperation in trading, transporting, storing and distributing crude oil, petroleum products and natural gas.
They will also expand cooperation on developing the infrastructure and logistics services that support these activities.
In its statement, Egypt’s Ministry of Petroleum & Mineral Resources said: “These efforts will contribute to improving energy market efficiency, enhancing the resilience and reliability of supply chains, and strengthening energy security.”
The MoU also provides for expanded cooperation in exchanging expertise and best practices in operating and developing fuel stations, as well as in transporting and tracking petroleum products and liquefied petroleum gas cylinders.
Additionally, the agreement seeks to explore investment opportunities in joint projects and promote exports.
The latest agreement comes as Egypt becomes an increasingly important export route for Saudi Arabia.
Due to disruptions and security risks affecting shipments through the Strait of Hormuz, Saudi Arabia has been redirecting crude exports via its East-West Pipeline to Yanbu on the Red Sea.
Meanwhile, the Bab El-Mandeb Strait, at the southern end of the Red Sea, has also become a security concern due to military activity in Yemen. Egypt offers an alternative route through the Sumed pipeline, which runs from Ain Sokhna on the Red Sea to Sidi Kerir on the Mediterranean.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20503239/main.jpeg -
JGC yet to return evacuated workers to Basra refinery
12 October 2026
Japan’s JGC has yet to bring evacuated workers back to the Basra refinery project in Iraq, according to industry sources.
JGC evacuated its personnel from the site in the southern oil hub of Basra following the start of the regional conflict on 28 February, when the US and Israel attacked Iran.
The evacuation halted work on the project, which was in its final construction stage.
On 14 August 2026, Iraq’s Ministry of Oil announced that it had signed an agreement with JGC to resume work on the fluid catalytic cracking (FCC) project at Basra refinery.
One source said: “Even though the agreement to bring the evacuated workers back was signed about two months ago, there is still no sign of the evacuated workers on the project site.
“It is possible that they will return soon, but it is hard to tell what will happen next in the current security environment.”
Earlier this month, Iraq’s Ministry of Oil said it met with Japanese officials to discuss plans to commission the FCC unit under the Basra refinery upgrade project.
The statement did not say when the evacuated JGC workers would return to the project site.
Strategic project
Iraq’s state-owned South Refineries Company (SRC) sent JGC notice of the main contract award for the FCC package of the Basra refinery upgrade project in August 2020.
JGC was awarded the contract in consortium with South Korea’s Hyundai E&C.
The official contract signing ceremony was held in Baghdad on 1 October 2020.
The contract awarded to JGC, which uses the engineering, procurement, construction and commissioning model, was worth $3.78bn.
The FCC package is part of a broader project to upgrade the Basra refinery.
The project site is located about 12 kilometres east of Iraq’s southern city of Basra.
The wider upgrade project involves installing new facilities on land adjacent to the existing Basra refinery, including a vacuum distillation unit and a diesel desulphurisation unit.
In April 2021, France’s Axens won a contract in Iraq to provide four process technologies to SRC for the Basra refinery upgrade project.
The technologies that SRC selected are:
- Diesel hydrotreatment unit (Prime-D)
- Vacuum gasoil (VGO) hydrotreating unit
- VGO fluid catalytic cracker unit
- Oligomerisation unit (polynaphtha)
In addition, Axens is providing catalysts and adsorbents, proprietary equipment, training and technical services.
MEED’s latest report on Iraq includes:
> COMMENT: Iraq’s reform window narrows
> GOVERNMENT: Al-Zaidi takes Iraq’s premiership under US shadow
> BANKING: Financial challenge tests Iraq’s resolve
> ECONOMY: Iraq enters era of resilience, reform and rising risks
> OIL & GAS: Iraqi oil and gas sector in crisis
> POWER & WATER: Focus shifts to delivery of Iraq utilities expansion
> CONSTRUCTION: Momentum builds in Iraq’s post-war construction sectorTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20503212/main.png