Transport projects driven by key trends
24 December 2024

Two key trends are driving the region’s transport projects. The first is a longstanding competitive advantage based on the Middle East’s strategic location, while the second is a renewed drive for regional integration.
 Over the past 20 years, the Middle East’s aviation sector has been transformed. Dubai has established itself as the world’s busiest international airport, while other regional airports have become significant aviation hubs, albeit on a smaller scale.
The logic is simple. The Gulf is within an eight-hour flight of most major destinations and two-thirds of the world’s population. It is also strategically located between established markets in Europe and North America and emerging markets in Africa and Asia.
Over the past decade, major projects have been undertaken to upgrade capacity and harness more of the global aviation market. As these projects were completed, 2024 became a turning point and the focus pivoted to two new projects that will be the largest airports in the region by far.
Major airports
Riyadh’s King Salman International airport was launched at the end of 2022. The airport, which will be built to replace the existing King Khalid International airport, aims to accommodate up to 120 million passengers by 2030 and 185 million by 2050.
In 2024, the project took several steps forward: it appointed UK-based Mace as a delivery partner; tendered contracts for delivery partner roles for the terminals, airside works and landside infrastructure; and began to approach contractors for construction work on the project.
The region’s other major airport scheme is the $35bn expansion of Dubai’s Maktoum International airport. The project, which had been planned for over a decade, had new designs approved in April. It will have a passenger handling capacity of 260 million passengers annually – the world’s largest.
Early infrastructure contracts have been awarded since the designs were approved, and contractors have been briefed on main construction packages that are expected to start in 2025.
 Building connections
The other key drive for the region’s transport projects is integration. Following the 2021 Al-Ula agreement, the GCC has been pressing to establish closer trade ties to accompany closer political links. At the same time, seaborne trade has been threatened by logistics bottlenecks and, more recently, by Houthi attacks in the Red Sea. These two factors combined have led to a push to build better overland transport links across the region.
The best demonstration of the renewed focus on overland transport links connecting the region came in April 2024, when Oman-Etihad Rail Company awarded contracts for the Hafeet Rail project connecting the UAE with Oman.
The estimated AED5.5bn ($1.5bn) design-and-build contract for the civil works was secured by Abu Dhabi-based National Projects Construction, National Infrastructure Construction Company and Tristar Engineering & Construction with Oman’s Galfar Engineering & Contracting. A contract for the rolling stock systems and integration contracts went to German firm Siemens and Egyptian contractor Hassan Allam Construction.
The speed at which the Hafeet Rail contracts were awarded was an anomaly, as other major rail projects have taken much longer to be awarded and move into construction. This has become a source of frustration for companies that invest considerable time and financial resources in tendering for contracts.
One of the longest-running contract negotiations in the region is for the $7bn Saudi Landbridge project that will link the western Red Sea coast of the kingdom to the eastern Gulf coast through Riyadh.
Saudi China Landbridge Consortium signed a memorandum of understanding to develop the project in October 2018. After six years of negotiations, there is now an expectation that construction will start in 2025, although there have been false dawns in the past.
The Mecca Metro project also has a long history. MEED reported in June 2024 that a feasibility study for the $8bn first phase of the scheme had restarted. Contracts for construction work were tendered and close to being awarded
in 2014.
Another rail project that has been slow to progress is Bahrain’s planned metro scheme. Launched in 2021, Bahrain’s Transportation & Telecommunications Ministry prequalified seven groups for the contract to deliver the first phase of the network on a public-private partnership basis in early 2023. Since then, it is understood that the project has shifted back to the study phase as the government considers the best way to proceed with the scheme.
 Airport projects also take time. The construction contract for the substructure of Al-Maktoum International airport was close to being awarded in early 2020 before the Covid-19 pandemic. That tender then ceased to be a priority as the focus for Dubai’s aviation sector shifted to supporting airlines Emirates and Flydubai and airport operations during the lockdown period, enabling the sector to reopen more quickly than its competition.
Now, expanding Dubai’s airport capacity is once again a strategic priority. Dubai International’s constrained site means it cannot add to its two existing runways, which means it is becoming vulnerable to being overtaken by other emerging hubs in the region.
At the tail end of the construction process, the completion of large-scale transportation projects is often delayed. The largest ongoing transport scheme in the region by value is Riyadh’s $23bn six-line metro network, for which construction contracts were awarded in 2013. It was rumoured in late 2024 that it would open by the end of the year, although no opening date has been confirmed.
There are examples of rail projects being completed more quickly. The Doha Metro network was opened as planned before Qatar hosted football’s Fifa World Cup 2022. The second and third phases of the UAE’s Etihad Rail network were also completed promptly, which has allowed Etihad Rail to focus on other schemes such as the passenger rail service, the Hafeet Rail project and the proposed high-speed rail scheme.
Like railways, there are examples of delayed airport schemes that ran over budget. The Midfield Terminal Complex at Abu Dhabi International airport was delayed for years, as was the opening of the first phase of Hamad International airport in Qatar and Muscat International airport in Oman.
Although delays were a significant problem for the construction companies involved in the projects, it is worth
noting that once the projects were completed, they were broadly praised for their quality and step-change in passenger experience.

Future focus
Looking ahead to 2025, the region’s strategic location and competitive edge in aviation will remain, which will support the business case for airport projects. The more interesting challenge will be the region’s ability to fund projects as large as King Salman International airport and Al-Maktoum International airport.
In Saudi Arabia, project spending is being more closely managed than it was in the past, and although people close to the King Salman International airport scheme insist that it remains a strategic priority, the same can be said of many other major projects in the kingdom.
There are also funding questions to be answered for Al-Maktoum International airport. Dubai does not have the financial resources to match Saudi Arabia, and with other infrastructure spending commitments – such as the $5bn Blue Line extension to Dubai Metro and an $8bn stormwater drainage scheme – funding the $35bn airport project will be a challenging undertaking.
High-level concerns are also present for transport links within the region. The warm relations that countries within the region enjoy today may change in the future, and should that happen, the impetus to complete regional rail links will quickly subside.
On the operational level, securing contractors and resources from the supply chain will be an ongoing problem. The record levels of construction awards in recent years mean that construction companies can afford to be selective about the projects they work on, and when they do choose to bid, they no longer feel obliged to slash their prices.
According to regional projects tracker MEED Projects, there were $37.8bn of transport contract awards in 2023, up from the $36.8bn of awards recorded in 2022.
By the end of October 2024, there had been $30.8bn of transport project contract awards. If extrapolated, this suggests a $37bn total for 2024, which is only slightly below the 2023 annual total.
The ability of contractors to hold firm when bidding was evidenced in October 2024, when initial offers were submitted for Dubai Metro’s Blue Line extension. The lowest bids were about $1bn over the project’s official $5bn budget, and a subsequent round of revised prices did not reduce that gap significantly.
Dubai Metro is just one of several major rail schemes due to be awarded soon. As well as the Saudi Landbridge, contractors are also competing for a contract to complete the extension to Riyadh Metro’s Line 2, which is at the bid evaluation stage. A contract to build an entirely new Line 7 was also tendered in September 2024 with a closing date in March 2025.
While it is not entirely reliant on these metro projects and the airports in Riyadh and Dubai moving into construction, their progress will go a long way to determining whether 2025 is a good year or not for transport projects in the region.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
-
 Nebius agrees Neom AI data centre capacity deal
22 October 2026
-
 Riyadh awards $301m Sheikh Jaber Road contract
22 October 2026
-
 Dewa International signs energy and infrastructure MoUs
22 October 2026
-
 EGA’s Al-Taweelah restoration reaches 50% completion
22 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
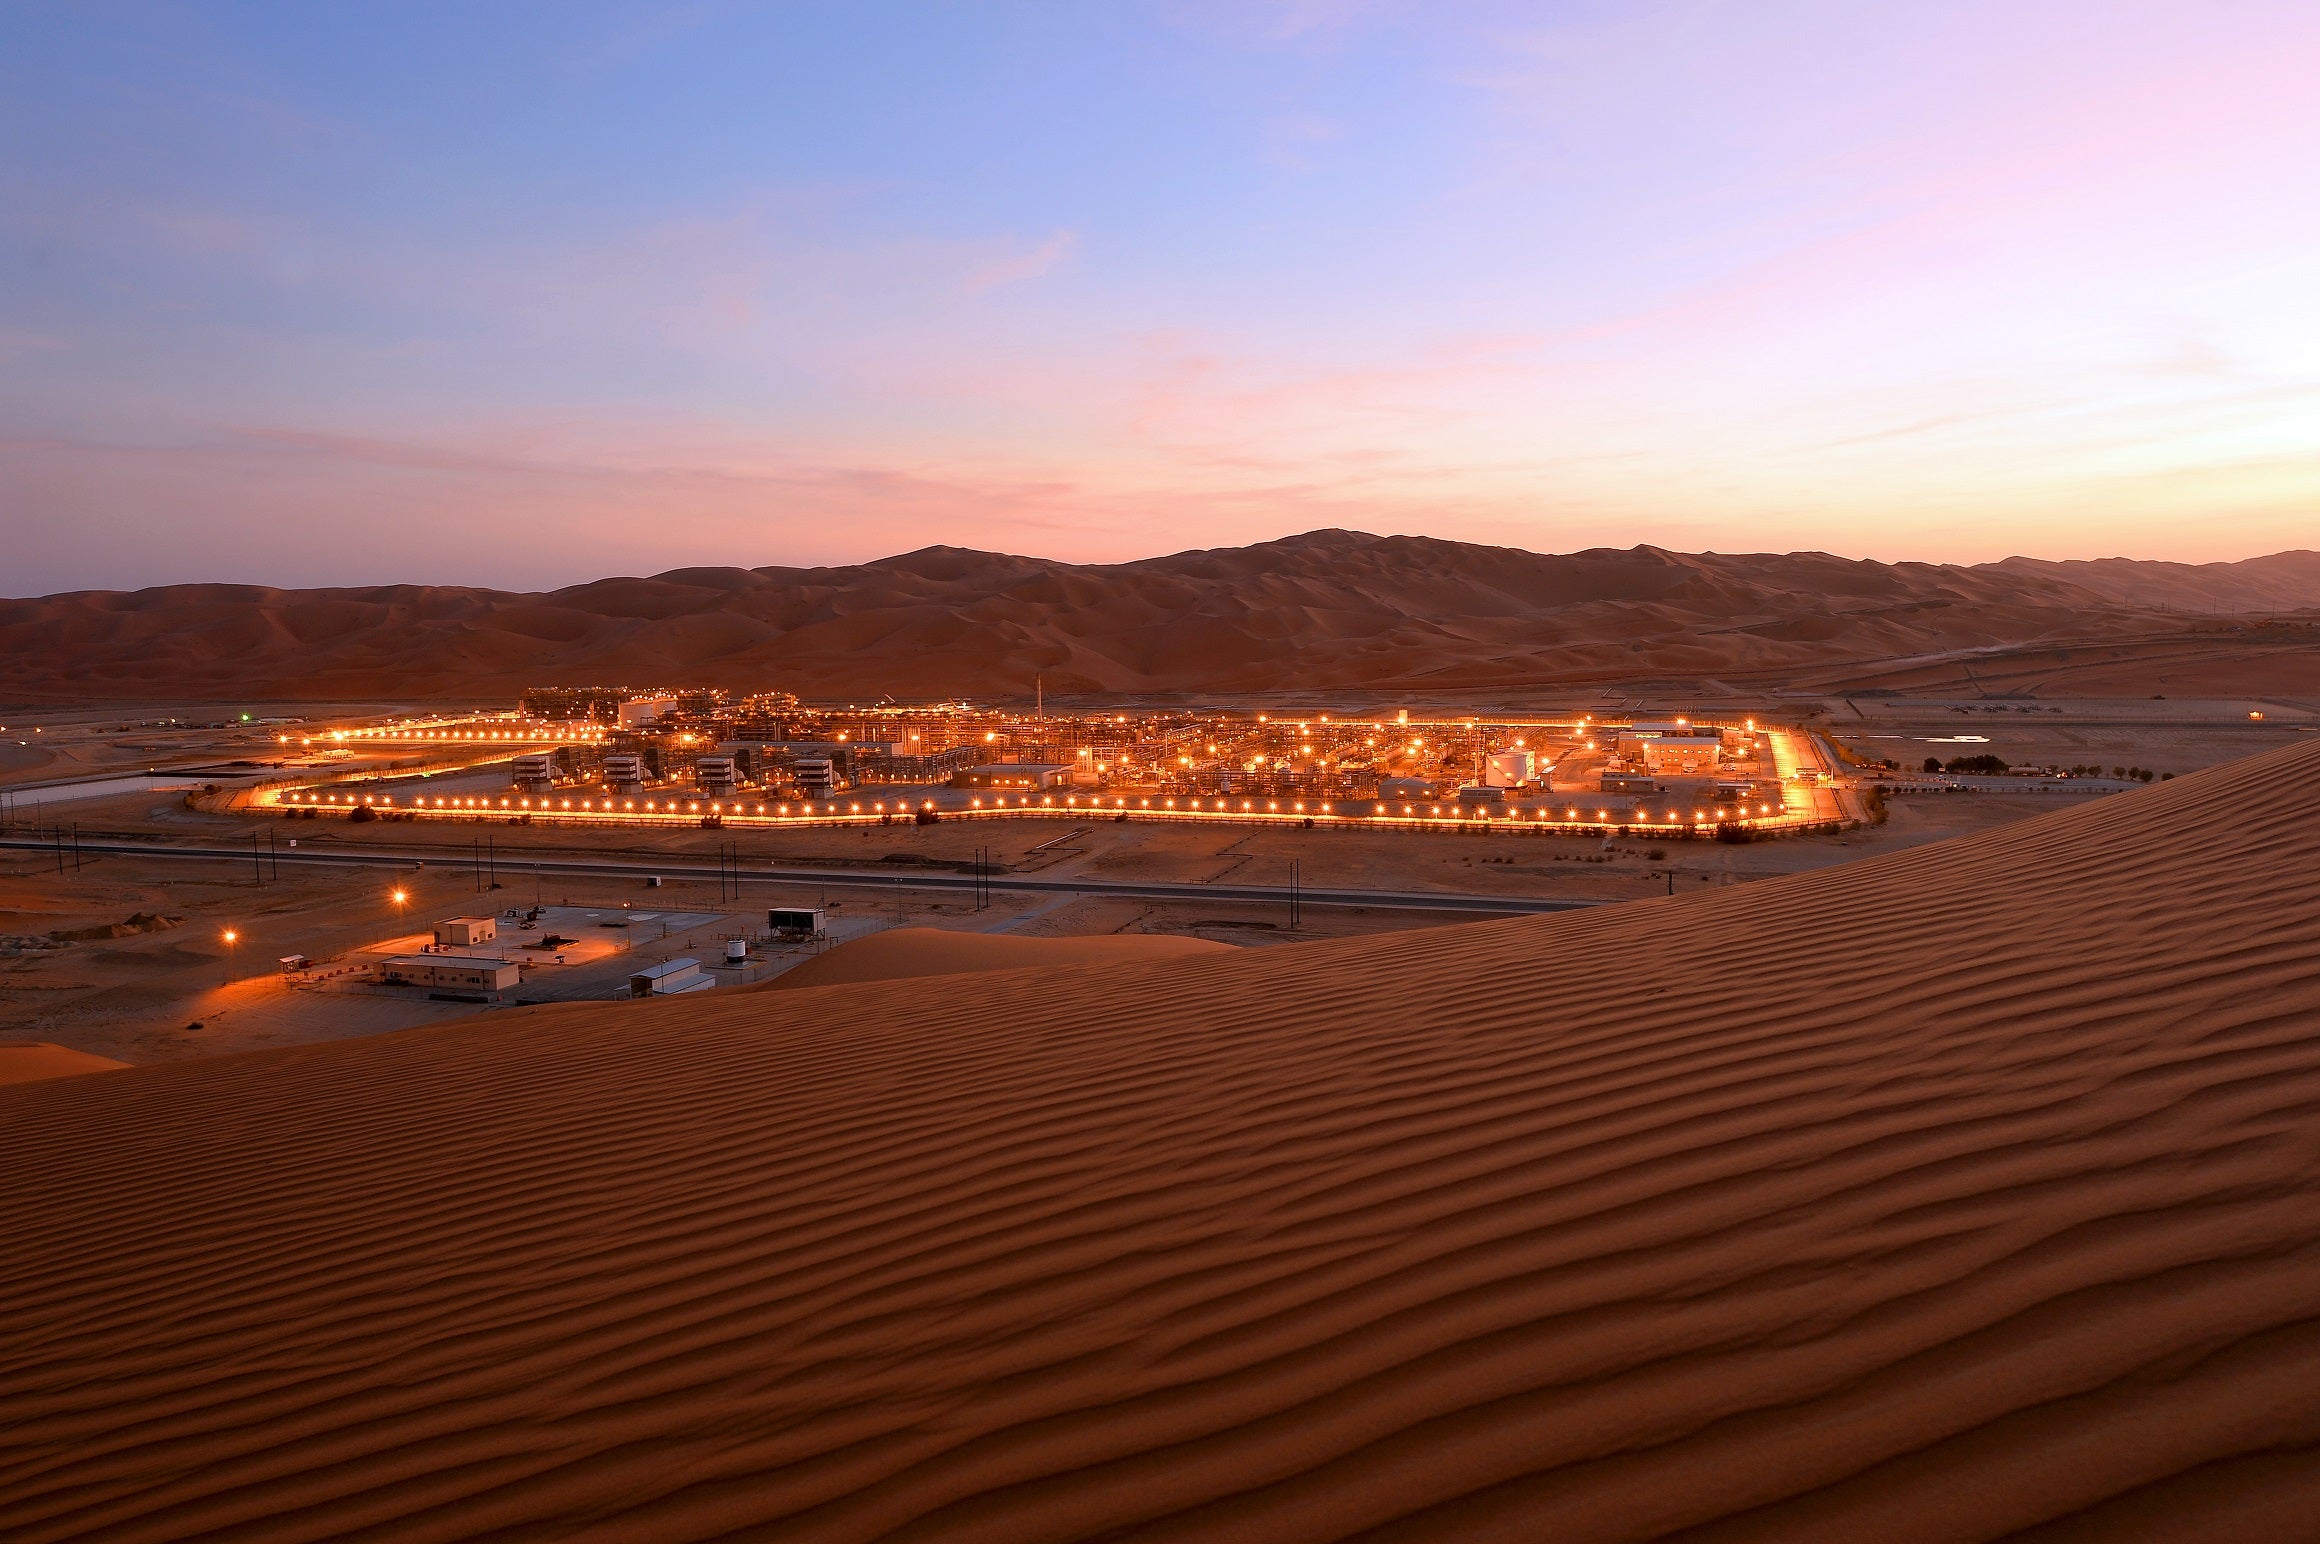
Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
Register for MEED’s 14-day trial access
Oil prices climbed more than 3% on 22 October after a drone targeting Saudi Aramco’s Shaybah oil field development killed two people and injured two others a day earlier, adding to concerns over energy supplies as attacks on Saudi energy infrastructure intensified.
Global benchmark Brent crude hit $112.30 in early trading on 22 October, but later pared gains and was trading at $111.52 a barrel as of 11am GST.
Three residents and a Saudi citizen were killed in two separate incidents in Saudi Arabia’s Eastern Province on 21 October, authorities said, as attacks on the kingdom accelerated following an escalation of hostilities with the Iran-backed Houthi group in neighbouring Yemen.
Overnight, the Saudi-led coalition fighting the Houthis in Yemen announced that it had intercepted and destroyed four drones in the Eastern Province.
Saudi air defences intercepted a drone attempting to target a processing facility at Saudi Aramco’s Shaybah oil field development on the morning of 21 October, the Saudi Ministry of Energy said.
The official Saudi Press Agency (SPA) carried a statement quoting an energy ministry official as saying the attempted attack resulted in the deaths of two residents – a Filipino and a Nepali – and injuries to two others – an Indian and a Pakistani – after debris fell due to the interception.
Following the interception, a fire broke out in a vehicle belonging to a contractor at the Shaybah oil field, outside the facility’s perimeter, with no impact on operations.
Dammam airport attack
Separately, a Houthi attack on King Fahd International airport in Dammam on the evening of 21 October killed an Indian resident and a Saudi citizen.
Eight people were also injured in the attack, including a Saudi national, a Nepali, and two nationals each from India, Yemen and Bangladesh. Injuries ranged from minor to critical, the Saudi General Authority of Civil Aviation (Gaca) said the next day.
“The attack also caused property damage, the extent of which is currently being assessed. Further updates will be provided,” Gaca said, adding that operations had since resumed at Dammam airport.
Saudi Arabia has come under sustained attack from the Iran-aligned Houthi rebel group in October, including strikes on Riyadh’s international airport in what authorities described as the kingdom’s deadliest incidents in years, as the war with the group escalates.
The Houthi militias also struck an administrative building at Aramco’s headquarters in Dhahran, in the Eastern Province, on 13 October, resulting in a limited fire.
The Houthi rebels opened a new front in the regional war between Iran and the US in mid-July, when they breached a four-year truce with Saudi Arabia in Yemen’s civil war, which began in 2014, and started attacking Saudi vessels and Aramco energy assets along the Red Sea, including repeated strikes on the Jizan refinery.
The 1,200-kilometre East-West pipeline operated by Aramco was also hit by Houthi missiles in September, and once directly by Iran in April.
The East-West pipeline transports crude from Saudi Arabia’s Eastern Province oil fields to the Red Sea port city of Yanbu on the kingdom’s west coast. It has a pumping capacity of 7 million barrels a day.
Saudi Arabia relies heavily on the East-West pipeline to bypass the volatile Strait of Hormuz maritime chokepoint and ship crude from its Red Sea coast. Riyadh has increasingly used the line to route exports away from Hormuz since the US-Iran conflict began on 28 February – a tactical advantage most of its Gulf neighbours lack.
Aramco resumed crude exports via the pipeline at the start of October.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20841984/main.jpg -
Nebius agrees Neom AI data centre capacity deal
22 October 2026
Register for MEED’s 14-day trial access
Saudi artificial intelligence (AI) company Humain and data centre developer DataVolt have signed a preliminary framework agreement with Netherlands-based AI cloud company Nebius for up to 50MW of data centre capacity at Oxagon, Neom’s industrial city on the kingdom's Red Sea coast.
Under the proposed agreement, Nebius will become an anchor customer at the planned AI data centre campus.
The contemplated capacity represents half of the initial 100MW currently under construction, which forms part of a planned 360MW first phase.
The capacity is expected to be commissioned in stages from the fourth quarter of 2027.
Humain, which is owned by Saudi sovereign wealth vehicle the Public Investment Fund, and DataVolt began construction on the initial 100MW facility at Oxagon in September. The wider campus is planned to reach 1.5GW of capacity.
The agreement was signed during Nvidia’s GTC event in Berlin, held on 20-22 October. The US graphics processing unit (GPU) designer hosts the GPU Technology Conference (GTC) to showcase advances in AI and accelerated computing.
Nebius is expected to deploy Nvidia-powered computing infrastructure at the Oxagon campus to support its AI cloud business and international customer base.
The project combines Humain’s AI capabilities with DataVolt’s experience in developing, financing and operating digital infrastructure. It is intended to support large-scale AI and cloud workloads for Saudi and international customers.
Oxagon is seeking to position itself as a location for energy-intensive digital infrastructure, supported by pre-zoned industrial land, power resources and subsea cable connectivity to Europe and Africa. The development is also expected to incorporate renewable energy and advanced cooling systems.
The Oxagon campus builds on an agreement signed in February 2025 by Neom and DataVolt to develop data centre infrastructure at the site. That deal involved an investment of about $5bn and envisaged a 1.5GW development.
In September 2025, DataVolt signed a memorandum of understanding with South Korea’s LG Electronics covering cooling systems for the Oxagon data centre project.
DataVolt was founded in 2023 and is a wholly owned subsidiary of Saudi infrastructure developer Vision Invest. Humain was launched in May 2025 to develop capabilities across the AI value chain, including data centres, high-performance computing infrastructure, cloud platforms and AI models.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20837696/main.jpg -
Riyadh awards $301m Sheikh Jaber Road contract
22 October 2026
Register for MEED’s 14-day trial access
The Royal Commission for Riyadh City (RCRC) has awarded an estimated SR1.13bn ($301m) contract to local firm Alomaier Trading & Contracting Company to upgrade a section of Sheikh Jaber Al-Ahmad Al-Sabah Road in the capital.
The project covers the construction of an urban road about 3 kilometres (km) long, with a right-of-way width of about 120 metres.
The scope of work includes the delivery of three interchanges featuring post-tensioned, voided-slab concrete bridges; a cut-and-cover tunnel; and three box culverts designated IC02, IC03 and IC04.
The contract also encompasses pumping and lifting stations, stormwater drainage and irrigation networks, earthworks, asphalt paving, roadway lighting, power distribution systems, mechanically stabilised earth retaining walls and landscaping works.
The award forms part of RCRC’s wider programme to upgrade Riyadh’s arterial road network, decongest critical bottlenecks and expand transportation capacity in the city ahead of Expo 2030 and the 2034 Fifa World Cup.
The contract award follows RCRC’s appointment in May of a joint venture of Riyadh-based Al-Rashid Trading & Contracting Company and Turkiye’s IC Ictas for an estimated SR5bn ($1.3bn) contract to construct another section of Sheikh Jaber Al-Sabah Road.
That project covers 12km from Khurais Road to Al-Thumama Road and is a component of Riyadh’s Second Eastern Ring Road scheme.
Alomaier Trading & Contracting Company has secured several contracts in recent months.
In August, Saudi Arabian Railways awarded the contractor an estimated SR4bn-plus ($1.1bn) contract to add a second track to the first section of the existing phosphate railway in the kingdom’s Eastern Province.
The railway package covers about 100km between AZ1/Nariyah Yard and Ras Al-Khair. Works include track doubling, alignment modifications, utility bridges, culvert widening, hydrological structures, conversion of the AZ1 siding into a mainline track, and enabling works for signalling and telecommunications systems.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20833960/main.jpg -
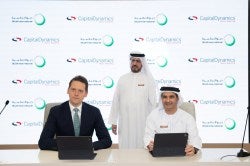
Dewa International signs energy and infrastructure MoUs
22 October 2026
Dubai Electricity & Water Authority’s (Dewa) new development arm, Dewa International, has signed four memorandums of understanding (MoUs) with international partners to explore investment and project development opportunities in the energy, water and infrastructure sectors.
The agreements, signed during Dubai’s Water, Energy, Technology and Environment Exhibition (Wetex 2026), follow the launch of the wholly owned subsidiary in June, as reported by MEED.
At the time, the utility said the arm would be used to export Dubai’s energy and water infrastructure model, with a focus on developing conventional and clean energy projects for global markets.
At Wetex, Dewa International signed an MoU with France’s EDF Power Solutions to explore potential joint participation in solar, wind, battery energy storage and pumped-storage hydropower projects.
A separate agreement with China Energy International Group explores the company’s potential role as an engineering, procurement and construction (EPC) partner for major energy, water and infrastructure projects. The MoU also covers cooperation in project development and EPC services.
A further agreement with UK-based Capital Dynamics focuses on potential joint investments in operational clean energy assets in Europe. The parties will also explore establishing an investment vehicle for future clean energy infrastructure investments.
Dewa International also signed a fourth agreement with Mumbai-Headquartered Tata Consultancy Services, exploring the company’s potential role as a technical consultancy partner. The scope covers technology strategy, information technology and operational technology integration, and asset performance management solutions.
Dewa currently has almost $7bn-worth of power and water projects under execution across the UAE, according to regional projects tracker MEED Projects.
Its flagship Mohammed Bin Rashid Al-Maktoum Solar Park is the largest single-site solar park in the world. The utility is currently advancing the project’s seventh phase, with Abu Dhabi Future Energy Company (Masdar) recently submitting the lowest bid for the project, as exclusively reported by MEED.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20828111/main0128.jpg -
EGA’s Al-Taweelah restoration reaches 50% completion
22 October 2026
Register for MEED’s 14-day trial access
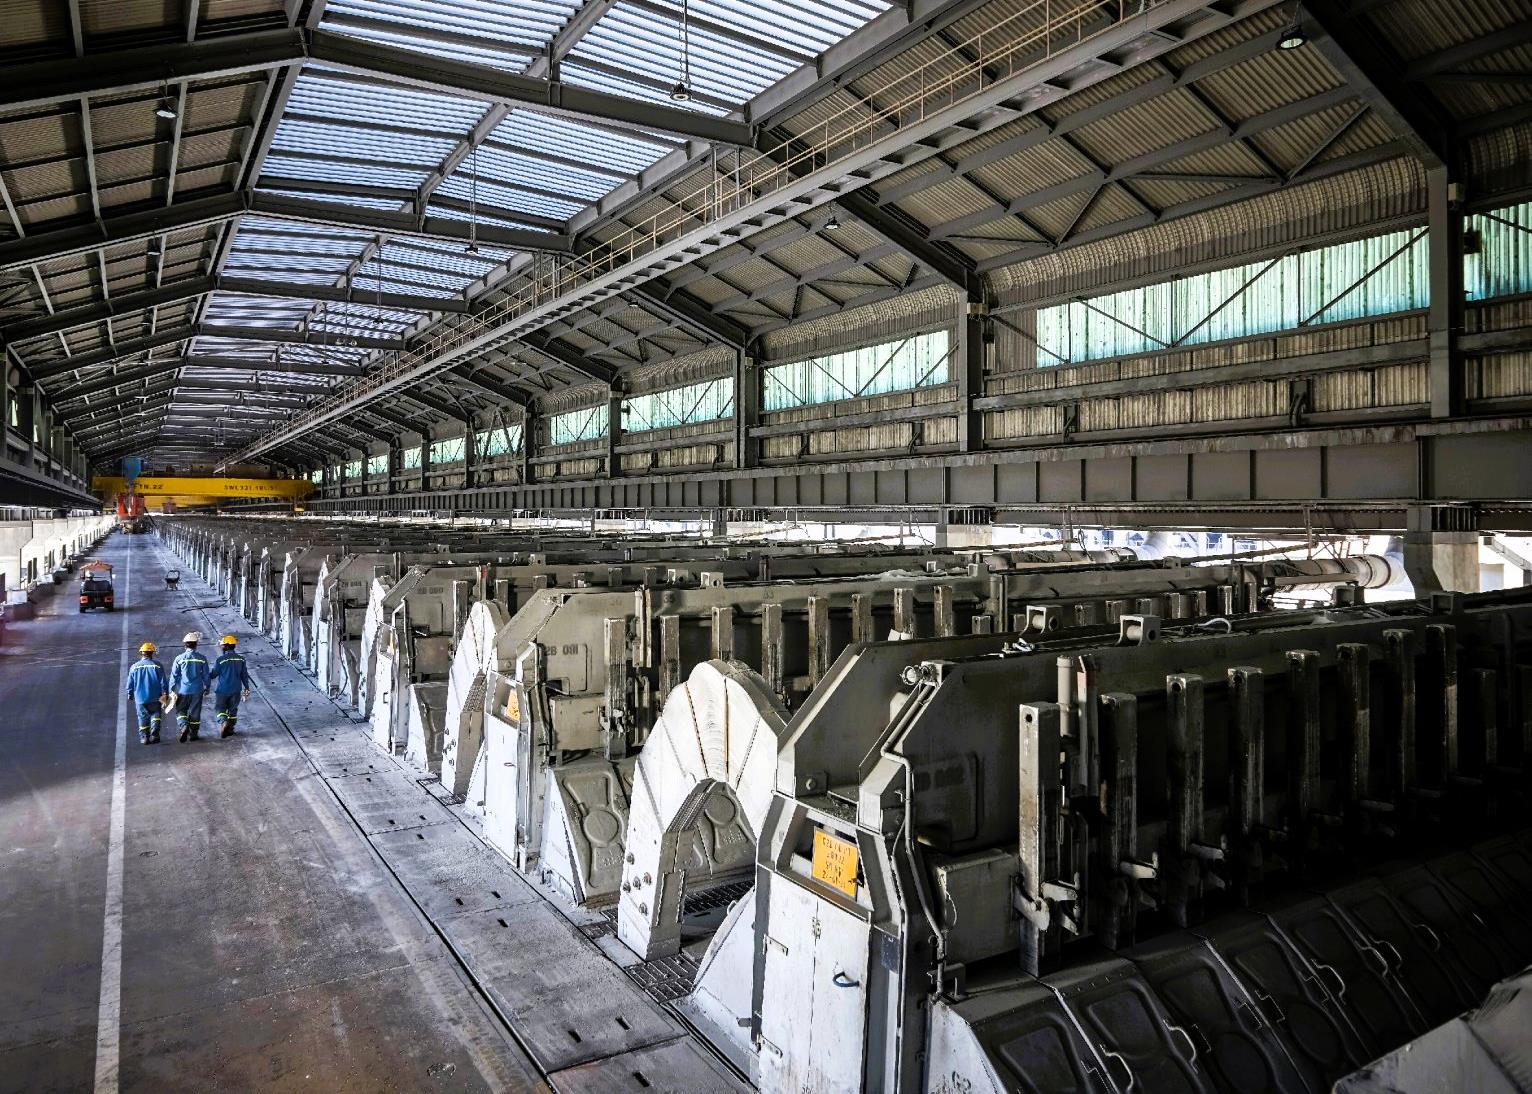
The UAE’s Emirates Global Aluminium (EGA) has announced that half of the reduction cells at its Al-Taweelah smelter in Abu Dhabi, which sustained damage from Iranian attacks in late March, have been restarted.
On 28 March, drone and missile attacks by Iran on Khalifa Economic Zone Abu Dhabi (Kezad), where the smelter is located, led to an emergency shutdown of the facility and injured two EGA employees, who were later discharged from hospital.
To restore hot metal production, EGA said it must progressively repair and restart each reduction cell. So far, 631 of the 1,262 reduction cells at Al-Taweelah have been restarted.
EGA – which is jointly owned by the governments of Abu Dhabi and Dubai – is working on all three potlines at Al-Taweelah in parallel, to accelerate the rate of reduction cell start-ups. Potline 1 was energised on 26 May, followed by Potline 3 on 13 July and Potline 2 on 3 August.
After being restarted, a reduction cell typically takes a week to stabilise and reach full production. Some hot metal is used to restart subsequent reduction cells, with the balance being delivered to EGA’s Al-Taweelah casthouse, to be cast into finished premium aluminium products.
Following the emergency shutdown, molten aluminium froze in every reduction cell at Al-Taweelah, leaving solid metal pads weighing up to 45 tonnes, which needed to be removed. Almost 80% of the reduction cells can then be restarted. The remaining reduction cells require repairs, potlining demolition and relining, depending on how long the reduction cells had been operating before the incident.
Periodically cutting out, repairing and relining reduction cells at the end of their operating life is routine in aluminium smelting. Compared to the normal rolling maintenance programme, EGA has more than tripled its capacity in order to safely repair and restart reduction cells at Al-Taweelah, by optimising workflows, adding equipment, strengthening employee capability and deploying industrial process innovations.
ALSO READ: EGA to receive first Guinea bauxite post-settlement
About 1,000 employees are working on the restoration of hot metal production at the Al-Taweelah smelter, EGA said in a statement on 26 August.
During the restoration, EGA has accelerated the deployment of a technology pilot at Al-Taweelah that would otherwise have required operating reduction cells to be shut down. The pilot E40 upgrades to 13 DX technology reduction cells will be used to prove the performance of the technology before industrialisation across all 808 DX technology cells at Al-Taweelah.
If applied to all DX reduction cells, EGA’s E40 technology has the potential to increase hot metal production by 67,000 tonnes a year (t/y).
EGA’s Al-Taweelah alumina refinery is located next to the Al-Taweelah smelter.
Alumina is the feedstock for aluminium smelters. It is transferred to storage and then into the smelter by a system of conveyor belts.
The Al-Taweelah alumina refinery continues to produce alumina at approximately 50% capacity, EGA said. While the alumina refinery is technically ready to ramp-up further, timing will be based on supply chain dynamics and the optimisation of EGA’s alumina sourcing strategy.
The company announced on 10 July that it had restarted alumina production at its main refinery in Al-Taweelah, adding at the time that it expected to have the technical capability to ramp up to full alumina production by the end of this year.
The Al-Taweelah alumina refinery began production in 2019 and has a nameplate capacity of 2 million t/y.
EGA’s Al-Taweelah smelter consists of 1,262 reduction cells and produced 1.6 million tonnes of cast metal in 2025.
The Al-Taweelah alumina refinery produced 2.4 million t/y of alumina in 2025, and met 46% of EGA’s alumina needs.
EGA also said in July that its site in the Jebel Ali area of Dubai is continuing aluminium production at full capacity. Average daily inbound deliveries of all major raw materials exceed EGA’s requirements to maintain metal production at Jebel Ali and meet the demands of restoration at Al-Taweelah, with raw material stocks in the UAE increasing.
Separately, the ramp-up of production at EGA’s new Al-Taweelah recycling plant remains on track, with full production expected by late in the fourth quarter of this year.
EGA’s recycling plants in the US and Germany, meanwhile, have continued production throughout 2026.
ALSO READ: EGA to receive first Guinea bauxite post-settlement
https://image.digitalinsightresearch.in/uploads/NewsArticle/20827987/main1007.jpg