Saudi banks track more modest growth path
15 September 2023
 MEED's October 2023 special report on Saudi Arabia also includes:
> Gigaproject activity enters full swing
> Infrastructure projects support Riyadh’s logistics ambitions
> Aramco focuses on upstream capacity building
> Saudi chemical and downstream projects in motion
> Riyadh rides power projects surge
> Jeddah developer restarts world’s tallest tower

Surging oil prices may have imbued the kingdom with a renewed sense of economic purpose, but the situation for banks is more complicated.
Economic conditions – notably the higher interest rate climate – have made life more challenging for lenders. They have been acquainting themselves with normality in 2023, after two post-Covid years in which the increase in profit yields averaged 30 per cent.
This year, Saudi bank metrics are solid rather than spectacular. Second-quarter net profits for the country’s 10 listed banks declined by 0.3 per cent in quarter-on-quarter terms to SR17.4bn ($4.64bn), according to figures from Alvarez & Marsal.
Fitch Ratings expects average sector financing growth to slow this year, although remaining above the GCC average of a forecast 5-6 per cent.
According to Junaid Ansari, head of Investment Strategy & Research at Kamco Invest, Saudi Arabia still recorded the strongest growth in outstanding credit facilities during the second quarter of 2023 at 2.5 per cent in quarter-on-quarter terms, while growth in Kuwait, Qatar, Bahrain and Oman was below 1 per cent.
Growth drivers
Aggregate credit facilities in Saudi Arabia grew 5.2 per cent on the start of the year to reach SR2.5tn ($670bn).
“Real estate was the biggest sector in terms of total lending in Saudi Arabia, accounting for 30 per cent of total bank credit facilities and 61 per cent of personal facilities during the second quarter,” says Ansari, citing Saudi central bank data from Bloomberg.
“Lending growth at Saudi banks is still high, albeit decreasing,” says Anton Lopatin, senior director at Fitch Ratings.
“Fitch is forecasting it to be 12 per cent for the whole year 2023, compared to 14 per cent last year. This is partially because mortgage financing affordability has decreased due to higher interest rates and also state subsidies have been tightened.”
Strong demand for mortgage financing, underpinned by a state subsidy programme, has supported the financing growth of Saudi banks in recent years, says Fitch.
Mortgage financing reached SR567bn ($151bn) at the end of the first quarter of 2023, with a compound average growth rate of 35 per cent over the past five years.
But Fitch sees financing growth moderating in Saudi Arabia.
“In the first six months of this year, deposit growth was above lending growth and that wasn’t the case in 2022,” says Lopatin, who points out that if banks’ funding base is growing faster than financing, that reduces pressure on liquidity.
Liquidity levels
Broadly speaking, liquidity is still healthy in Saudi Arabia. Low-cost current account and savings account (Casa) deposits in Saudi Arabia are still among the highest in the GCC, and there is a strong cash-rich government behind the banks in case of need.
After some liquidity tightening in 2022, the Central Bank (Sama) placed SR50bn ($13.3bn) of deposits in the banking sector to reduce the pressure.
“This is a Saudi-specific issue, reflecting that banks’ financing books are growing faster than deposits, and that is putting pressure on liquidity,” says Lopatin.
Casa deposits remain high in the kingdom, even though rising interest rates have led some customers to shift into term deposits. In the first quarter of 2023, Casa deposits still accounted for 56 per cent of total deposits, whereas two years ago the figure was 65 per cent.
“One reason for this [9 per cent decline] is the higher interest rates, but it’s also because banks have been competing for funding to support their growth. There is a huge increase in the cost of funding, but the margin is still very healthy, and the average net interest margin for the first quarter was 3.2 per cent,” says Lopatin.
Despite the higher cost of borrowing – and the attendant risk that this could force clients to default on loans – this should be manageable for most lenders.
“We believe that with adequate controls and policies, asset quality is not a concern at present for the Saudi banking sector,” says Kamco’s Ansari.
“The cost of risk for the sector has been consistently declining over the last quarters and stood at 44 bps, one of the lowest over the last several quarters. This also remains well below the GCC average of 66 bps.”
Loan health
Another source of comfort for Saudi banks is that the higher interest rates are applied to new loans while older loans remain at pre-decided fixed rates.
As a result, non-performing loans (NPLs) are not expected to see any steep increase in the coming quarters – especially, notes Ansari, in light of expectations of rate cuts from next year.
“In the first quarter of 2023, the average NPL ratio was stable at around 2 per cent, and the cost of risk was about 50 bps, which is rather low,” says Lopatin.
In construction and real estate, this could become an issue if higher interest rates result in higher borrowing costs for these companies.
“Not all of them operate with very healthy margins. Thus, their debt service capability will deteriorate. But as of now, we do not see significant upticks in cost of risk or sector average NPL ratios,” says Lopatin.
If Saudi banks are forced to reduce their exposure to real estate, there should be other opportunities for them to grow loan books – not least the Vision 2030-linked series of gigaprojects looking for support. Some of the Saudi banks whose balance sheets have expanded following mergers are now better placed to fund infrastructure projects.
According to the IMF, while mortgage growth has recently moderated, demand for project-related and consumer loans is expected to remain strong, helping offset the impact on profitability from rising funding costs linked to higher policy rates.
This may take a while to materialise. “As of now, we see only moderate financing for companies participating in the execution of the new gigaprojects in Saudi Arabia, but over the longer term, this will support banks’ lending growth,” says Lopatin.
There are other benefits to supporting these projects, not least with the government being the ultimate guarantor, which is positive from an asset quality perspective.
With a strengthening oil price expected to underpin a Saudi economic renaissance, there should be many more opportunities for growth-oriented Saudi banks to get their teeth into.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Lebanon sets October deadline for power generation projects
23 September 2026
-
 Jedco maps next phase of Jeddah airport expansion
22 September 2026
-
 Contractor wins $105m Medina university hospital deal
22 September 2026
-
 Fourteen contractors bid for Oman dam drainage project
22 September 2026
-
 Oman tenders Thumrait Industrial City infrastructure
22 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Lebanon sets October deadline for power generation projects
23 September 2026
Lebanon’s Electricity Regulatory Authority (ERA) has extended the deadline for private sector companies to submit expressions of interest (EoIs) for several upcoming power generation projects.
The new deadline is 15 October. The original deadline was 30 September.
The regulator said the extension follows “requests received from interested applicants for additional time to finalise and submit the required documentation”.
The EoI covers up to five grid-connected solar photovoltaic projects with a combined installed capacity of 350 megawatts-peak. The projects are also expected to include battery energy storage systems with a combined capacity of 1,000 megawatt-hours.
The regulator is also seeking proposals for distributed dual-fired thermal power plants with net capacities ranging from 20MW to 100MW. The plants are expected to run on natural gas as the primary fuel and heavy fuel oil as a backup.
The ERA invited companies to submit EoIs at the beginning of August.
On 11 August, the ERA issued its first set of clarifications following queries regarding the EoI. The clarifications confirmed that “proposed dual-fired plants should be gas-ready”, with natural-gas infrastructure planned but no implementation timeline yet available.
The ERA also said key power purchase agreement (PPA) terms, including duration, tariff structure and indexation mechanisms, will be determined “during a future procurement process”.
Electricity reforms
The EoI comes as the government advances wider reforms to Lebanon’s electricity sector. On 4 September, the Higher Council for Privatisation and Partnership discussed steps to transform the state utility Electricite du Liban (EDL) into a company, including creating a new entity, transferring its assets, and taking measures to protect employees’ rights during the transition.
The government said the restructuring aims to improve the financial sustainability of the electricity sector, recover costs and improve electricity supply.
On 18 September, the council discussed a draft decree to establish the new EDL company, evaluate its assets and separate its activities. However, it deferred a decision for further study.
The ERA was established earlier this year, more than two decades after it was envisaged under Law No. 462/2002 but not implemented due to political delays. The Energy & Water Ministry and EDL previously oversaw the electricity sector.
Lebanon’s electricity sector continues to face insufficient generation capacity, fuel supply constraints, ageing generation assets and limited grid flexibility. These challenges have led to prolonged electricity shortages and increased reliance on private diesel generation and distributed solar systems, prompting the government to seek additional private investment in new generation capacity.
According to the EoI document, the projects are expected to be structured as independent power producer (IPP) schemes. The competent public authority will determine any future contractual arrangements, including PPAs, under the applicable legal framework.
The ERA said the EoI is open to private investors, IPP operators, engineering, procurement and construction contractors, equipment suppliers and consortiums. It aims to assess market interest, identify potential generation projects, and evaluate the technical and financial capabilities of prospective developers.
Respondents must provide information on their technical and financial capabilities, proposed project locations, grid connection plans and relevant project experience.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19906210/main.jpg -
Jedco maps next phase of Jeddah airport expansion
22 September 2026
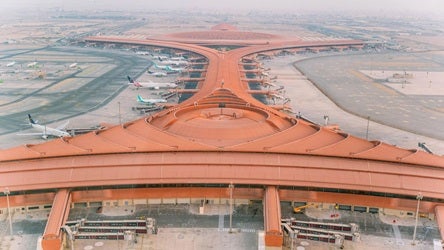
Jeddah Airports Company (Jedco) has outlined plans for the next phase of expansion at King Abdulaziz International airport (KAIA) in Jeddah.
The programme comprises six upcoming contractor packages spanning airside works, terminal upgrades and utilities as Jedco advances its long-term expansion plans.
The opportunities include airfield rehabilitation; a five-year construction framework covering multiple workstreams and facility types; a Terminal 3A (T3A) package; Terminal 1 (T1) optimisation; a fuel farm; and Concourse C works.
The packages cover terminal buildings and ancillary facilities, runways, taxiways and aprons, hangars, fuel systems, airside facilities, supporting infrastructure and utility networks.
Tendering and award activity will be staggered over the next two years. Airfield rehabilitation is targeted for Q3 2026. The construction framework is scheduled for Q4 2026 and will run for five years.
The T3A package is planned for Q1 2027 and will be delivered under an early contractor involvement contract. Local contractors are encouraged to bid as part of a joint venture with an experienced international partner.
T1 optimisation is planned for Q4 2027, the fuel farm for Q2 2027, and Concourse C – currently the latest of the six milestones – for Q2 2028.
The new packages add detail to Jedco’s wider expansion plans disclosed in 2023, when it was reported that the company would invest SR115bn ($31bn) to increase KAIA’s capacity to 114 million passengers a year, with an overall completion target of 2031.
Jedco has recently awarded several significant contracts linked to the airport’s upgrade programme.
In November 2024, a joint venture of local Algihaz Contracting and Turkey’s TAV was awarded a contract to rehabilitate the South Terminal to serve Umrah and Hajj pilgrims, with Singapore’s Surbana Jurong acting as consultant.
Earlier that year, Jedco also awarded France’s Alstom a contract to increase the capacity of the Innovia automated people mover at Terminal 1, including new cars and upgrades to signalling, communications and controls.
Surbana Jurong is expected to play a leading role in future KAIA expansion plans and is currently providing technical advisory and project management consultancy for more than 100 capital projects for Jedco, valued at over SR6bn ($1.6bn).
These upgrades are expected to boost KAIA’s annual capacity in line with Saudi Arabia’s Vision 2030 and National Aviation Strategy, enhancing the experience for domestic travellers and millions of Hajj and Umrah pilgrims.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19877992/main.jpg -
Contractor wins $105m Medina university hospital deal
22 September 2026
Riyadh-based construction firm Al-Mansouria General Contracting Company has been awarded a SR396m ($105.6m) contract to complete the remaining construction works on the Taiba University Hospital project in Medina.
The contract scope includes structural completion, remaining civil works, mechanical, electrical and plumbing installations, specialised clinical fit-outs and medical gas infrastructure to bring the long-stalled facility into operation.
Located on King Khalid Road along Medina’s Third Ring Road, the teaching hospital will have a capacity of 563 beds.
The contract duration is three years, with delivery targeted for late 2029.
The latest award follows a prolonged procurement cycle that began more than a decade ago as part of a public budget drive to expand Saudi Arabia’s higher education infrastructure.
The project’s first phase was initially signed in December 2011 with local firm Al-Muhaidib Contracting under a SR500m ($133.3m) contract.
Groundbreaking for the eight-storey complex took place in July 2013. The project covers a gross floor area of more than 200,000 square metres.
Progress stalled shortly thereafter due to reported structural delays and the reallocation of public capital budgets across the kingdom’s social infrastructure pipeline.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19870032/main.jpg -
Fourteen contractors bid for Oman dam drainage project
22 September 2026
Fourteen contractors have submitted bids for a major drainage project designed to manage flows downstream of Oman’s Al-Khawd Recharge Dam and strengthen flood protection in Al-Seeb, Muscat Governorate.
The proposed works will manage flows downstream of the Al-Khawd Recharge Dam and reduce flood and erosion risks around Al-Khawd village and surrounding assets. The project site includes remote wadi reaches, with access constraints expected to affect construction logistics and temporary access arrangements.
Oman’s Ministry of Agriculture, Fisheries & Water Resources (MAFWR) is the project client.
Bidders submitted their main contract bids on 14 September, with prices ranging from about $126m to $390m.
The bidders and their prices are:
- China International Water & Electric Corporation: $125.94m
- Eksen Project Construction Tourism & Trade (Turkiye): $149.09m
- Ozkar Construction (Turkiye): $149.71m
- United Thumtait Lines (Oman): $149.80m
- Portex Construction Industry & Trade (Turkiye): $154.67m
- Galfar Engineering & Contracting (Oman): $154.80m
- The Arab Contractors (Egypt): $159.70m
- Yildizlar Grup (Turkiye): $172.03m
- Hindustan Construction Company (India): $182.15m
- Strabag Oman (Oman): $205.80m
- AZ Engineers (Oman): $231.19m
- Sarooj Construction Company (Oman): $232.33m
- The Egyptian Contracting Company (Egypt): $239.25m
- Al-Adrak Trading & Contracting (Oman): $389.93m
The project scope includes a drainage network, channel lining and bed protection works, pipelines and concrete box culverts.
MAFWR appointed Muscat-based ARQ and Partners Consulting Engineers to carry out the design works in July 2025. The main contract tender was subsequently issued in May 2026.
Dam pipeline
In parallel, Oman continues to advance a pipeline of major flood protection schemes across the sultanate.
In August, MAFWR received bids from nine contractors to construct the Wadi Rijma flood protection dam (R2A) in Liwa, North Batinah Governorate.
The Wadi Rijma dam project is one of four flood protection dams being planned in the sultanate to intercept floodwaters flowing from the northern Omani mountain range into the coastal plain.
In June 2025, MEED reported that the Islamic Development Bank (ISDB) had extended a $632m loan to the ministry to fund the construction of four major flood protection dams in the sultanate.
The four projects are:
- Wadi Al-Khoud Flood Protection Dam (AK01) in Seeb
- Wadi Rijma Flood Protection Dam (R2A) in Liwa
- Wadi Majlas Flood Protection Dam in Qurayat
- Wadi Ahin Flood Protection Dam in Saham North
In June, the ministry invited contractors to bid to construct the Wadi Al-Khoudh flood protection dam in Wilayat Al-Seeb, Muscat Governorate, reviving a project that had been on hold since 2019.
The design review and supervision services contracts have been awarded for both the Wadi Majlas Flood Protection Dam and Wadi Ahin Flood Protection Dam projects.
The contracts were awarded to local firms Al-Abraj Consulting Engineering and Atlas International Engineering Consultants, respectively. The main contract tenders for these projects are expected to be released by the end of the year.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19868201/main.jpg -
Oman tenders Thumrait Industrial City infrastructure
22 September 2026
Oman’s Public Establishment for Industrial Estates (Madayn) has tendered an estimated RO15m ($39m) contract to develop infrastructure for Thumrait Industrial City.
The tender was issued on 14 September, with bids due by 12 November.
The scope covers site-wide utilities and services, including an internal road network, stormwater channels and culverts. It also includes installing sewerage and water networks, along with landscaping works.
In addition, Madayn intends to build plug-and-play industrial units and a facilities building.
The first phase of the development will cover about 120,000 square metres (sq m).
Thumrait Industrial City is located in Oman’s Dhofar Governorate and spans an area of more than four million sq m.
The project location is close to concession blocks, quarry sites and the Najd agricultural areas. It is positioned to attract industrial investments in sectors such as mining and minerals processing (including gypsum and cement), food production, and a range of light and general manufacturing activities.
In March, Madayn said it is preparing to invest more than RO245m ($637m) to upgrade and expand infrastructure across its industrial cities between 2026 and 2030, as part of efforts to attract new investment and advance economic diversification.
According to media reports, Madayn chief executive Dawood Bin Salim Al-Hadabi said the programme is part of an expanded, phased plan aligned with Oman Vision 2040 and the authority’s long-term Madayn 2040 strategy.
The objective is to deepen Oman’s industrial base and spread growth across the sultanate’s governorates.
Madayn said the pipeline comprises about 90 strategic projects to improve industrial-city infrastructure, extend serviced land and increase the overall ease of doing business for investors.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19866218/main.jpg