Regional diplomacy fails Syrian economy
6 June 2024

Syria’s dire economic position continues to worsen. In a report issued in May, the World Bank predicted the economy will shrink by 1.5% this year, following a 1.2% decline in 2023.
The economy had already contracted by 54% between 2010-21, according to the Washington-based body. Its international trade has also entered freefall, with the value of exports falling from $8.8bn in 2010 to just $0.7bn in 2023, while imports dropped from $17.5bn to $3.2bn over the same period. Syria was once an oil exporter with a large agriculture sector, but it has become reliant on fuel and food imports.
What makes matters worse is that the cost of importing goods is now far higher than it once was, thanks to the collapse in the value of the Syrian pound. In 2011, you needed £Syr47 to buy one US dollar; by 2023, the cost had risen to more than £Syr12,500 for every greenback. Last year alone, the Syrian pound declined by 141% against the dollar, while inflation was running at 93%.
Agriculture fared slightly better in 2023 due to improved weather conditions compared to 2022, but the north of the country suffered a devastating earthquake in February 2023, which killed several thousand people and destroyed thousands of homes.
The authorities have few spare resources to devote to rebuilding areas devastated by natural disasters or the civil war.
The government has lost control over oil revenues to the Autonomous Administration of North and East Syria (AANES), which holds the oil-rich parts of the country. The security challenges of the past 13 years have also led to a downturn in most other parts of the economy and enfeebled the government’s ability to collect taxes.
The World Bank estimates that, after adjusting for inflation, government revenues are now 85% lower than before the war.
The poor living conditions prompted a fresh wave of protests in Daraa and Al-Sweida in August 2023, which then spread to other government and rebel-controlled areas of the country. Locals have much to complain about.
The International Rescue Committee reckons that nearly three-quarters of Syria’s population, or more than 16.5 million people, require some sort of humanitarian assistance and upwards of 90% of Syrians now live in poverty.
Smuggling economy
One area of activity that has prospered has been the production and export of Captagon. This illegal amphetamine-like drug is smuggled in huge quantities into the Gulf, where it finds a ready market despite concerted efforts by the authorities there to clamp down on it.
The World Bank has estimated Syria’s Captagon trade was worth between $1.9bn and $5.6bn a year from 2020-23; that higher figure is not far below the country’s GDP of $6.2bn in 2023.
Those linked to the Syrian trade are thought to earn between $600m and $1.9bn in revenue a year. To put that in context, the revenue generated from all legal exports from Syria last year was $960m.
The Captagon trade might be enriching some figures close to the regime of President Bashar Al Assad, but it is also undermining the country’s wider economic prospects.
One potential avenue for rebuilding the shattered economy is to attract inward investment and the rich Gulf countries are an obvious potential source for that.
However, despite the diplomatic normalisation with Gulf governments over the past few years, the hoped-for investment flows have not materialised, with unhappiness over the Captagon trade a key factor – even if there have been some signs of a reduction over the past year or two.
Caroline Rose, who runs the Washington-based New Lines Institute’s research project on the Captagon trade, said: “We keep tabs of recorded Captagon seizures … and noted a slight dip in Captagon seizures region-wide between 2022 and 2023, so the reduction in seizures could be related to a stabilisation in the supply and production of Captagon.” However, she added that Syria continued to export the drug “at industrial levels”.
Investment brakes
The drug trade is not the only barrier to attracting foreign capital, though. Inward investment has also been hampered by US sanctions set out under the Caesar Syria Civilian Protection Act of 2019, generally known as the Caesar Act, and the myriad problems within the domestic economy are also a major hurdle for any would-be investor.
“When it comes to business and investment, Syria does not really provide any good environment for that. You have high costs, high risks, absence of rule of law, low purchasing power,” said Haid Haid, a consulting fellow at UK thinktank Chatham House, in April. “Businesses in general will not be tempted to go and open businesses there because the gains are low.”
Some regional aid has been flowing in, though. Arab countries raised their contributions from 2% of the total aid in 2022 to 15% in 2023, with the UAE, Kuwait and Saudi Arabia being the largest donors.
Others have been focusing their efforts on the plight of the millions of Syrian refugees displaced inside the country and beyond its borders in Turkey, Jordan, Iraq and Lebanon. Since the war started, around half of Syria’s 23 million-strong population has been displaced, with more than 5 million fleeing abroad.
Some €7.5bn ($8.1bn) of grants and loans were pledged by international donors to help Syrian refugees at the Brussels VIII Conference on Supporting the Future of Syria and the Region on 27 May.
But until a political resolution to the civil war can be found, Syria’s enormous economic and humanitarian crises are unlikely to be solved. Speaking at the Brussels conference, the European Union’s foreign policy chief Josep Borrell said a “Syrian-owned political solution … is the only credible path for all Syrians to live in peace and stability, and for refugees to return home.”
 Gaza conflict renews violence in Syria

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Hydrom targets hyperscalers in round four
19 November 2026
-
 Contractors submit best offers for Oxagon Highway 55
19 November 2026
-
 Construction starts on Damascus hotel and mall
19 November 2026
-
 Kuwait discusses retender of $7.7bn of oil projects
19 November 2026
-
 Saudi Arabia cancels more water tenders
19 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Hydrom targets hyperscalers in round four
19 November 2026
Oman’s green hydrogen company Hydrom is turning to domestic demand to support the sector as export markets slow, says managing director Abdulaziz Al-Shidhani.
Speaking to MEED after Hydrom awarded two projects under its third auction round and launched a fourth round linked to data centres at UN climate change conference Cop31 in Antalya, Al-Shidhani says interest in the third round had been satisfactory but below earlier levels.
“There was a good interest, satisfactory to the auction itself, but it was not as big as it was in round one specifically,” he says. “[That is] reflecting the overall market sentiment when it comes to green hydrogen.”
Hydrom does not disclose the number of auction bids it receives.
Domestic demand
 According to Al-Shidhani, regulatory slowdowns in Europe and slower progress in markets such as South Korea and Japan prompted Hydrom to look for buyers at home.
“We decided last year to start exploring each and every avenue domestically to support decarbonising our industries and introducing green solutions for expanding the industrial base within Oman itself,” he says.
Steel, methanol, mobility, hydrogen-to-power and data centres are among the applications that are under review. A natural gas supply agreement was recently signed for a green direct reduced iron (DRI) plant, which carries a mandate to replace natural gas with green hydrogen in the early 2030s. Hydrom is helping first-round developers in Duqm reach a commercial agreement with the DRI investor.
Data centres
The fourth round, the Green-Powered Data Centre Hydrogen Auction, will be held in Dhofar Governorate. The city of Salalah was chosen for its connectivity, cooler climate and seawater cooling.
Al-Shidhani says the national grid is not yet in a position to supply hyperscalers requiring 100MW or more. The Energy & Minerals Ministry and the Transport, Communications & Information Technology Ministry mandated Hydrom to design a captive power solution.
“Our work yielded that the best techno-commercial proposition is a blend of renewable electrons supported by batteries and supported by up to 20% firming power through hydrogen gensets,” he says.
The auction is designed for integrated consortiums covering power, hydrogen and data centre hubs. Hydrom will also offer matchmaking for investors that want a partner to supply the energy.
Registration for expressions of interest is open until February 2027. Al-Shidhani says a market sounding exercise had given “a very positive signal”. Hydrom plans to issue the request for qualification by the end of the first quarter of 2027, with requests for proposals expected around mid-year.
Round three
The awards went to a consortium of Petrogas E&P and Italy’s Bio3Energy, which plans to produce about 625,000 tonnes a year (t/y) of green ammonium nitrate, and a consortium of PLN Indonesia Power Renewables, Alawi Enterprises and HBA Offshore International, which plans to produce about 400,000 t/y of green ammonia. Combined green hydrogen output is expected to reach about 121,000 t/y by 2032.
The block offered covers 300 square kilometres and could accommodate up to three projects. One winner has an option on a further 100 square kilometres, which would use the full block.
Al-Shidhani says the land usufruct agreements will be registered with Oman’s Housing Ministry within two to three weeks. Developers then have three and a half years for development work, with a final investment decision expected by the end of year three and financial close six months later. Construction is allotted three and a half years, followed by 40 years of operations.
He says the 2032 production date does not represent a delay to Oman’s 2030 target.
“It is a rolling process,” he says. “The 2030 [projects] were signed in 2023 and 2024. It is a moving target.”
One of the new projects has opted for solar power only at the outset. Hydrom does not specify generation or electrolyser technology. Project finance remains the most common funding route, although Al-Shidhani says export credit agencies could also play a role.
This is a demonstration that Oman is able to produce [some of] the lowest-cost hydrogen
First production
The first phase of India-based Acme Group’s project in Duqm, which will produce 100,000 t/y of green ammonia, is expected to start production in Q2 2027. Al-Shidhani, who visited the site in October, says major components were almost complete.
“This is a demonstration that Oman is able to produce [some of] the lowest-cost hydrogen and deliver it competitively to markets, and we are not talking about small quantities,” he says.
He expects the first export cargo to convince sceptical investors that Oman can produce hydrogen for less than $3 a kilogram. Other first- and second-round developers are still negotiating offtake before moving to front-end engineering and design.
Further rounds
Al-Shidhani says the awarded projects use approximately 4% of the land available to Hydrom, and that further auctions are certain. Oman’s strategy targets 8.5 million t/y of green hydrogen by 2050.
Hydrom paused for almost a year after the second auction round, and the timing of future rounds will depend on the market.
“It is all about selecting the right time to go to the market,” he says. “In terms of whether there would be round five or round six, the answer is definitely there would be.”
https://image.digitalinsightresearch.in/uploads/NewsArticle/21573009/main.gif -
Contractors submit best offers for Oxagon Highway 55
19 November 2026
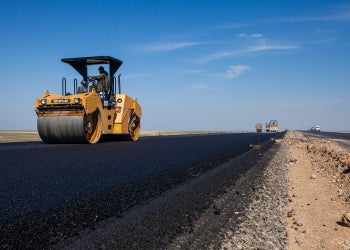
Contractors have submitted their best and final offers for a design-and-build contract to upgrade Highway 55 in Saudi Arabia’s Oxagon region.
The first phase of the project includes the construction of 14 kilometres of road, with two lanes in each direction, as well as one bridge and three interchanges.
The project is expected to take 22 months to complete.
Contractors initially submitted bids on 28 September, as MEED exclusively reported.
Highway 55 connects the Red Sea coast with the mainland in northwestern Saudi Arabia. It is currently the only road providing north-south connectivity between Duba and the Neom region.
MEED reported exclusively in August last year that contractors had submitted responses to an expression of interest notice that Neom had issued earlier that month.
The project is expected to support cargo movement from Duba Port to other parts of the kingdom and the wider region.
Last year, Neom tested a pilot initiative by handling a shipment that travelled from Cairo via the Port of Safaga, across the Red Sea to the Port of Neom, and then inland to Erbil, Iraq.
In a statement, Neom said: “The shipment travelled through an intermodal corridor spanning over 900 kilometres, marking a significant milestone in the kingdom’s transformation into a regional and global logistics hub.”
 READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Gulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21556022/main.jpg -
Construction starts on Damascus hotel and mall
19 November 2026
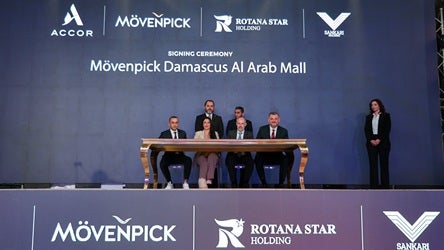
Construction has started on the Movenpick Hotel and Arab Mall development in the Kafr Sousa district of Damascus.
Rotana Star Holding and Sankari Holding are backing the project, which Syria’s Ministry of Tourism is developing under its patronage.
The project marks Accor’s entry into the Syrian market. The France-based hotel group signed an agreement earlier this year to manage the project’s Movenpick Hotel component.
The integrated development will cover more than 90,000 square metres (sq m) and combine hotel, retail, entertainment and supporting facilities.
The Movenpick Hotel will occupy more than 25,000 sq m and include 300 accommodation units. Facilities will include event and celebration halls, restaurants with panoramic views, and health and fitness amenities.
Arab Mall will cover more than 65,000 sq m across seven levels. It will include retail units, entertainment facilities and service areas.
The developers expect Arab Mall to open in the first quarter of 2028, followed by the hotel in the first quarter of 2029.
Accor acquired the Swiss-founded Movenpick brand in 2018. Under the management agreement, Accor will operate the hotel and provide access to its global reservation, distribution and marketing platforms.
The development is expected to create direct and indirect employment across construction, engineering, hospitality, retail and services.
The project is being advanced as Syria seeks to expand its tourism and hospitality capacity.
Syria’s Ministry of Tourism has reported that the country received 3.52 million visitors in the first half of 2026, 111% more than in the same period of 2025.
The ministry said foreign tourist arrivals increased by 448%, while Arab visitor numbers rose by 107%.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21555695/main.jpeg -
Kuwait discusses retender of $7.7bn of oil projects
19 November 2026
State-owned upstream operator Kuwait Oil Company (KOC) is discussing the retendering of upstream projects worth an estimated $7.7bn, according to industry sources.
The tender processes for all four contracts were cancelled earlier this year after the lowest bids exceeded the projects’ approved budgets.
The projects are:
- Separation Gathering Centre 1 (SGC-I) and Water Injection Plant (WIP-1)
Previous low bidder: Tecnicas Reunidas (Spain) – $2.47bn - Separation Gathering Centre 3 (SGC-3) and Water Injection Plant (WIP-3)
Previous low bidder: Larsen & Toubro (India) – $2.48bn - Installation of Water Injection Plant (WIP-4)
Previous low bidder: Petrofac (UK) – $1.48bn - Effluent Water Disposal Plants 1 & 2 expansion project (EWDP 1&2)
Previous low bidder: Larsen & Toubro (India) – $1.30bn
KOC is considering a strategy under which pipeline and network installation work would be removed from the main contract scopes and tendered separately, the sources said.
The company is also planning to relaunch the four main packages under a build-own-operate model rather than the engineering, procurement and construction (EPC) model used previously.
KOC is expected to tender the pipeline and network packages on an EPC basis, or under a similar delivery model.
In addition, KOC is discussing increases to the projects’ approved budgets to enable contractors to submit compliant bids, the sources said.
Since KOC cancelled the four tenders in January, Kuwait’s oil and gas sector and the wider economy have faced disruption linked to the regional conflict that began after the US and Israel attacked Iran on 28 February.
The conflict has reduced shipping through the Strait of Hormuz, limiting Kuwait’s ability to export crude oil.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21532374/main.jpg - Separation Gathering Centre 1 (SGC-I) and Water Injection Plant (WIP-1)
-
Saudi Arabia cancels more water tenders
19 November 2026
Two tenders for a major water pipeline project in Saudi Arabia have been cancelled, marking the second major water infrastructure project in the kingdom to have its tender process called off this month.
The tenders cover Package B and the combined Packages C1 and C3 of the New Water Pipeline to Feed Riyadh City 2 project, being developed by Water Transmission Company (WTCO).
A source close to the project told MEED that bidders were notified of the decision earlier in November.
The three packages have a combined value of about $556m and involve the construction of a long-distance potable-water transmission system to strengthen supplies to Riyadh.
The wider masterplan includes approximately 136 kilometres of pipeline, with diameters ranging from 64 inches to 100 inches. The scope also includes 10 steel storage tanks with capacities ranging from 100,000 cubic metres to 170,000 cubic metres.
According to regional tracker MEED Projects, Saudi Services for Electro-Mechanic Works was appointed as the main contractor for Package B in 2025, with a reported contract value of $279.6m. Another local firm, Al-Rawaf Trading & Contracting, was appointed for Packages C1 and C3, with a combined contract value of $276m. Multiple other contractors submitted bids for the three packages.
As MEED understands, construction was expected to start earlier this year.
The cancellations follow the withdrawal of a tender for a 300-million-litres-a-day seawater reverse osmosis desalination plant at Yanbu, valued at $272m.
As reported by MEED on 16 November, Saudi Water Authority cancelled the Yanbu tender despite India’s VA Tech Wabag receiving the contract award in July 2025.
The contractor disclosed the decision in a filing to Indian stock exchanges, saying the tender was cancelled due to “internal reasons” on the authority’s side.
It is the second time a tender has been cancelled for the project at the final award stage.
It is unclear whether the desalination or transmission-pipeline projects will be retendered and, if so, whether their scopes will remain unchanged. MEED has contacted WTCO for comment.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21527730/main.jpg