Region remains global project finance hotspot
25 October 2024

This package also includes: PPP activity eases back but remains strong
While the Middle East and North Africa (Mena) region has recently become the focus of global attentions for all the wrong reasons – amid surging conflict in the Levant – advisers continue to see the adjacent Gulf as a standout market for project finance.
“The Middle East market has been buoyant compared to the project finance market in many other parts of the world,” says Matthew Escritt, a partner at the UAE office of law firm Pinsent Masons, who has advised on large regional financings.
“By far and away, the Middle East is the place to be if you want to do big-ticket project finance.”
Major deals such as the $6.1bn financing for Neom Green Hydrogen Company, which closed in 2023, affirm the region’s continued affinity with large and sometimes complex transactions that involve senior and mezzanine facilities and bring numerous financial institutions into the mix.
The use of project finance structures across a widening array of sectors – from hard and soft infrastructure, to newer asset classes such as green energy – suggests that the Middle East will remain a hotspot for funding activity.
Ratings agency S&P Global has forecast that alongside the energy sector, the region will see significant investments in transport and social infrastructure, as well as in digitalisation, with large outlays on connectivity and a doubling of data centre capacity as the region’s population continues to grow.
Regional reconfiguration
While the Mena region as a whole has seen an uptick in activity, the picture is not even.
“Activity in Saudi Arabia has seen something of a slowdown after it became clear that some of the kingdom’s more ambitious plans were being recalibrated,” says Escritt.
“Liquidity has become tighter and we’re finding that procurers are taking longer to announce their preferred bidder.”
Appetite among international banks has been weaker for some sectors, such as social infrastructure.
Neom’s large green hydrogen financing of 2023 remains a standout rather than the norm, although local lenders appear ready to step into the breach when circumstances allow. For example, in April of this year, when Neom secured a $2.7bn revolving credit facility to cover short-term financing requirements, it was nine local banks that ended up providing the financing. It was, according to Neom CEO Nadhim Al-Nasr, a “natural fit” within the company’s wider funding structure.
International banks’ interest remains fixed on energy sector and infrastructure projects. Outside of these, says Escritt, the project finance market is dominated by large local banks. This, he says, has contributed to a tighter liquidity environment as these financial institutions run up against exposure limits. “The key to unlocking that market’s undoubted potential is to create conditions that improve the appetite of foreign lenders for Saudi Arabian credits,” says Escritt.
International lenders’ comfort zones were once largely focused on massive financings such as the kingdom’s Sadara petrochemicals project, which in 2013 drew commitments of $12.5bn.
“Frankly, the days of the Sadara blockbuster-type projects are over. But there’s still some substantial projects out there,” says John Dewar, a partner at international law firm Milbank, which specialises in energy and infrastructure financings.
Dewar points out that there are still a fair number of $2bn-$4bn projects in the region, but that it is more challenging to syndicate larger scales of debt. Even export credit agency (ECA) support is not a given in the Mena region.
“Even if they’ve got large export content in them, it’s still more difficult to get them mobilised into oil and gas financings, for example. The ECAs are pulling back from those types of deals,” says Dewar. “Petrochemicals is slightly easier, but nonetheless, over the next couple of years we will see fewer agency lenders involved in the petrochemicals sector than we have at the moment.”
The UAE – Abu Dhabi in particular – remains a bright spot in the region.
“Abu Dhabi has shown that it is very good at getting things done,” says Escritt, whose team helped bring the Khalifa University student accommodation public-private partnership project to financial close – another significant social infrastructure project in the UAE capital.
“There’s a strong appetite among the major project finance players for Abu Dhabi risk – they like it.
“You are also now seeing the larger local banks stepping into this space, with Abu Dhabi Commercial Bank and First Abu Dhabi Bank in particular showing appetite for these credits,” says Escritt.
The Qatari market has proved more sluggish, although the Al-Wakra and Wukair independent sewage treatment plant project – the country’s first – has seen progress this year with a $540m financing on a 75:25 debt-to-equity ratio basis, including a soft mini-perm structure.
Emergent energy markets
Energy has traditionally been a magnet for project financing in the Mena region and should support one of the emerging areas within that segment – carbon capture and storage (CCS), which is an area of focus for regional oil companies.
Saudi Aramco’s first phase of its Accelerated Carbon Capture and Sequestration project is expected to be the world’s largest CCS hub upon completion. Aramco aims to transport and capture 9 million tonnes a year of emissions by 2027 in its first phase.
Carbon-capture financing could prove an attractive opportunity for banks, swelling the liquidity that is already there for hydrogen schemes.
Lender appetite has increased for these new energy schemes. “[Saudi Arabia] had a large splash on solar power recently with Acwa Power financings, while Saudi Aramco will have relatively large financing requirements for its energy transition projects. The [kingdom is] now still very much focused on project finance transactions,” says Dewar.
With Oman pushing green hydrogen projects in Duqm and Dhofar, and Egypt backing an ambitious renewables programme under a structure that investors have found to be attractive and bankable, project financing should make more headway in the low-carbon space across the region.
In renewables, there is more depth in the market and more lenders willing to participate, although as law firm AO Shearman has noted, there remains a deficiency in bankability and unpredictable development costs in green hydrogen schemes.
This piqued interest in non-fossil fuel project funding contrasts with the reduced appetite globally among banks for traditional hydrocarbons schemes. “If you’re looking at oil and gas financing, then it’s increasingly a struggle outside of some of the Chinese banks,” says Dewar. “That’s not to say that in the Middle East there aren’t still a number of local and regional banks that are happy to participate in the market.”
Government support will remain critical in getting centrepiece financings under way in areas such as green hydrogen. And, as AO Shearman notes, given the nature of the supply chain for green hydrogen projects, there is value in including ECA-supported debt in the financing mix. In particular, where Mena projects involve key equipment coming in from outside the region, ECAs have an important role to play in building confidence.
ECAs remain a mainstay in traditional Gulf downstream sectors such as petrochemicals. For example, South Korea’s Hyundai Engineering & Construction has tapped $1bn of project financing support from the Export-Import Bank of Korea for the Amiral petrochemicals project in Saudi Arabia. As the lone South Korean contractor deployed on the estimated $7bn scheme, it therefore enjoys sole access to this project financing facility.
Project sponsors will also be looking to capital market instruments, despite these losing favour in recent years as the global
interest-rate environment rendered proposed bond components in project financings less appealing to many.
With the US Federal Reserve in a gradual monetary easing cycle, however, the use of project-related bonds may begin to revive.
For example, Saudi Aramco has managed to complete some large gas pipeline financings using acquisition facilities that were refinanced in the bond and sukuk markets.
“As the interest-rate environment changes, that’s going to get more people thinking about bond refinancing activity. We’ll see a bit more in a year’s time, when interest rates have come down and investors readjust and start to look for more attractive yields,” says Dewar.
With a different interest-rate climate in place, and more lenders and project backers gaining experience in the new energy schemes that are emerging in the Gulf and the wider Mena region, the hope is that banks will be dipping back into the region with transactions that will maintain its status as the global project finance hotspot for a while longer.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
-
 Dubai approves metro extension to Al-Maktoum airport
10 November 2026
-
 Egypt seeks to accelerate gas pipeline project with Libya
10 November 2026
-
 Omani company signs Kuwait drilling contract
10 November 2026
-
 Adnoc Drilling wins $315m Kuwait offshore rig deals
10 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
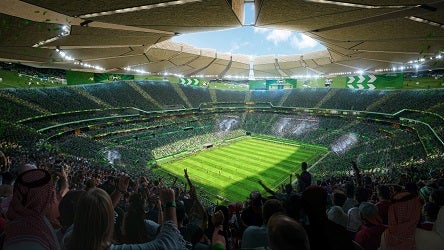
Saudi Arabia’s Sports Ministry has set a deadline of 1 December for a contract covering early works at the King Salman International Stadium in Riyadh.
The tender scope encompasses enabling works, site preparation and initial construction activities. The tender was issued on 11 October, carrying an initial submission deadline of 19 November. Contractors previously submitted prequalification statements for the main design-and-build contract in February.
Designed by US-based architectural firm Populous, the stadium will cover approximately 660,000 square metres (sq m), seat 92,000 spectators and stand adjacent to King Abdulaziz Park. Facilities will feature a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The broader masterplan encompasses more than 360,000 sq m of ancillary facilities, featuring two training fields, fan zones, a closed sports hall, an Olympic-sized swimming pool, an athletics track, and outdoor courts for volleyball, basketball and padel.
Scheduled for completion by 2029, the venue will serve as the home base for the Saudi national football team and host the opening match and final of the 2034 Fifa World Cup.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia plans to build 11 new stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21325461/main.jpg -
Dubai approves metro extension to Al-Maktoum airport
10 November 2026
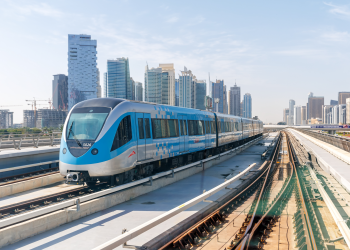
Dubai’s Executive Council has approved a project to extend the Dubai Metro’s Route 2020 to Al-Maktoum International Airport City, with passenger services scheduled to begin operations in 2031.
Sheikh Hamdan bin Mohammed bin Rashid Al-Maktoum, Crown Prince of Dubai, announced the decision following a council meeting held during the UAE Government Annual Meetings 2026.
The rail project forms part of a package of strategic schemes worth over AED11bn ($3bn) approved by the council.
The wider approvals include a comprehensive framework to upgrade community facilities and public services by 2040, with priority given to residential communities for UAE citizens.
حمدان بن محمد يترأس اجتماع المجلس التنفيذي لإمارة دبي ضمن الاجتماعات السنوية لحكومة دولة الإمارات، ويعتمد خلاله موازنة بقيمة أكثر من 11 مليار درهم لمشاريع استراتيجية جديدة في دبي، وخطة شاملة لتطوير الخدمات والمرافق المجتمعية، ومشروع امتداد مترو دبي إلى مطار آل مكتوم الدولي، كما أعتمد سموه خلال الاجتماع نتائج دراسة مستقبل السوق العقاري في دبي.
— Dubai Media Office (@DXBMediaOffice) November 10, 2026
The project approval follows the procurement of detailed design work for the rail link. MEED exclusively reported in September that Dubai’s Roads & Transport Authority (RTA) had awarded US-based engineering consultancy Aecom the design contract for the Route 2020 extension.
The planned extension will run for about 3 kilometres from the existing Expo 2020 terminus station to connect directly with the West Terminal of Al-Maktoum International airport. The scheme will add two new stations to the network.
The existing Route 2020 corridor is a 15km spur that branches off the Dubai Metro Red Line at Jebel Ali station. It comprises 11.8km of elevated viaduct and 3.2km of underground track, serving five elevated and two underground stations.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21301168/main.png -
Egypt seeks to accelerate gas pipeline project with Libya
10 November 2026
Egypt aims to accelerate a range of energy projects with Libya, including gas pipeline links, according to a statement from the Egyptian Foreign Minister Badr Abdelatty.
Other projects include a scheme to refine Libyan crude in Egypt and an electricity interconnection.
Abdelatty’s comments came in a ministry statement after a meeting with Libya’s acting oil and gas minister, Khalifa Abdulsadek, in the Libyan capital of Tripoli.
Egypt is currently trying to address an energy squeeze that has escalated due to elevated global liquefied natural gas (LNG) prices since the start of the US-Israeli war on Iran in February of this year.
In his statement, Abdelatty called for cooperation on petroleum products and the completion of projects to refine Libyan oil in Egypt and re-export it.
He also said that Abdulsadek would visit Cairo soon to continue technical talks with Egypt’s petroleum and electricity ministers.
The statement did not provide details on costs or the status of the projects.
Plans for new gas pipeline links with Libya are just one of several ambitious gas pipeline plans Egypt is pursuing.
In October, the Italian oil and gas company Eni signed the main engineering, procurement, construction and drilling contracts for a project to export gas from reserves in Cyprus using a major pipeline to Egypt.
The project includes contracts with several companies that will develop infrastructure in both Egypt and Cyprus.
The awards included a $170m contract won by Egypt’s Petrojet for a new onshore gas pipeline in Egypt that will help transport gas to Egypt’s Damietta LNG facility.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273777/main.jpg -
Omani company signs Kuwait drilling contract
10 November 2026
Oman’s MBPS has signed a drilling rig contract worth $127.3m with state-owned upstream operator Kuwait Oil Company (KOC).
Under the terms of the deal, MBPS will supply and operate three newly built 1,000-horsepower land rigs for drilling and workover operations, according to a company statement.
The UAE-based oil field services company Adnoc Drilling is a majority shareholder in MBPS.
The chief executive of MBPS, Salim Al-Harthy, said: “This is another important milestone for MBPS and a strong reflection of KOC’s confidence in our capabilities.
“It further strengthens our presence in Kuwait and our commitment to delivering safe, reliable and efficient drilling and workover services across the region.”
He : “My sincere appreciation to KOC for their continued trust, and to our MBPS team for their hard work and dedication in making this possible.”
In October last year, KOC said it planned to spend KD1.2bn ($3.92bn) on its exploration drilling programme through 2030.
The spending was part of a KD9.8bn budget, the company’s biggest ever, allocated for drilling and maintenance of up to 6,193 wells by the end of this decade.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273731/main.png -
Adnoc Drilling wins $315m Kuwait offshore rig deals
10 November 2026
Register for MEED’s 14-day trial access
Abu Dhabi National Oil Company (Adnoc Group) subsidiary, Adnoc Drilling, has been selected for two offshore drilling rig contracts in Kuwait with a combined maximum value of KD96.55m ($315m), according to documents published by Kuwait’s Official Gazette.
The Higher Purchasing Committee of state-owned Kuwait Petroleum Corporation (KPC) has given approval for its subsidiary Kuwait Oil Company (KOC) to award the contracts to the Abu Dhabi-listed drilling contractor after Adnoc Drilling submitted the lowest compliant bids.
While the maximum combined contract value has been confirmed as KD96.55m ($315m), the individual contract values, rig identities, durations and expected commencement dates have not been disclosed.
The approval comes as Kuwait moves to expand offshore exploration and development following a series of discoveries in its territorial waters.
It is currently unclear how Kuwait will provide security for its planned offshore oil and gas projects in the Gulf, adding uncertainty to the outlook for these plans.
On 5 October, KPC chief executive Shaikh Nawaf Al-Sabah reiterated the company’s commitment to developing three major offshore oil discoveries in the region.
KPC initially launched the Al-Seef project to develop the three fields in February, just weeks before the US and Israel attacked Iran, triggering a regional war that has sparked a crisis in Kuwait’s oil and gas sector.
The regional conflict has seriously disrupted shipping through the Strait of Hormuz, a key export route for Kuwaiti oil.
The war has also led to dozens of attacks on Kuwaiti oil and gas infrastructure, with at least one causing damage to a Kuwaiti offshore platform.
This attack took place on 12 July, when a drone struck a KOC offshore drilling platform in Kuwaiti territorial waters, causing damage to the platform and injuring one worker.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273678/main2430.jpg