Region plays high-stakes AI game
11 June 2024
This package also includes: Data centres meet upbeat growth
Artificial intelligence (AI) is a potential enabler for the economic diversification programmes of the GCC’s hydrocarbons-exporting states.
The UAE launched an open-source large-language model (LLM) last year. Falcon 40B, shortly followed by Falcon 180B, cemented the reputation of the Abu Dhabi government-funded Technology Innovation Institute as a major player in generative AI.
With 180 billion parameters and trained on 3.5 trillion tokens, Falcon 180B soared to the top of the Hugging Face Leaderboard, a benchmark for pre-trained LLMs. Falcon 180B outperformed competitors such as Meta’s Llama 2 in areas including reasoning, coding, proficiency and knowledge tests.
The launch of Falcon followed cumulative investments in research, talent acquisition and digital infrastructure. In recent years, Abu Dhabi has formed government-attached agencies and commercial entities backed by its sovereign wealth funds to focus on AI.
One such company is G42, which has partnered with the US’ OpenAI to develop sector-focused generative AI models, and with Microsoft to run applications on Azure and undertake AI skilling initiatives in the UAE and beyond.
Global AI hubs
The UAE aims to become a world-leading AI hub alongside the US and China, but the country will have to tread carefully when choosing partners to avoid geopolitical complications involving its most important security ally and its largest energy client.
Riyadh seems determined to give Abu Dhabi a run for its AI money. The GCC region’s two largest states have placed
separate multimillion-dollar orders for graphics processing units – powerful chips designed for training AI – from top US supplier Nvidia.
They have also formed AI-focused investment vehicles with a view to maximising investments and returns from AI ventures at home and abroad. Abu Dhabi formed MGX, which aims to build $100bn in assets under management within a few years, while Saudi Arabia’s Public Investment Fund formed a $100bn platform to transform the kingdom into a semiconductor and electronics hub, with AI playing a central role in the plan.
In May this year, the Saudi Data & Artificial Intelligence Authority and New York-based technology company IBM launched an open-source Arabic LLM called Allam on IBM’s Watsonx AI and data platform.
With AI promising to be a $1tn market by 2030, it offers attractive opportunities
Computer power
A potential issue facing the determined push for AI leadership is that AI requires enormous computational power and energy, in addition to vast capital and talent.
A recent article published by the World Economic Forum (WEF) suggests that the computational power required to sustain the rise of AI doubles approximately every 100 days.
Related read: Global AI market to top $1tn in 2030
“The energy required to run AI tasks is already accelerating with an annual growth rate between 26% and 36%. This means by 2028, AI could be using more power than the entire country of Iceland used in 2021,” the WEF article says.
The AI lifecycle impacts the environment in two stages. First is the training phase, when the models learn and develop by digesting vast amounts of data; and second is the inference phase, when they solve real-world problems.
At present, the environmental footprint is split, with training responsible for about 20% and inference taking up 80%.
“As AI models gain traction across diverse sectors, the need for inference and its environmental footprint will escalate,” the WEF warns.
A peer-reviewed analysis in the science journal Joule says that a continuation of the current trends in AI capacity and adoption will likely result in Nvidia shipping 1.5 million AI server units a year by 2027.
When running at full capacity, these servers are expected to consume at least 85.4 terawatt-hours of electricity annually, which is equivalent to 100GW of installed capacity in the next three years.
Data centres, which make up the main AI digital infrastructure, already account for about 1%-1.5% of global electricity use.
In a hypothetical scenario in which everyone shifts to AI for mundane tasks such as performing searches on Google, every data centre would effectively experience a 10-fold increase in energy consumption, according to Alex De Vries, a data scientist at the Central Bank of the Netherlands, which conducted the analysis published by Joule.
As a result, the hydrocarbons-exporting and energy-transitioning GCC states – particularly the UAE and Saudi Arabia – appear to be a natural fit for AI, due to the presence of abundant and cheap fossil-fuel or renewable-energy resources, and the need to diversify their revenue sources away from oil. With AI promising to be a $1tn market by 2030, it offers attractive opportunities.
According to a Dubai-based senior executive with a global infrastructure investor, each country and company will eventually need to consider what part they can play in the AI value chain.
Since Nvidia seems to have captured the microprocessor space, the other areas of opportunity are in developing computing power, algorithms and implementation. “Both Saudi Arabia and the UAE have the theoretical capability to grow into the computing power and implementation spaces, which require computing capacity through data centres and medium-skilled manpower to deploy, migrate, train and maintain [AI],” the executive says.
Greening AI
Policy adjustments could be needed to support such advances, especially when it comes to minimising AI’s carbon footprint, even as it enables the curbing of those in other sectors – including the power sector.
In addition to the vast computing and wattage requirements of AI, the region’s arid weather and very hot summer temperatures mean that regional data centres have greater cooling requirements.
To address this, the Dubai state utility has started to build a solar-powered data centre, which is understood to be the first of its kind in the world.
Saudi Arabia, which aims to have 58.7GW of renewable energy installed capacity by 2030 – accounting for about 50% of its electricity production mix – could follow a similar model.
Abu Dhabi’s quantum computer project, in partnership with researchers at Spain’s Qilimanjaro Quantum Tech, is under way.
Unlike a classic supercomputer that operates on binary states, a quantum computer uses quantum mechanics phenomena including superposition and entanglement to generate and manipulate subatomic particles such as electrons or photons, or qubits.
This allows greater processing powers that can enable the performance of complex calculations that would take much longer to be solved, consuming less power than a supercomputer.
The growing electricity surplus in Abu Dhabi, as all four reactors at the Barakah nuclear power plant come onstream this year, could also be allocated to data centres and AI applications.
In addition, Abu Dhabi’s plan to start procuring phase two of its Barakah nuclear energy plant may not only boost energy exports, but could also create sufficient margins to accommodate future AI computing demand.
Related read: Nuclear power will help region achieve AI ambitions
“I don’t know if that means only nuclear power can solve the demand, but it certainly is a good option and carries some strategic advantage as well,” says Karen Young, senior research scholar at Columbia University’s Centre on Global Energy Policy.
While AI needs a significant amount of electricity for computations, there should be savings through productivity increases
Efficiency gains
While it is difficult to accurately quantify and forecast AI’s overall carbon emissions, a holistic view of its overall environmental impact is required.
In theory, while AI itself needs a significant amount of electricity for computations, there should be savings through productivity increases. “Will people need to go to the office less often, and how about the improved performance of machines?” asks the Dubai-based infrastructure investor.
However, it is also important not to overstate AI’s potential benefits to the region’s economies. While AI could be a major driver of economic diversification, Young has yet to be convinced that it will significantly boost the GCC’s GDP growth.
Job creation is a vital element of economic diversification, she tells MEED, but AI is often used to replace roles in the service sector and lower-skilled opportunities, such as those in the retail banking sector. This could impact efforts under way in several GCC states to boost employment among citizens, such as the Saudi Nationalisation Programme and the UAE’s Emiratisation drive.
On the upside, however, AI can be very good at improving efficiencies in the oil and gas industry and the power sector, and at boosting productivity.
The need of the hour appears to be establishing a clear path towards efficient AI deployment, despite the fact that the results of the technology’s full-fledged implementation remain hard to ascertain.
“The UAE is doing a lot to attract skilled people to provide more value-added services, but that is an organic process and needs a more vibrant ecosystem of education institutions – and companies establishing more than just sales offices – to be truly called a hub,” the infrastructure investor tells MEED. “Saudi Arabia is still a bit far from that.”
 Data centres meet upbeat growth

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Borouge puts butene-1 expansion project on hold
16 November 2026
-
 Contractor wins Saudi Energy substation deal
16 November 2026
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
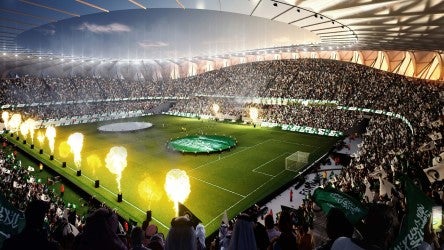 Saudi Arabia tenders World Cup stadiums upgrade works
13 November 2026
-
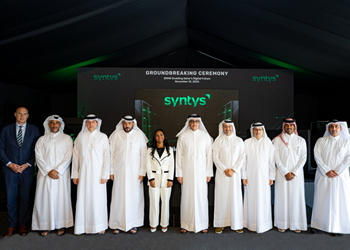 Syntys breaks ground on 20MW Qatar data centre
13 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
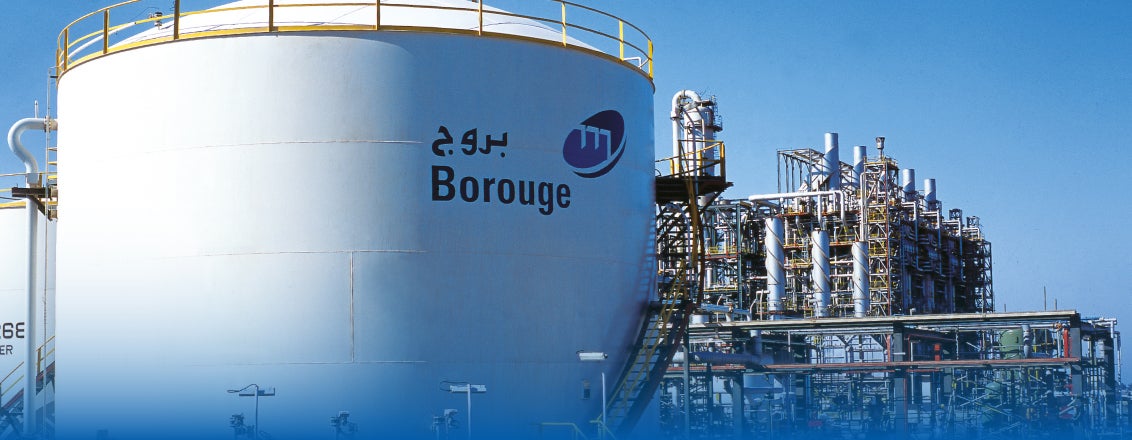
Borouge puts butene-1 expansion project on hold
16 November 2026

Abu Dhabi petrochemicals producer Borouge, now part of Austria-headquartered Borouge International, is said to have put on hold a project to increase butene-1 production from the olefins conversion unit (OCU) at its Borouge 2 facility in Ruwais Industrial City.
Under the proposed project, Borouge planned to produce 60,000 tonnes a year (t/y) of butene-1 from the existing fractionator column while limiting propylene production from the OCU to 500,000 t/y.
The company intended to achieve this by adding co-monomer production technology and selective hydrogenation units, while retaining the capability to run the unit at its original design capacity of 752,000 t/y of propylene and 39,000 t/y of butene-1. The scope also entailed expanding butene-1 storage capacity by converting existing N1 mixed-butane spheres into dedicated butene-1 units.
According to sources, Borouge informed contractors in the weeks after receiving bids that it had decided to shelve the tender.
Contractors submitted technical bids for the engineering, procurement and construction (EPC) package by 1 September 2025, following several extensions to the original 23 June deadline. Borouge had initially released an advanced tender notice in May last year, followed by the main EPC tender on 4 June, and hosted a site visit for bidders on 25 June.
Contractors understood to have submitted bids include:
- Galfar Emirates (UAE subsidiary of Oman’s Galfar Engineering & Construction)
- Target Engineering Construction (UAE)
US-based Lummus Technology was previously awarded the contract to provide the process design package for the new co-monomer production unit as the OCU licensor. Lummus sub-contracted the extended process design package and basic engineering works to South Korea’s Samsung E&A. Borouge had targeted an EPC contract award in the first quarter of 2026.
Butene-1 is a colourless gas primarily used as a co-monomer in the production of high-grade polyethylenes and poly(1-butene), serving end markets such as specialty films, bags and food packaging.
ALSO READ: Borouge prepares to tender construction works for ethane cracker expansion
Borouge International was formed through the combination of Adnoc Group and OMV’s shareholdings in Borouge and Austria-based Borealis, alongside the acquisition of Canada-based Nova Chemicals. In July, Adnoc announced it would transfer its holding in Borouge International to its global investment arm, XRG.
Borouge began operations in 2001 with 450,000 t/y of polyethylene capacity. The Borouge 2 and Borouge 3 expansions raised overall capacity to 2 million t/y in 2010 and 4.5 million t/y in 2014, respectively. Once the Borouge 4 expansion is commissioned, total production capacity will increase from 5 million t/y to 6.4 million t/y, creating the world’s largest single-site polyolefins facility.
Borouge 4 will add two polyethylene units with a combined capacity of 1.4 million t/y (700,000 t/y each) based on Borealis’s third-generation Borstar technology, supplied by a 1.5 million t/y ethane cracker and associated derivative units.
ALSO READ: Borouge restores Ruwais complex after Iranian attacks
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443754/main.jpg -
Contractor wins Saudi Energy substation deal
16 November 2026
Local firm Alfanar Projects has signed a contract with Saudi Energy, formerly Saudi Electricity Company, to build a 115/13.8kV substation in Al-Aqiq, Al-Bahah province, a source confirmed to MEED.
The station will receive electricity at 115kV and step it down to 13.8kV for local distribution. The scope of work includes site preparation, civil works, substation buildings and foundations, and the supply and installation of power transformers and associated electrical equipment.
Seventeen firms submitted bids for the project in May. The bidders included:
- Al-Babtain Contracting
- Al-Gihaz Holding
- Al-Haider Company
- Alfanar Projects
- Cepco
- Energy & Infrastructure Company (Eico)
- Expertise Contracting
- Haif Company
- JAL International
- Maetel Saudi Arabia Construction Company
- Mohammed Al-Ojaimi Group
- Nesma Infrastructure & Technology
- Nour Energy Company
- PA Cost International
- Sama Energy
- Saudi Projects & Supplies Company
- Tareg Al-Jaafari Contracting Establishment
According to regional project tracker MEED Projects, AlFanar Projects had won up to eight awards for substation projects this year, prior to the Al-Aqiq award.
The largest is a contract worth more than SR122m ($32.5m) to construct a 132/13.8kV substation for the Expo 2030 Riyadh site.
The firm was one of four contractors selected by Saudi Energy to deliver electricity infrastructure for the site, MEED reported in August.
Recent contracts include the 380kV Tumair PV substation (#9127), the Busita-C 132/33kV substation, the 132/13.8kV substation north of Al-Kharj (#8721) and the Al-Sahafa 132/13.8kV new substation (#8316).
Saudi Energy has tendered several other 380kV substations and associated transmission lines this year, including projects serving planned solar and wind developments in the kingdom’s central, western and southern regions.
Earlier, in November, MEED exclusively reported that China’s TBEA Shandong Luneng Taishan Cable Company (TBEA) and Egypt’s Elsewedy had submitted the lowest bids for two substation projects in Riyadh Province, estimated to cost a combined $100m.
The tenders for the Thadeq PV and Qiddiya 2 bulk supply points were issued earlier this year, with bids submitted in August and November, respectively.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443095/main.jpg -
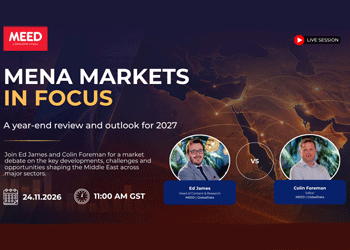
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
Saudi Arabia tenders World Cup stadiums upgrade works
13 November 2026
Saudi Arabia's Sport Ministry has tendered contracts for upgrade works on two stadiums that will host games for Fifa World Cup 2034.
The two tenders cover upgrade works on Prince Faisal bin Fahad (PFBF) Stadium, located in Riyadh, and King Khalid University Stadium in Abha.
The deadline for bid submissions is 22 November.
PFBF Stadium is located in the northern section of King Abdullah Park in the Al-Malaz area of Riyadh. It will have a seating capacity of about 47,000 spectators.
It will host the Round of 32 games for the Fifa World Cup in 2034.
The project was floated as a public-private partnership under a design, build, finance, operate and maintain model last year, but will proceed on a conventional engineering, procurement and construction basis.
King Khalid University Stadium is expected to be upgraded to have over 45,400 seats. It will host the tournament's Round of 16 games.
The stadium is located in the southeast of the city of Abha, in Asir Province.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia planned to build 11 stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the Fifa World Cup 2034 tournament during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21379026/main.jpg -
Syntys breaks ground on 20MW Qatar data centre
13 November 2026
Register for MEED’s 14-day trial access
Qatari data centre developer Syntys has broken ground on a 20MW facility to support hyperscale, cloud, artificial intelligence (AI) and advanced computing deployments.
The groundbreaking ceremony took place on 12 November. It was attended by Qatar’s Communications & Information Technology Minister, Mohammed bin Ali bin Mohammed Al-Mannai, along with representatives from Ooredoo Group, Microsoft, Google, Kahramaa, the National Cyber Security Agency, Qatar Free Zones Authority and local banks.
Syntys said the facility is being developed on an existing company campus, where power, fibre connectivity and an operational team are already in place. The company has yet to disclose the project value or planned completion date.
The facility is designed to meet Tier 3 requirements and accommodate a range of rack densities, including higher-density configurations for graphics processing unit (GPU)-based AI and high-performance computing workloads.
It will operate as a carrier-neutral facility, allowing customers to select connectivity providers and establish network resilience in line with their own technical and operational requirements.
The project forms part of Syntys’ strategy to expand its Qatar platform through acquisitions and new development. Earlier this year, the company acquired QData QFZ, adding two operational, Tier 3-compliant, carrier-neutral facilities to its portfolio.
Syntys now owns and operates four campuses in Qatar, allowing customers to establish primary and disaster-recovery environments at separate in-country locations.
The company also designs and operates the facilities supporting Ooredoo’s sovereign AI cloud, which uses Nvidia Hopper GPUs.
The development comes as Qatar implements its Digital Agenda 2030, which identifies digital infrastructure as one of six strategic pillars and targets about QR40bn ($11bn) in economic impact by 2030.
The data centre is expected to support the growth of in-country digital services and enable sensitive workloads to remain within Qatar’s national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21378257/main1028.png