Mena economies living dangerously
27 December 2023

 Gaza conflict puts the region on edge once again
Middle East and North Africa (Mena) economies enter 2024 in a state of flux. While most are well placed to continue their post-pandemic growth trajectory, albeit in the context of weaker oil sector growth, some states – Egypt and Tunisia notable among them — are under pressure to undertake painful reforms in order to elicit IMF funding packages.
Overall, hopes are high that growth in the Mena region will at least outpace the sluggish performance of the past year. Policymakers across the region will also be looking to double down on the private sector dynamism that saw non-oil growth outpace hydrocarbons performances in 2023.
The overall rear-view mirror is not especially encouraging. The IMF’s Regional Economic Outlook has Mena real GDP slowing to 2 per cent in 2023 from 5.6 per cent in 2022, a decline attributed to the impact of lower oil production among exporters and tighter monetary policy conditions in the region’s emerging market and middle-income economies. Geopolitical tensions – not least the Gaza conflict – and natural disasters in Morocco and Libya have also weighed on regional economies.
GDP growth
The World Bank estimates that in per capita terms, GDP growth across the region decreased from 4.3 per cent in 2022 to just 0.4 per cent in 2023. By the end of 2023, it says, only eight of 15 Mena economies will have returned to pre-pandemic real GDP per capita levels.
Much hinges on developments in the oil market. The Opec+ decision on 30 November to agree voluntary output reductions that will extend Saudi and Russian cuts of 1.3 million barrels a day (b/d), is designed to shore up prices, but it will come at a cost.
Saudi Arabia’s GDP data for the third quarter of 2023 revealed the full impact of output restraint, as the economy contracted at its fastest rate since the pandemic. Saudi GDP notably declined by 3.9 per cent in the third quarter compared to the previous quarter – after the kingdom implemented an additional voluntary 1 million b/d oil output cut.
As a whole, GCC economic growth has been tepid, despite a resurgence in services hotspots such as the UAE, where retail and hospitality sectors have boomed. The World Bank’s Gulf Economic Update report, published in late November, sees GCC growth at just 1 per cent in 2023, although this is expected to rise to 3.6 per cent in 2024.
Oil sector activity is expected to contract by 3.9 per cent in 2024 as a result of the recurrent Opec+ production cuts and global economic slowdown, according to Capital Economics. However, weaker oil sector activity will be compensated for by non-oil sectors, where growth is projected at a relatively healthy 3.9 per cent in 2024, supported by sustained private consumption, strategic fixed investments and accommodative fiscal policy.
“There has not been much GDP growth this year, but the non-oil economy has been surprisingly robust and resilient, despite the fact that the liquidity has not been as much of a driver as it was a year earlier,” says Jarmo Kotilaine, a regional economic expert.
“Of course, the cost of capital has gone up and there have been some liquidity constraints. But we do have a lot of momentum in the non-oil economy.”
In Saudi Arabia, beyond its robust real estate story, the ventures implemented under the national investment strategy are unfolding and semi-sovereign funds are playing a key role in ensuring continuity. “You are seeing more of these green energy projects across the region. It really has been a surprisingly positive story for the non-oil economy,” says Kotilaine.
Government spending
Fiscal policy will remain loose, at least among Mena oil exporters, whose revenues endow them with greater fiscal fire-power.
Saudi Arabia’s 2024 pre-budget statement bakes in further budget deficits, with government spending for 2023 and 2024 expected to be 34 per cent and 32 per cent higher, respectively, than the finance ministry had projected in the 2022 budget. This is not just higher spending on health, education and social welfare, but also marked increases in capital expenditure, including on the kingdom’s gigapojects.
That luxury is not open to the likes of Bahrain and Oman, the former recording the highest public debt-to-GDP ratio in the region at 125 per cent in 2023. Those two Gulf states will need to maintain a closer watch on their fiscal positions in 2024.
There are broader changes to fiscal policy taking place in the Gulf states, notes Kotilaine, some of which will be registered in 2024. “There are areas that the government will play a role in, but in a much more selective and focused manner. Much less of the overall story now hinges on government spending than it used to in the GCC,” he says.
For 2024, a consensus is emerging that the Mena region should see GDP growth of above 3 per cent. That is better than 2023, but well below the previous year and, warns the IMF, insufficient to be strong or inclusive enough to create jobs for the 100 million Arab youth who will reach working age in the next 10 years.
The Mena region’s non-oil buoyancy at least offers hope that diversification will deliver more benefits to regional populations, reflecting the impact of structural reforms designed to improve the investment environment and make labour markets more flexible.
“The labour market in the region continues to strengthen, with business confidence and hiring activity reverting to pre-pandemic levels,” says Safaa el-Tayeb el-Kogali, World Bank country director for the GCC. “In Saudi Arabia, private sector workforce has grown steadily, reaching 2.6 million in early 2023. This expansion coincides with overall increases in labour force participation, employment-to-population ratio, and a decrease in unemployment.”
El-Kogali adds that non-oil exports across the GCC region continue to lag, however. “While the substantial improvement in the external balances of the GCC over the past years is attributed to the exports of the oil sector, few countries in the region have also shown progress in non-oil merchandise exports. This requires close attention by policymakers to further diversify their exports portfolio by further promoting private sector development and competitiveness.”
Regional trade
There is a broader reshaping of the Gulf’s international trading and political relations, shifting away from close ties with the West to a broader alignment that includes Asian economies. The entry of Saudi Arabia, the UAE and Iran to the Brics group of emerging market nations, taking effect in 2024, is a sign of this process.
The decision of the Saudi central bank and People’s Bank of China in November 2023 to agree a local-currency swap deal worth about $7bn underscores the kingdom’s reduced reliance on the Western financial system and a greater openness to facilitating more Chinese investment.
“You want to be as multi-directional, as multi-modal as you can,” says Kotilaine. “For the Gulf states, it is almost like they are trying to transcend the old bloc politics. It is not about who your best friend is. They want to think of this in terms of a non-zero sum game, and that worked very well for them during the global financial crisis when they had to pivot from the West to the East.”
Near-term challenges
While long-term strategic repositioning will influence Mena economic policy-making in 2024, there will be near-term issues to grapple with. High up that list is the Gaza conflict, the wider regional impacts of which are still unknown.
Most current baseline forecasts do not envisage a wider regional escalation, limiting the conflict’s impacts on regional economies. The initial spike in oil prices following the 7 October attacks dissipated fairly quickly.
Egypt is the most exposed to a worsening of the situation in Gaza, sharing a land border with the territory. However, the Gaza crisis is not the only challenge facing the North African country
Elections set for 10 December will grant President Abdelfattah al-Sisi another term in office, but his in-tray is bulging under a host of economic pressures.
Inflation peaked at 41 per cent in June 2023. A currency devaluation is being urged, as a more flexible pound would offer a better chance of attracting much-needed capital inflows.
The corollary is that it would have to be accompanied by an interest rate hike. Capital Economics sees a 200 basis point increase to 21.25 per cent as the most likely outcome, ratcheting up the pain on Egyptian businesses and households.
A deal with the IMF would do much to settle Egyptian nerves, with a rescue plan worth $5bn understood to be in the offing. But Egypt has to do more to convince the fund that it is prepared to undertake meaningful fiscal reforms. Privatisations of state assets, including Egypt Aluminum, will help.
Other Mena economies will enjoy more leeway to chart their own economic path in 2024. Iraq has achieved greater political stability over the past year, and may stand a better chance of reforming its economy, although weaker oil prices will limit the heavily hydrocarbons-dominated economy’s room for manoeuvre.
Jordan is another Mena economy that has managed to tame inflation. Like Egypt, however, the country is also heavily exposed to what happens in Gaza.
Few could have predicted the bloody events that followed the 7 October attacks. Mena region economic strategists will be hoping that 2024 will not bring further surprises.
|
Can the Gulf build back better? The GCC has done much to put itself on the global map through effective reputation building. But, notes regional economic expert Jarmo Kotilaine, the focus of policy will now have to change from building more to building better, making the existing infrastructure and systems operate with greater efficiency. Above all, the region will need dynamic and adaptable companies and an economically engaged workforce. “The reality is the GCC has a lot of capital committed to the old economy. There is the question of how much of that should be upgraded, or made to work better, because fundamentally, one of the region’s big challenges is that local economies have very low levels of productivity.” It is by upgrading what the GCC has, by incorporating technology and energy efficiency, that the region can make productivity growth a driver, he tells MEED. “One area where GCC economies have started to make progress is in services: logistics, tourism, financial services. This is bringing money to the region,” he says. “We are also starting to see new potential export streams with things like green energy, and obviously green hydrogen. But the Gulf states have to manufacture more, and they have to manufacture better.” |

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Ashghal tenders Mekeines-Umm Bab link road
30 October 2026
-
-
 Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
-
 Oman announces $790m industrial investment deals
30 October 2026
-
 Sabic swings back to profit in Q3 with $224m net income
30 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Ashghal tenders Mekeines-Umm Bab link road
30 October 2026
Qatar’s Public Works Authority (Ashghal) has tendered a contract for the design and construction of the Mekeines to Umm Bab Link Road and associated infrastructure.
The tender was issued on 29 October, with a bid submission deadline of 22 December.
The scope comprises:
- Highway works, including main carriageways, access roads, grade-separated ramps, junctions and tie-ins to existing networks
- Dedicated non-motorised user facilities, footpaths and shared-use cycle paths
- Structural installations, including camel underpasses, a QatarEnergy culvert and gateway monumentation
- Extensive dry and wet utilities, encompassing Kahramaa potable water and electrical transmission networks, surface water drainage, street lighting and dedicated communication networks for Ooredoo, the Qatar National Broadband Network and the Qatar Armed Forces
Under the scope of work, the appointed contractor will execute full design verification and turnkey construction under Ashghal’s standard Building and Engineering Design and Build General Conditions of Contract (2018 Edition) on a lump-sum basis. Engineering subconsultants must hold Grade 1 or International classification with the Ministry of Municipality across civil, architectural, mechanical and electrical engineering disciplines.
The contract stipulates an execution period of 1,260 calendar days (3.5 years) from the commencement date, followed by a 400-day maintenance liability period.
The project is open to local and international contractors classified as Grade A in roads specialisation by Qatar’s Ministry of Finance (MoF).
Foreign firms may participate independently or within a joint venture, provided the joint venture leader holds the requisite classification, by registering through the MoF e-procurement portal with attested equivalent certification from their home countries.
The planned corridor is located within Al-Rayyan Municipality across Zones 82 to 84 in the Al-Sheehaniya area.
At its eastern end, the link road begins about 40 kilometres southwest of central Doha, tying into the Salwa Road Interchange 42. At the western terminus, it connects to the roundabout adjacent to Umm Bab on the Abu Samra to Dukhan road (Route 39).
The link road serves as a critical logistics corridor connecting western settlements, residential districts and industrial installations, including concession areas operated by QatarEnergy.
The western 7.5km of the alignment passes directly through the QatarEnergy District, where the corridor runs parallel to active oil and gas pipelines and includes a designated gateway monument.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21041383/main.gif -
Contractors prepare bids for Petro Rabigh bottom-of-the-barrel project
30 October 2026
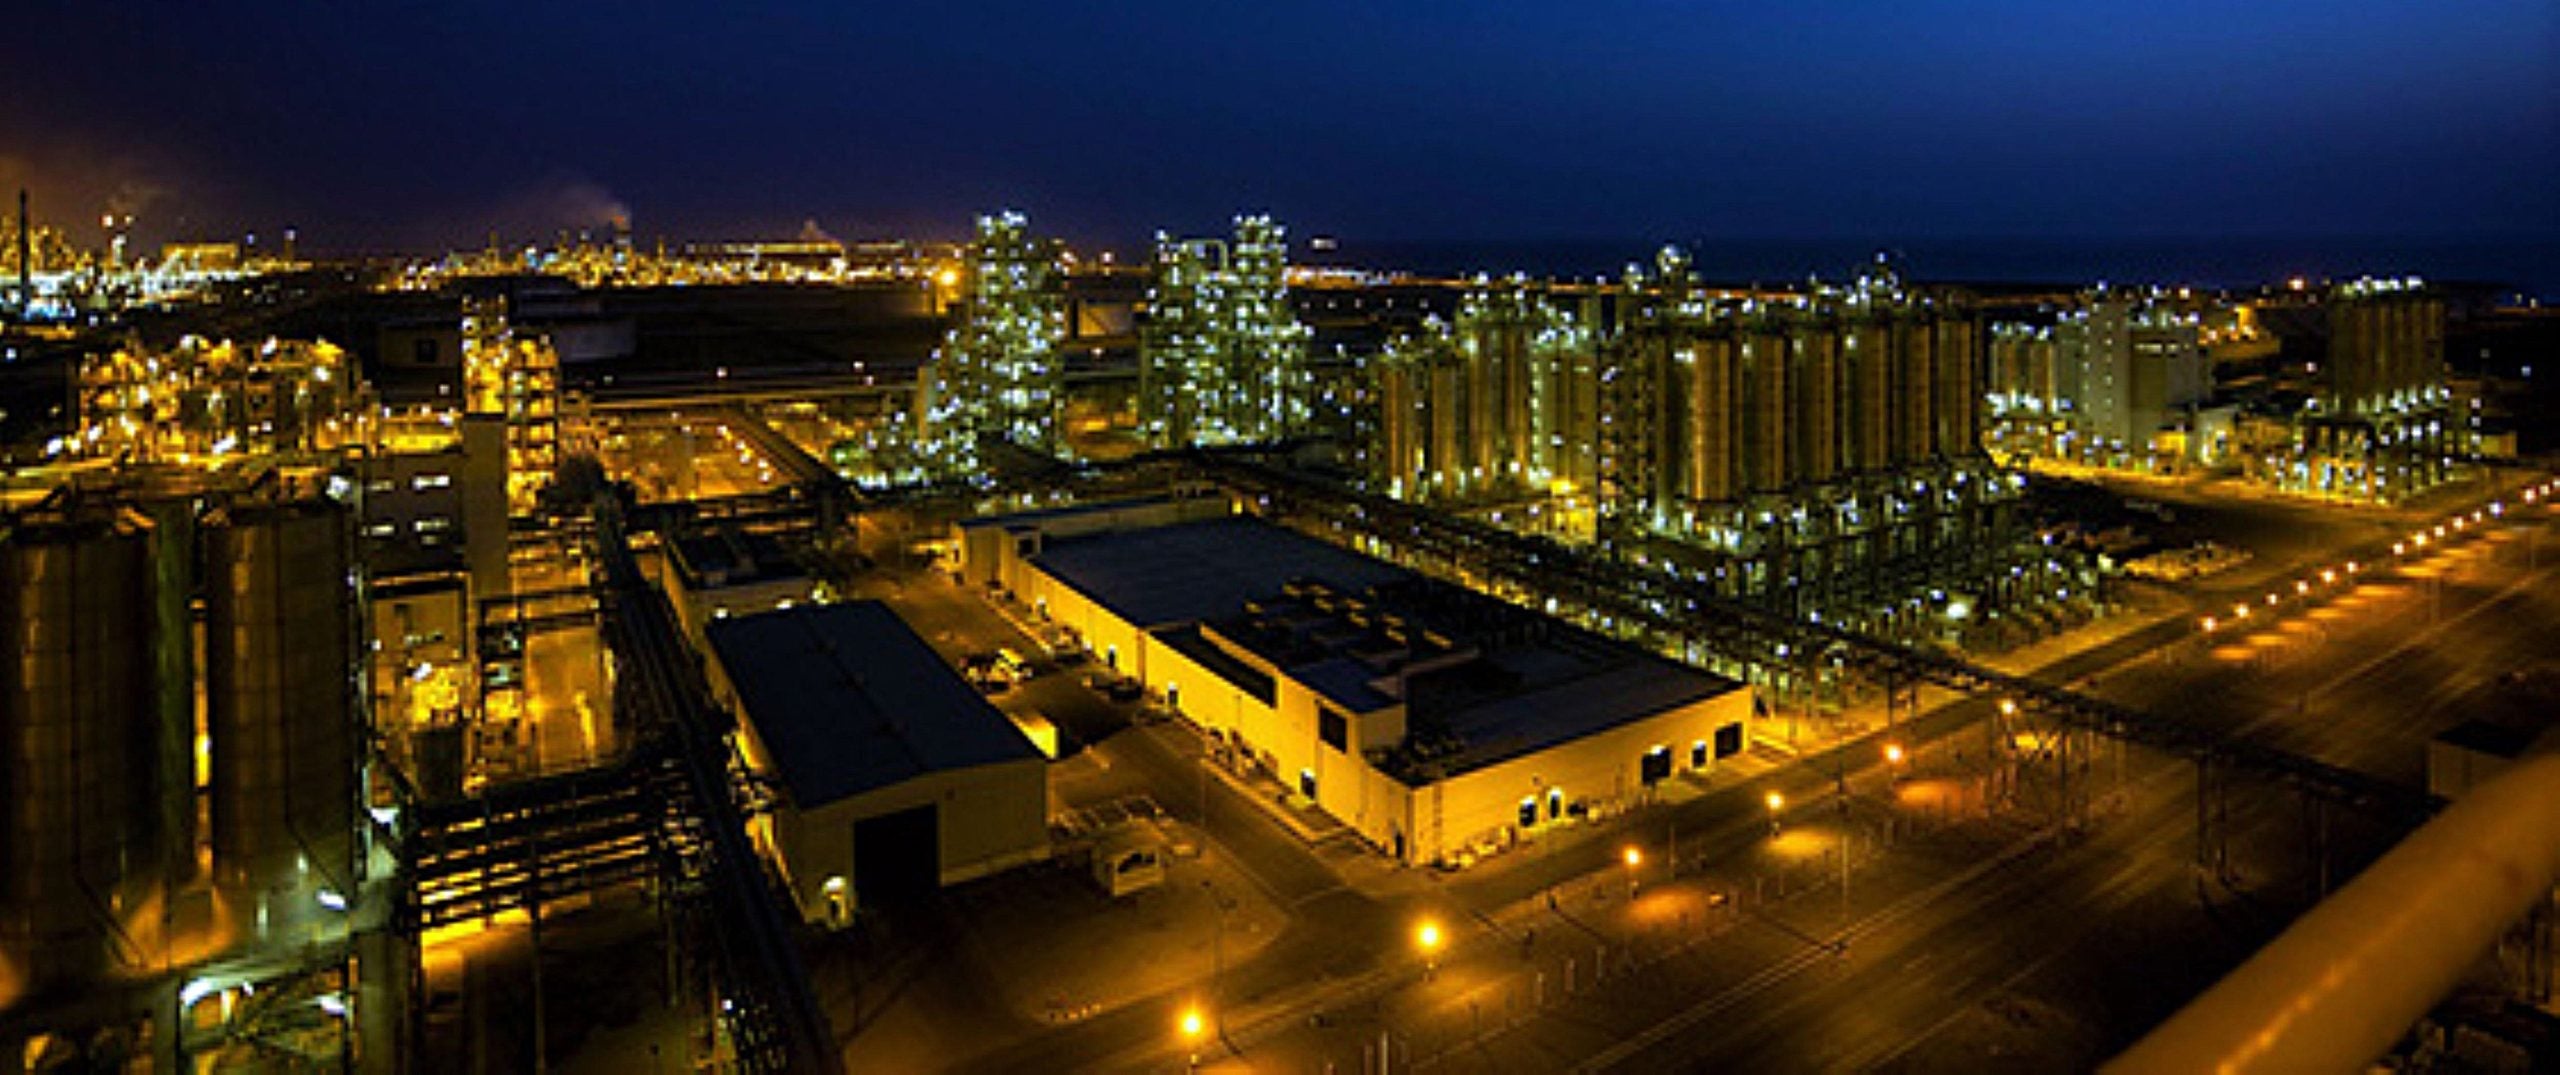
Contractors are preparing proposals for Saudi Arabia’s Rabigh Refining & Petrochemical Company (Petro Rabigh) for a major project to increase output and improve the efficiency of its integrated refining and petrochemicals complex in Rabigh, on the kingdom’s Red Sea coast.
Petro Rabigh’s downstream complex, which is majority-owned by Saudi Aramco, includes a topping refinery with a 340,000-barrel-a-day (b/d) crude-distillation unit, a 47,000 b/d hydrotreater, a 12 million-cubic-feet-a-day hydrogen plant, a 75,000 b/d naphtha Merox unit and a 60,000 b/d kerosene Merox unit. The complex also includes supporting utilities, product tankage and a marine terminal.
The main objective of the bottom-of-the-barrel project is to convert low-value, high-sulphur fuel oil and heavy-residue streams – which account for about 20% to 22% of refinery output – into higher-value, cleaner products, including diesel and lighter distillates.
Petro Rabigh aims to achieve residue-conversion capacity of about 64,000 to 75,000 b/d by adding integrated fuel-oil upgrading and diesel-treatment units.
The company issued the main tender for engineering, procurement and construction (EPC) works earlier this year. Contractors have until 19 November to submit proposals, sources told MEED.
The following companies are understood to be among those bidding for the project:
- CTCI Corporation (Taiwan)
- JGC Corporation (Japan)
- Larsen & Toubro (India) / Technip Energies (France)
- Tecnicas Reunidas (Spain)
The overall scope of work on the project covers the construction of the following units:
- A light-naphtha isomerisation unit
- A deasphalting and dewaxing unit
- An ebullated-bed processing unit
- A sulphur block, comprising sulphur-recovery, acid-gas-removal, sour-water-stripping and sulphur-forming units
- Sales-gas allocation facilities and associated pipeline works
- Utilities outside battery limits
- Auxiliary piping modifications
- Utility and hydrocarbon tie-ins
Petro Rabigh appointed Australia-headquartered Worley last year to carry out front-end engineering and design (feed) work for the bottom-of-the-barrel project.
MEED also reported that Petro Rabigh appointed Worley to provide engineering and project-management consultancy (PMC) services for the project in the first quarter of this year.
Under the contract, Worley will carry out engineering studies and PMC functions. It will also support the development of cost estimates, project-specific execution procedures and technical procedures in line with Saudi Aramco guidelines. The work covers both the design-basis scoping-paper stage and the subsequent feed stage.
Petro Rabigh will draw on Worley’s expertise in design, procurement and processing technologies, including light-naphtha isomerisation; vacuum-residue processing through deasphalting and dewaxing; an ebullated-bed configuration integrated with the diesel-hydrotreating section; and unconverted-oil hydrotreatment.
Worley recently confirmed its contract award from Petro Rabigh, saying it will deliver engineering, project management, procurement support and related consultancy services for projects across its client’s portfolio.
The scope includes developing design-basis documents, conducting technical evaluations, preparing cost estimates, supporting feed tender packages and providing detailed engineering and execution-phase support as projects advance through development and delivery.
The services will support the evaluation and development of potential new facilities and infrastructure across the complex, including process units, utilities, sulphur recovery facilities and associated infrastructure.
“The work will help Petro Rabigh advance future projects aimed at enhancing the long-term value and performance of its refining and petrochemicals operations,” Worley said in a statement on 28 October.
Separately, Petro Rabigh awarded US-based KBR a 10-year maintenance contract in February to support its polymer plants in Rabigh.
KBR’s Technology Led Industrial Solutions business line will execute the operations and maintenance contract, sources told MEED. The business operates within the Houston-headquartered company’s Technology Solutions portfolio.
In March 2024, Petro Rabigh also awarded KBR a similar five-year asset-condition-monitoring contract. Under that programme, KBR is providing predictive-maintenance services at Petro Rabigh’s main plant.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21032785/main.jpg -
Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
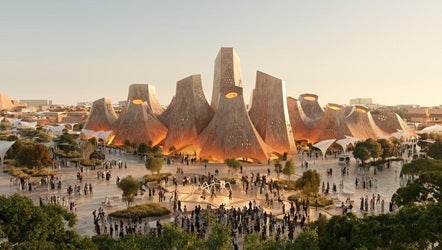
Contractors submitted bids on 25 October for a contract to design and build the Saudi Arabia pavilion at the Expo 2030 Riyadh site.
The facility will include exhibition halls, VIP and protocol areas, event and performance spaces, meeting rooms, food and retail outlets, and back-of-house facilities.
The pavilion will host exhibitions, cultural and commercial showcases and official events throughout the six-month expo.
External public realm works are also included.
Expo 2030 Riyadh Company (ERC), tasked with delivering the Expo 2030 Riyadh venue, issued the main tender on 19 May, as MEED exclusively reported.
Earlier this week, ERC appointed UK-based Mace as procurement advisory consultant for Expo 2030 Riyadh, supporting procurement activities across the programme.
Under the appointment, Mace will provide procurement services and advise on the management and delivery of procurement activities, with the aim of supporting the expo’s wider programme objectives.
Expo 2030 Riyadh will run from October 2030 to March 2031 with the theme Foresight for Tomorrow, with host authorities projecting approximately 42 million visits.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event.
Situated north of the Saudi capital, the site is located near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched Expo 2030 Riyadh Company – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21031590/main.jpg -
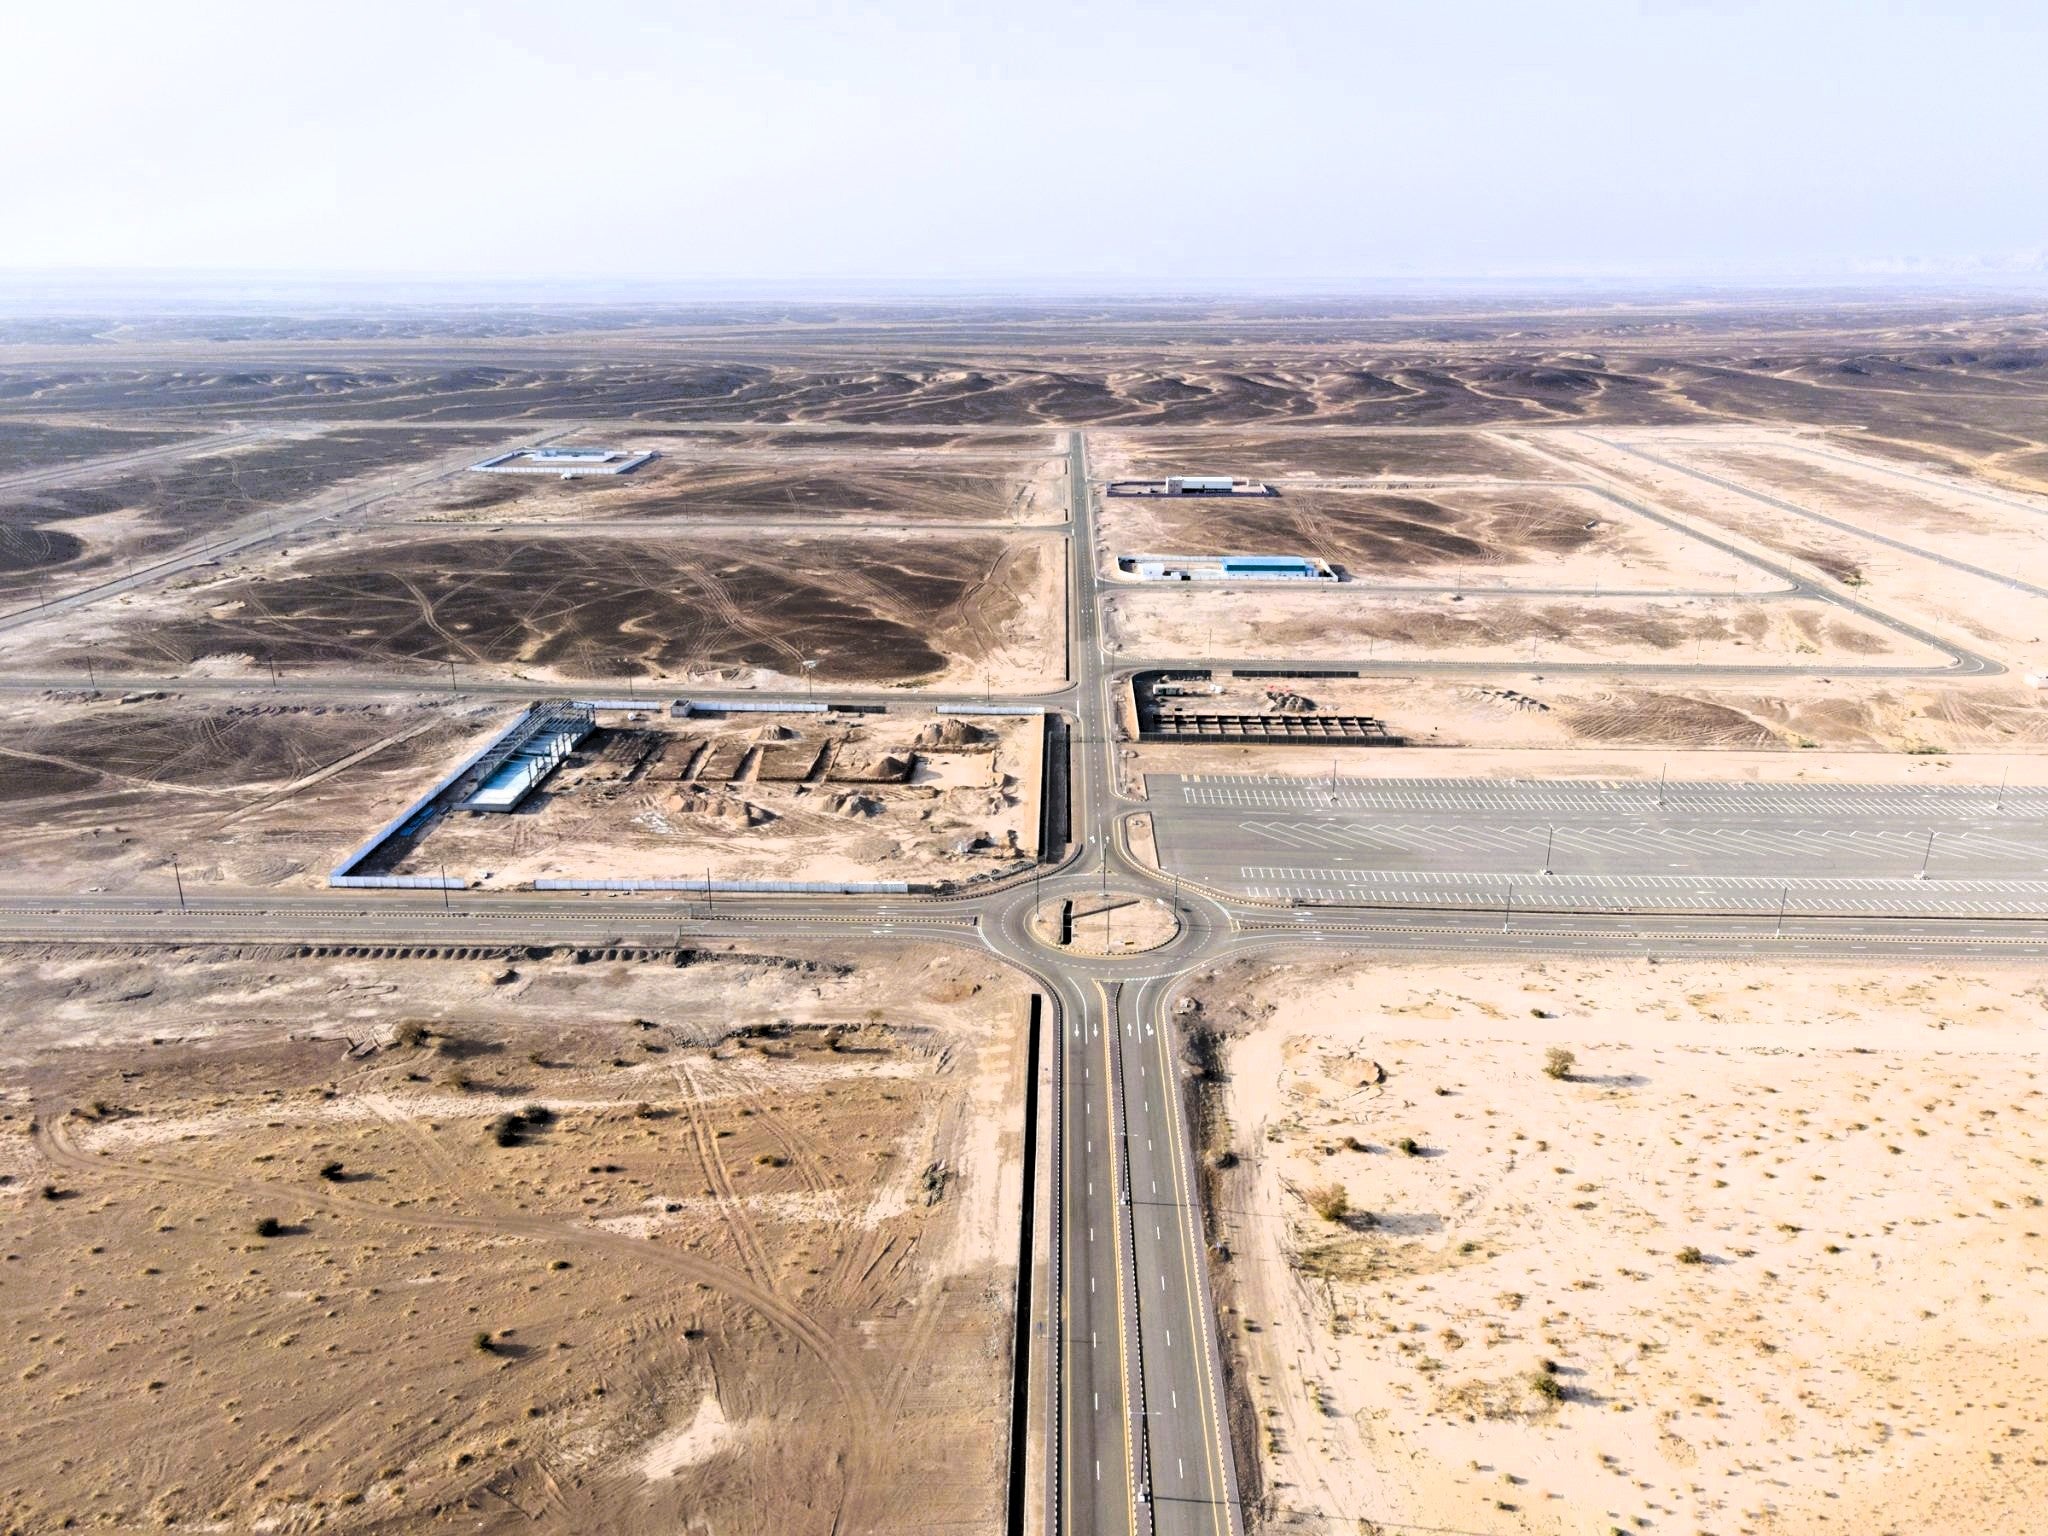
Oman announces $790m industrial investment deals
30 October 2026
Oman’s Public Authority for Special Economic Zones and Free Zones has signed 28 investment agreements worth more than RO304m ($790m) for new projects and expansions across the country’s special economic zones, free zones and industrial cities.
The agreements cover more than 2 million square metres (sq m) of land and span industrial manufacturing, food production, logistics, recycling and commercial activities.
About $383.6m of the investment has been allocated to industrial cities operated by the Public Establishment for Industrial Estates (Madayn). Sohar Free Zone accounted for $152m, followed by the Special Economic Zone at Duqm (Sezad) with $143.1m, Salalah Free Zone with $85.6m and Khazaen Economic City with more than $27m.
The projects are expected to support Oman’s efforts to diversify its economy, expand industrial production and attract private investment in line with Oman Vision 2040.
Investment deals
In Sohar Industrial City, Atlas Steel will invest more than $291.1m in a plant producing iron and steel products on a site of about 440,000 sq m.
Fujian Mancheng Industries & Investment will invest $52m in a ceramics facility covering more than 241,000 sq m. Other investments in Madayn’s industrial cities include an $18.2m phosphate and nitrogen fertiliser plant planned by Gulf Company for Organic and Biological Fertilisers in Raysut, as well as projects involving structural metal products, paper and corrugated cardboard, and oil and gas equipment and services in Raysut, Ibri and Nizwa.
In Sohar Free Zone, Sohar Automotive & Advanced Industries Company will invest $98.8m in an automobile assembly complex covering 317,000 sq m. The complex aims to attract vehicle manufacturers, automotive supply-chain companies and advanced-manufacturing businesses.
Voltamp High Voltage Transformers has announced a $39m investment in a plant that will produce power and electrical-distribution transformers for regional and international markets.
Lalan Middle East will invest a further $3.9m to expand its medical-device manufacturing facility.
ALSO READ: Oman’s Madayn prepares $637m investment drive
In Sezad, Al-Jazir Feed Plant will invest $104m in a shrimp-feed facility to support an integrated shrimp-farming project.
In Salalah Free Zone, Al-Nawras Industries will invest $50m in a steel-structures manufacturing facility, while Integrated Gypsum Company will invest $20m in gypsum-products production. Marai Dhofar will invest $15.6m in the production of Italian cheeses and other dairy products.
Projects in Khazaen Economic City include a plant by Aleemit International Services to manufacture electric-vehicle chargers and components, with an investment of more than $8.8m, and a $6.5m facility by Joger Modular Building Technologies to produce precast-concrete building components.
Additional investments in Khazaen include construction materials, ready-mix concrete, industrial units, logistics facilities and warehouses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21016368/main.jpg -
Sabic swings back to profit in Q3 with $224m net income
30 October 2026
Register for MEED’s 14-day trial access
Saudi Basic Industries Corporation (Sabic) returned to profitability in the third quarter of the year, reporting adjusted net income of SR840m ($224m) as revenue and earnings improved from the previous quarter.
The Saudi chemicals giant had posted an adjusted net loss of $100m in the second quarter.
Revenue increased 14% on a quarter-on-quarter basis to $7.51bn, while adjusted earnings before interest, taxes, depreciation and amortisation (Ebitda) climbed 40% to $1.27bn. Adjusted Ebitda surged 434% to $578.67m.
Sabic’s net debt stood at $808m as of 30 September compared with $728m as of 30 June.
Adjusted earnings per share rose to SR0.28 ($0.07) from a loss of SR0.13 ($0.03).
The recovery occurred despite persistent margin pressure across the global petrochemicals sector and heightened geopolitical risk in the Middle East.
Additionally, Sabic said it achieved $949.33m of its broader portfolio optimisation programme target of $3bn by 2030 in positive recurring Ebitda impact from its transformation efforts.
During the third quarter, Sabic received its Local Content Certificate for 2025 from the Local Content and Government Procurement Authority, recording a score exceeding 61% – an increase of more than nine percentage points over the prior evaluation period. The company attributed the increase to domestic procurement agreements, including a memorandum of understanding with Lenovo.
Capital projects
After several years of subdued project spending, Sabic is beginning to step up investment in new production capacity, with major projects reaching key milestones this year.
In February, affiliate Petrokemya awarded China National Chemical Engineering Group Corporation the main engineering, procurement and construction (EPC) contract for a new ethylene oxide catalyst production facility. The 4,000-tonne-a-year (t/y) unit at Jubail Industrial City includes catalyst carrier washing, drying facilities and associated utilities.
Major ammonia-urea complex
In September, Sabic Agri-Nutrients awarded South Korea’s Samsung E&A a $3.465bn EPC contract for its seventh production complex in Jubail Industrial City (San VII).
The project will have an annual capacity of approximately 1.2 million metric tonnes of conventional ammonia and 2.6 million tonnes of urea, integrated with a post-combustion carbon-capture unit.
The Ministry of Energy approved feedstock allocation for the project in March. San VII will expand the company’s total urea capacity by 54%, from approximately 4.8 million t/y to 7.4 million t/y.
The development reflects a shift in project scope. Originally conceived as San VI – a low-carbon facility designed to yield 1.2 million t/y of blue ammonia alongside specialised nutrients – the scheme was re-engineered as a conventional ammonia and urea plant using carbon-capture systems to manage emissions intensity.
Construction is scheduled to begin in the fourth quarter of 2026. Commissioning is slated for the third quarter of 2030, with full commercial operation targeted before year-end 2030.
Sabic Agri-Nutrients positions the project as central to its 2040 strategy to expand export market share and support international supply chains.
Greenfield methanol plant
San VII is not the only major project moving forward.
Also in September, Sabic subsidiary Saudi Methanol Company (Ar-Razi) secured feedstock approval from the Ministry of Energy to build a 1.8 million t/y greenfield methanol plant in Jubail.
The project aligns with Sabic’s focus on scale in core petrochemical chains and provides intermediate feedstock for expanding domestic downstream manufacturing.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21015944/main2510.jpg