Kuwait enjoys sustained non-oil growth
25 August 2023
 This month’s special report on Kuwait also includes:
> POLITICS: Stakeholders hope Kuwait can execute spending plans
> ENERGY: Kuwait’s $300bn energy target is a big test
> POWER & WATER: Warming erodes Kuwait’s power and water reserves
> BANKING: Kuwaiti banks enter bounce-back mode
> INTERVIEW: Kuwait’s Gulf Centre United sets course for expansion

After witnessing a substantial upswing in its economy in 2022, with real GDP growth surging to 8.2 per cent, according to the IMF, Kuwait’s growth has nominally slowed to 0.1 per cent in 2023. However, this plummet on paper is more a function of the country’s pullback in oil production than any dramatic swing in its economic fate.
Amid the surprise production cuts by the Opec+ producers in April 2023, Kuwait announced a cut of 128,000 barrels a day (b/d), equivalent to about 10 per cent of the group’s 1.15 million b/d in total cuts and around 5 per cent of Kuwait’s output.
In May and June, Kuwait pumped 2.55 million b/d of crude oil, down from 2.65 million b/d in April. For 2024, the country’s quota is 2.676 million b/d.
This curbing of the country’s primary export has naturally had a significant impact on headline growth, but looking ahead to 2024, the growth rate is projected to recover to 2.7 per cent.
Non-oil sustenance
Behind the fluctuations in Kuwait’s headline real GDP growth due to oil production and prices, the country continues to enjoy strong domestic demand and robust non-oil growth, with 4 per cent non-oil GDP growth in 2022 and a projection of 3.8 per cent growth in 2023, according to the IMF.
The World Bank, meanwhile, expects Kuwait’s non-oil economy to grow by 4.4 per cent in 2023.
Kuwait’s fiscal surplus stood at an estimated 7 per cent of GDP in the 2022/23 fiscal year, although that surplus is expected to disappear in 2023/24 after the Kuwait government approved an expansionary budget with a spending allocation of KD26.3bn ($85.5bn) for the current fiscal period – more than 12 per cent larger than the KD23.5bn spending budget for 2022/23.
If ultimately spent, the significantly higher allocated expenditure should further stimulate the non-oil economy.
The budget, approved on 2 August before the parliamentary summer recess, anticipates a fiscal deficit of KD6.8bn. This follows Kuwait achieving its first budget surplus in nine years in 2022/23. The current budget is based on an assumed average oil price of $70 a barrel, with an estimated government revenue of KD19.5bn, including KD17.2bn from oil revenue.
Kuwaiti business leaders are cautiously optimistic that this 2023 government could be the one to break the political gridlock
Oil price uncertainty
Looking ahead, oil price volatility remains the key threat to the oil-dependent Kuwaiti economy. Despite this, 2023/24 is conservatively budgeted in terms of its oil price assumptions, broadly aligning with the IMF assumptions for a $73.1 average in 2023, and $68.9 in 2024, and comparing with a July 2023 spot price around the $80-mark.
The hope will be that the price will remain at a higher mark and that the budgeted oil price turns out to be overly precautionary.
However, China’s economy showed signs of slipping again in July, with both imports and exports falling – a worrying sign for global trade and commodity prices. In mid-August, the International Energy Agency lowered its 2024 oil demand growth forecast to 1 million b/d in 2024, down 150,000 b/d from its prior forecast, pointing to a combination of high interest rates, tight credit, and sluggish manufacturing and trade.
The uncertainty of such scenarios should lend haste to the fiscal and structural reforms waiting in the wings. The hope is that Kuwait’s newly minted parliament and cabinet could mean that a resolution to the political gridlock is in sight, offering a path to the fiscal and structural reforms the country requires.
Kuwaiti business leaders are cautiously optimistic that this 2023 government could be the one to break the political gridlock between the government and parliament and reset the loop of successive resignations, reappointments and elections that have recently prevented any reform progress.
Reform requirements
Fiscal measures identified by the IMF as priorities include the need to rationalise Kuwait’s public sector wage bill and phase out energy subsidies, alongside introducing the long-delayed value-added tax and expanding the country’s corporate income tax base.
Advocated structural reforms include labour market reforms, competition strengthening, and climate change adaptation and mitigation.
Enacting at least some of these reforms will be crucial to Kuwait’s fiscal and economic viability in the medium to long term, with each delay only making tackling items such as the public sector wage bill harder.
In the short term, Kuwait can, of course, keep pumping. In June, Kuwait Oil Company CEO Ahmed Jaber al-Aydan told the Kuwait Times that the country’s oil production capacity would reach 3 million b/d by 2025. He also said the oil company would spend KD13bn ($42.5bn) on oil projects over the next five years.
The Kuwait government, meanwhile, announced in July that it planned to boost its crude oil production capacity to 3.15 million b/d within four years.
Yet at some point, Kuwait will still need to take a long, hard look at its future finances. All hopes are presently set on the 2023 government being the one to start moving in the right direction.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
-
 Contractors submit bids for Libya refinery
5 October 2026
-
 Dubai tenders sewage and stormwater projects
5 October 2026
-
 QatarEnergy gives North Field West topside bidders more time
2 October 2026
-
 Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
Saudi Arabia's Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion has reached financial close.
In a disclosure to the Saudi Exchange, Acwa said it had secured SR9.69bn ($2.58bn) in long-term financing for the project, which has a generation capacity of 2,313.5MW.
In April, MEED reported that Acwa and Saudi Energy (formerly Saudi Electricity Company) had signed a 31-year power purchase agreement (PPA) with Saudi Arabia’s principal buyer, Saudi Power Procurement Company (SPPC), for the project.
The project involves the development of a combined-cycle gas turbine (CCGT) plant in the Mecca region. It is being developed by Al-Morjan Two Electricity Company, with Acwa and Saudi Energy each owning a 40% stake in the project.
The contract is valued at SR11.5bn ($3.07bn), the companies said in separate stock exchange filings at the time. The carbon-capture-ready power plant will be implemented under a build, own and operate contract.
The financing has a tenor of about 34 years and was provided by a consortium of local, regional and international lenders.
The lenders are:
- Abu Dhabi Commercial Bank
- Alinma Bank
- Boubyan Bank
- China Minsheng Banking Corporation, Hong Kong Branch
- Commercial Bank of Dubai
- HSBC Bank Middle East
- Industrial and Commercial Bank of China
- Industrial Bank, Beijing Branch
- National Bank of Greece, Cyprus
- Riyad Bank
- Saudi Awwal Bank
- Saudi National Bank
- Standard Chartered Bank, Taiwan
- Sumitomo Mitsui Trust Bank, London Branch
The project scope also includes financing and expansion of a 380kV electrical substation.
According to regional project tracker MEED Projects, construction works have commenced on the project and a joint venture of Egypt's Elsewedy Electric and China's Sinohydro has been working as the main contractor.
Rabigh 1 extension
In January, Saudi Energy announced a spearate energy conversion agreement with SPPC for the purchase of electricity from the Rabigh 1 power plant expansion.
The contract is valued at SR5.33bn ($1.42bn).
It covers the development, financing, construction, ownership and operation of the gas-fired power plant, which will have a generation capacity of 1,179MW.
A joint venture of Elsewedy Electric and Germany’s Siemens Energy is undertaking the engineering, procurement and construction work for the project, which is expected to be completed by the end of 2026.
US/India-based Synergy Consulting is the financial advisory consultant to Saudi Energy on this project.
Acwa also recently started initial commercial operations at the Taiba 1 and Qassim 1 combined-cycle gas turbine (CCGT) power plants, as reported by MEED.
The plants have a combined generation capacity of about 3.8GW and are two of four projects procured under the first round of Saudi Arabia’s gas-fired independent power producer (IPP) programme by Saudi Power Procurement Company.
A team of Saudi Energy, formerly Saudi Electricity Company, and Acwa won the contract to develop and operate the projects in 2023.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20270643/main.jpg -
Contractors submit bids for Libya refinery
5 October 2026
Bids have been submitted for the main contract for Libya’s planned South Refinery project and are currently under technical evaluation, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year, and the main contract is anticipated to be worth more than $600m.
The main contract is expected to use the engineering, procurement and construction (EPC) model.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20267178/main.jpg -
Dubai tenders sewage and stormwater projects
5 October 2026
Dubai Municipality has issued tenders for a 3,000-cubic-metre-a-day (cm/d) sewage treatment plant (STP) and a strategic stormwater drainage system.
The first tender is for the design and construction of the Al-Lissaily STP.
The project, identified as DS311/1, covers the design, supply, installation, construction and commissioning of the plant in the Al-Lissaily area.
Dubai Municipality’s Sewerage and Recycled Water Projects Department is issuing the tender. The bid submission deadline is 29 October.
The facility is located near residential communities and farming areas. The project will therefore include measures for odour control, treated effluent quality, noise mitigation and environmental performance.
The municipality said the plant will incorporate landscaping and architectural features designed to reflect Dubai’s heritage character and the surrounding farming environment.
The second tender is for project TF-07-C1, a strategic stormwater drainage system covering more than 100 million square metres.
The project area extends from Sheikh Mohammed Bin Zayed Road (E311) to the north to Emirates Road (E611) to the south, and from Expo Road in the west to Dubailand in the east.
The project will provide stormwater infrastructure and service connections for more than 20 private developers, as well as the Al-Yalayis 5 community.
It will also support major roads in the Jebel Ali area, including Sheikh Mohammed Bin Zayed Road, Emirates Road, Sheikh Zayed Road, Sheikh Zayed Bin Hamdan Al-Nahyan Road, Hessa Street, Al-Yalayis Road and Al-Fay Road.
The scope includes a major stormwater gravity drainage system, with pipeline diameters of up to 3,000mm.
Dubai Municipality said the project is intended to increase drainage capacity, improve relief for existing and new stormwater systems, and strengthen protection against extreme rainfall events.
The bid submission deadline is 22 October.
The municipality also recently invited contractors to bid for a contract to upgrade and rehabilitate the stormwater system in Abu Hail.
The project comprises a stormwater pumping station with a total discharge capacity of 26 cubic metres a second. It is estimated to cost up to $163m.
Bid submissions are due by 15 October.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20266881/main.jpg -
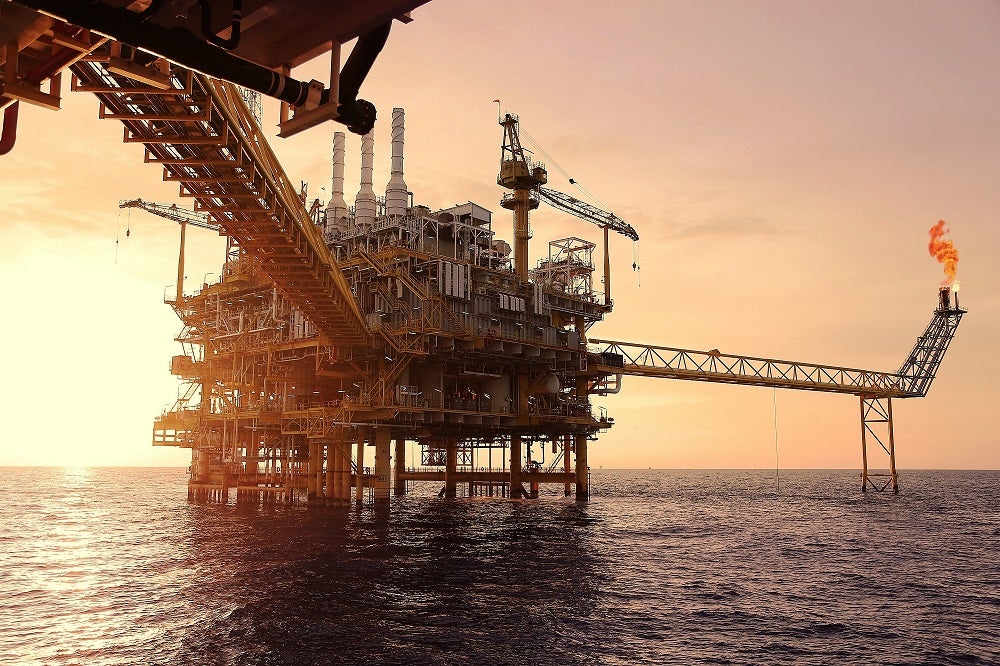
QatarEnergy gives North Field West topside bidders more time
2 October 2026
QatarEnergy has granted contractors more time to prepare bids for a tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors now have until 12 October to submit technical bids for the project, according to sources. Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The PDMs will increase gas production from North Field reservoirs and provide additional gas feedstock for the NFW liquefied natural gas (LNG) development.
The tender, issued earlier this year, forms part of the wider NFW project, the third and final phase of the state enterprise’s North Field LNG expansion programme.
The previous deadlines for technical bids were 30 August, 15 September and 28 September, while commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott a contract for the EPCI of four offshore jackets that will also support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208200/main.jpg -
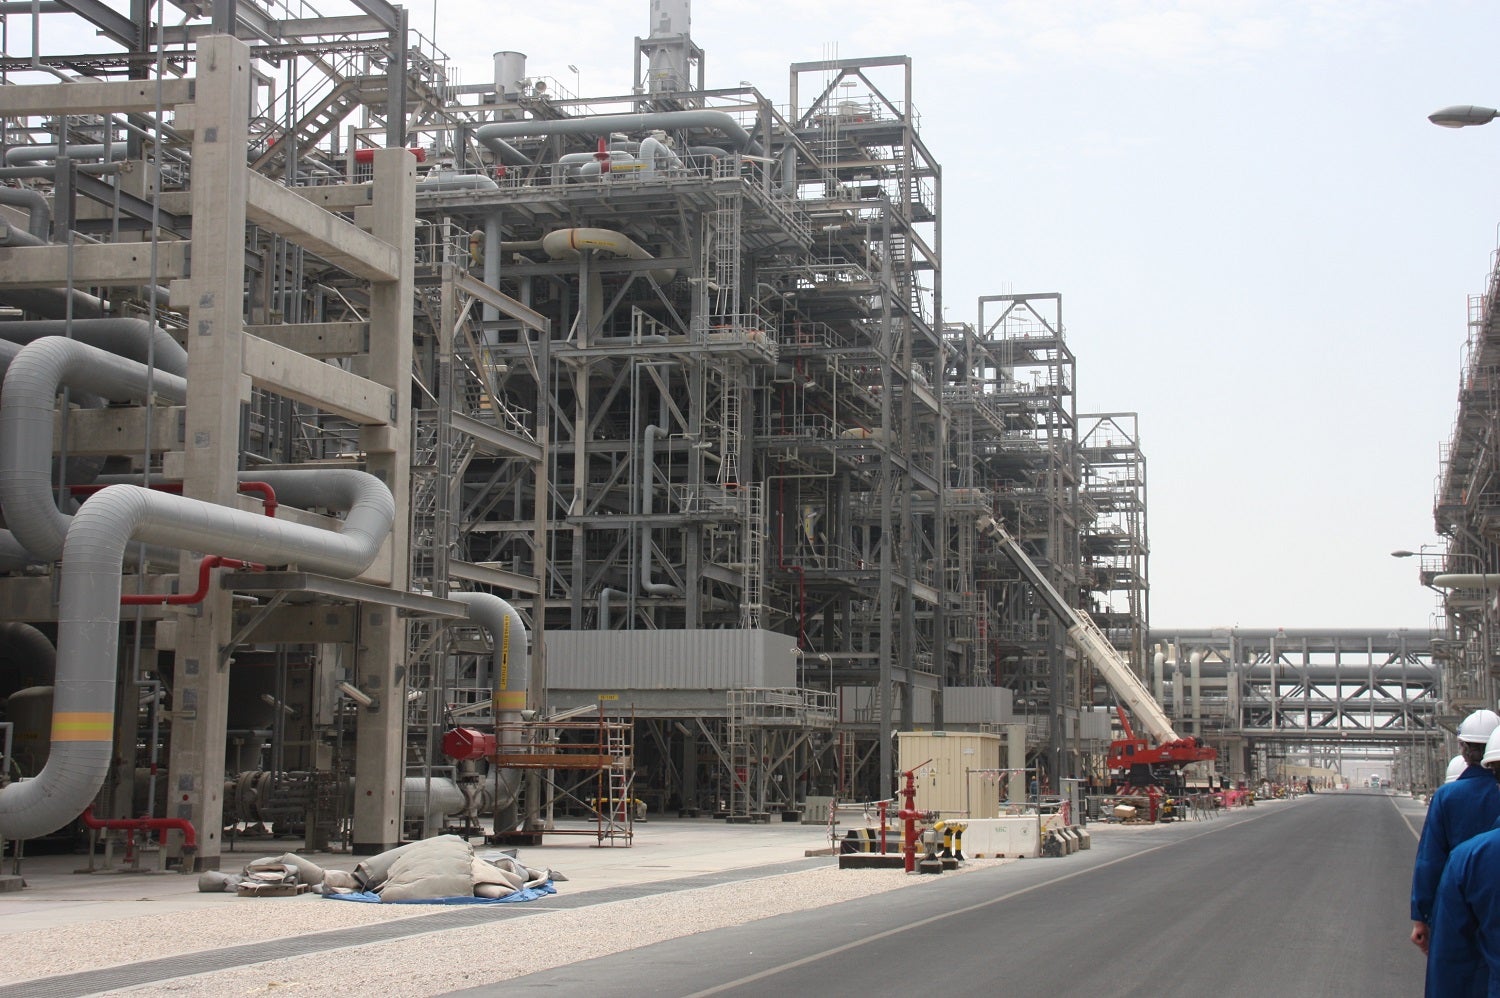
Egypt implements oil and gas storage projects worth $1.1bn
2 October 2026
Egypt is implementing oil and gas storage projects worth a total of £E54bn ($1.1bn), according to a statement released by the country’s cabinet.
Active developments include expanding El-Hamra Petroleum Port in El-Alamein on the Mediterranean coast, as well as building a jet-fuel storage and transport hub at the Badr depot in Cairo.
Other projects include constructing new storage tanks at refinery complexes in Amreya, Alexandria; Assiut; and Cairo.
Over the past 12 years, Egypt has built 84 petroleum storage facilities with a total capacity of 5.2 million tonnes, the cabinet statement said.
Egypt has invested £E42.7bn ($880m) in developing these facilities, with the aim of bolstering domestic energy security.
Completed infrastructure projects include facilities in Sohag (Upper Egypt) and Alexandria.
They also include offshore terminal and storage facilities, a liquid bulk station in Ain Sokhna, and strategic crude oil storage tanks across the country.
Storage facilities have become a strategic priority for Egypt since the US and Israel attacked Iran on 28 February, triggering a regional war that has disrupted shipping through the Strait of Hormuz.
The disruption has made imports of hydrocarbon products into Egypt less predictable, increasing the importance of strategic stockpiles.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208195/main.jpg