IMF downgrades Mena growth forecast
1 February 2024
The Washington-based IMF has revised down the expected real GDP growth figure for the Middle East and North Africa region for 2024 to 2.9%, down from the previous projection of 3.4% in its October economic outlook.
The downgraded growth forecast reflects, among other things, the deepening of the voluntary oil production cuts as part of a further Opec+ agreement in November, as well as the heightened instability in the region as a result of the war in Gaza and the Red Sea crisis.
The most recent agreement among the Opec+ members saw half a dozen countries agree to additional voluntary production cuts through to the end of Q1 2024 – in addition to the voluntary cuts announced in April 2023 and extended until the end of 2024.
The regional oil producers that agreed to these additional cuts were Saudi Arabia, Iraq, the UAE, Kuwait, Algeria and Oman, with the six countries collectively accounting for a 1.6 million barrel a day reduction in oil output, led by Riyadh, which alone cut 1 million b/d.
In the same update, the IMF revised down Saudi Arabia’s real GDP growth forecast for 2024 to 2.7%, down from a previous projection of 4.0% in its October economic outlook.
A week ago, the fund’s concluding statement to its Article IV consultation with Oman also saw it lower the growth forecast for that country to 1.4%, down from a previous forecast of 2.7% growth.
Both revisions reflect the country-level economic impact of these additional voluntary cuts, which will have an even greater impact on the fiscal side, cutting into government revenues and possibly spending.
Geopolitical impacts
The other major influence on the regional economy in the past three months has been the eruption of the war in Gaza and the Red Sea shipping crisis.
These twin events have had considerable impact on the most adjacent geographies, with the war in Gaza affecting economies across the Levant, as well as regional tourism, and the Red Sea crisis hitting trade.
In mid-December, a study commissioned by the UN Development Programme (UNDP) estimated that the economic cost of the war in Gaza on neighbouring Egypt, Jordan and Lebanon was set to exceed $10bn in 2023 alone and had the potential to push 230,000 more people into poverty.
It noted that the conflict was impacting consumption and trade and exacerbating the existing weak growth, high unemployment and fiscal pressure in the three countries.
Egypt has been acutely affected by both the impact on tourism and the fall in receipts from the passage of ships transiting through the Suez Canal – both major sources of revenue for the Egyptian government.
On 26 January, the UN Conference on Trade and Development (UNCTAD) estimated that weekly transits through the Suez Canal had fallen by 42% over the past two months, and that container ship transits specifically had plummeted by 67% as compared to one year previously.
However, the largest impact has been on liquefied natural gas (LNG) carriers, which have stopped altogether since 16 January, according to Jan Hoffmann, trade logistics chief at UNCTAD.
Cross-sector impacts
Tourism has also been severely impacted since the commencement of hostilities in October, with the significant tourism markets of Egypt and Jordan being subject to mass flight and hotel cancellations. For Lebanon, the regional economic crisis has merely compounded the already dire domestic economy crisis.
In the IMF’s January briefing, research department division chief Daniel Leigh noted that for Egypt, “despite strong tourism performance overall in 2023, there’s been a slowdown since the start of the conflict in Gaza, in Israel, with hotel bookings clearly coming down.
“Now, on top of that, there’s the escalation and the Red Sea attacks, which may impact, and are impacting, foreign exchange inflows. That’s about $700m a month, a very important source of foreign currency for Egypt.”
Leigh said the uncertainty of the situation was already impacting investment prospects, creating an even more urgent need for additional financing to enable reforms and bring inflation down to restore growth.
The IMF is currently in discussions with Cairo over the provision of additional financing to the Egyptian government in the form of an Extended Fund Facility (EFF) from the fund alongside a reform programme.
More broadly, the IMF has assessed that the shockwaves from the war in Gaza have already caused current accounts across the region to deteriorate and given rise to $30bn in additional financing needs among Arab states outside of the Gulf, with further fallout expected if the conflict drags on.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Ashghal tenders Mekeines-Umm Bab link road
30 October 2026
-
-
 Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
-
 Oman announces $790m industrial investment deals
30 October 2026
-
 Sabic swings back to profit in Q3 with $224m net income
30 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Ashghal tenders Mekeines-Umm Bab link road
30 October 2026

Qatar’s Public Works Authority (Ashghal) has tendered a contract for the design and construction of the Mekeines to Umm Bab Link Road and associated infrastructure.
The tender was issued on 29 October, with a bid submission deadline of 22 December.
The scope comprises:
- Highway works, including main carriageways, access roads, grade-separated ramps, junctions and tie-ins to existing networks
- Dedicated non-motorised user facilities, footpaths and shared-use cycle paths
- Structural installations, including camel underpasses, a QatarEnergy culvert and gateway monumentation
- Extensive dry and wet utilities, encompassing Kahramaa potable water and electrical transmission networks, surface water drainage, street lighting and dedicated communication networks for Ooredoo, the Qatar National Broadband Network and the Qatar Armed Forces
Under the scope of work, the appointed contractor will execute full design verification and turnkey construction under Ashghal’s standard Building and Engineering Design and Build General Conditions of Contract (2018 Edition) on a lump-sum basis. Engineering subconsultants must hold Grade 1 or International classification with the Ministry of Municipality across civil, architectural, mechanical and electrical engineering disciplines.
The contract stipulates an execution period of 1,260 calendar days (3.5 years) from the commencement date, followed by a 400-day maintenance liability period.
The project is open to local and international contractors classified as Grade A in roads specialisation by Qatar’s Ministry of Finance (MoF).
Foreign firms may participate independently or within a joint venture, provided the joint venture leader holds the requisite classification, by registering through the MoF e-procurement portal with attested equivalent certification from their home countries.
The planned corridor is located within Al-Rayyan Municipality across Zones 82 to 84 in the Al-Sheehaniya area.
At its eastern end, the link road begins about 40 kilometres southwest of central Doha, tying into the Salwa Road Interchange 42. At the western terminus, it connects to the roundabout adjacent to Umm Bab on the Abu Samra to Dukhan road (Route 39).
The link road serves as a critical logistics corridor connecting western settlements, residential districts and industrial installations, including concession areas operated by QatarEnergy.
The western 7.5km of the alignment passes directly through the QatarEnergy District, where the corridor runs parallel to active oil and gas pipelines and includes a designated gateway monument.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21041383/main.gif -
Contractors prepare bids for Petro Rabigh bottom-of-the-barrel project
30 October 2026
Contractors are preparing proposals for Saudi Arabia’s Rabigh Refining & Petrochemical Company (Petro Rabigh) for a major project to increase output and improve the efficiency of its integrated refining and petrochemicals complex in Rabigh, on the kingdom’s Red Sea coast.
Petro Rabigh’s downstream complex, which is majority-owned by Saudi Aramco, includes a topping refinery with a 340,000-barrel-a-day (b/d) crude-distillation unit, a 47,000 b/d hydrotreater, a 12 million-cubic-feet-a-day hydrogen plant, a 75,000 b/d naphtha Merox unit and a 60,000 b/d kerosene Merox unit. The complex also includes supporting utilities, product tankage and a marine terminal.
The main objective of the bottom-of-the-barrel project is to convert low-value, high-sulphur fuel oil and heavy-residue streams – which account for about 20% to 22% of refinery output – into higher-value, cleaner products, including diesel and lighter distillates.
Petro Rabigh aims to achieve residue-conversion capacity of about 64,000 to 75,000 b/d by adding integrated fuel-oil upgrading and diesel-treatment units.
The company issued the main tender for engineering, procurement and construction (EPC) works earlier this year. Contractors have until 19 November to submit proposals, sources told MEED.
The following companies are understood to be among those bidding for the project:
- CTCI Corporation (Taiwan)
- JGC Corporation (Japan)
- Larsen & Toubro (India) / Technip Energies (France)
- Tecnicas Reunidas (Spain)
The overall scope of work on the project covers the construction of the following units:
- A light-naphtha isomerisation unit
- A deasphalting and dewaxing unit
- An ebullated-bed processing unit
- A sulphur block, comprising sulphur-recovery, acid-gas-removal, sour-water-stripping and sulphur-forming units
- Sales-gas allocation facilities and associated pipeline works
- Utilities outside battery limits
- Auxiliary piping modifications
- Utility and hydrocarbon tie-ins
Petro Rabigh appointed Australia-headquartered Worley last year to carry out front-end engineering and design (feed) work for the bottom-of-the-barrel project.
MEED also reported that Petro Rabigh appointed Worley to provide engineering and project-management consultancy (PMC) services for the project in the first quarter of this year.
Under the contract, Worley will carry out engineering studies and PMC functions. It will also support the development of cost estimates, project-specific execution procedures and technical procedures in line with Saudi Aramco guidelines. The work covers both the design-basis scoping-paper stage and the subsequent feed stage.
Petro Rabigh will draw on Worley’s expertise in design, procurement and processing technologies, including light-naphtha isomerisation; vacuum-residue processing through deasphalting and dewaxing; an ebullated-bed configuration integrated with the diesel-hydrotreating section; and unconverted-oil hydrotreatment.
Worley recently confirmed its contract award from Petro Rabigh, saying it will deliver engineering, project management, procurement support and related consultancy services for projects across its client’s portfolio.
The scope includes developing design-basis documents, conducting technical evaluations, preparing cost estimates, supporting feed tender packages and providing detailed engineering and execution-phase support as projects advance through development and delivery.
The services will support the evaluation and development of potential new facilities and infrastructure across the complex, including process units, utilities, sulphur recovery facilities and associated infrastructure.
“The work will help Petro Rabigh advance future projects aimed at enhancing the long-term value and performance of its refining and petrochemicals operations,” Worley said in a statement on 28 October.
Separately, Petro Rabigh awarded US-based KBR a 10-year maintenance contract in February to support its polymer plants in Rabigh.
KBR’s Technology Led Industrial Solutions business line will execute the operations and maintenance contract, sources told MEED. The business operates within the Houston-headquartered company’s Technology Solutions portfolio.
In March 2024, Petro Rabigh also awarded KBR a similar five-year asset-condition-monitoring contract. Under that programme, KBR is providing predictive-maintenance services at Petro Rabigh’s main plant.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21032785/main.jpg -
Contractors submit Riyadh Expo KSA pavilion bids
30 October 2026
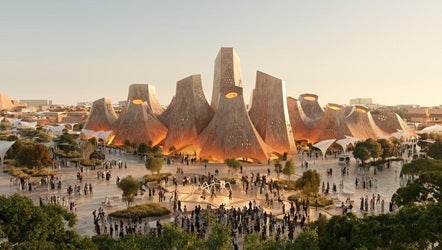
Contractors submitted bids on 25 October for a contract to design and build the Saudi Arabia pavilion at the Expo 2030 Riyadh site.
The facility will include exhibition halls, VIP and protocol areas, event and performance spaces, meeting rooms, food and retail outlets, and back-of-house facilities.
The pavilion will host exhibitions, cultural and commercial showcases and official events throughout the six-month expo.
External public realm works are also included.
Expo 2030 Riyadh Company (ERC), tasked with delivering the Expo 2030 Riyadh venue, issued the main tender on 19 May, as MEED exclusively reported.
Earlier this week, ERC appointed UK-based Mace as procurement advisory consultant for Expo 2030 Riyadh, supporting procurement activities across the programme.
Under the appointment, Mace will provide procurement services and advise on the management and delivery of procurement activities, with the aim of supporting the expo’s wider programme objectives.
Expo 2030 Riyadh will run from October 2030 to March 2031 with the theme Foresight for Tomorrow, with host authorities projecting approximately 42 million visits.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event.
Situated north of the Saudi capital, the site is located near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched Expo 2030 Riyadh Company – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21031590/main.jpg -
Oman announces $790m industrial investment deals
30 October 2026
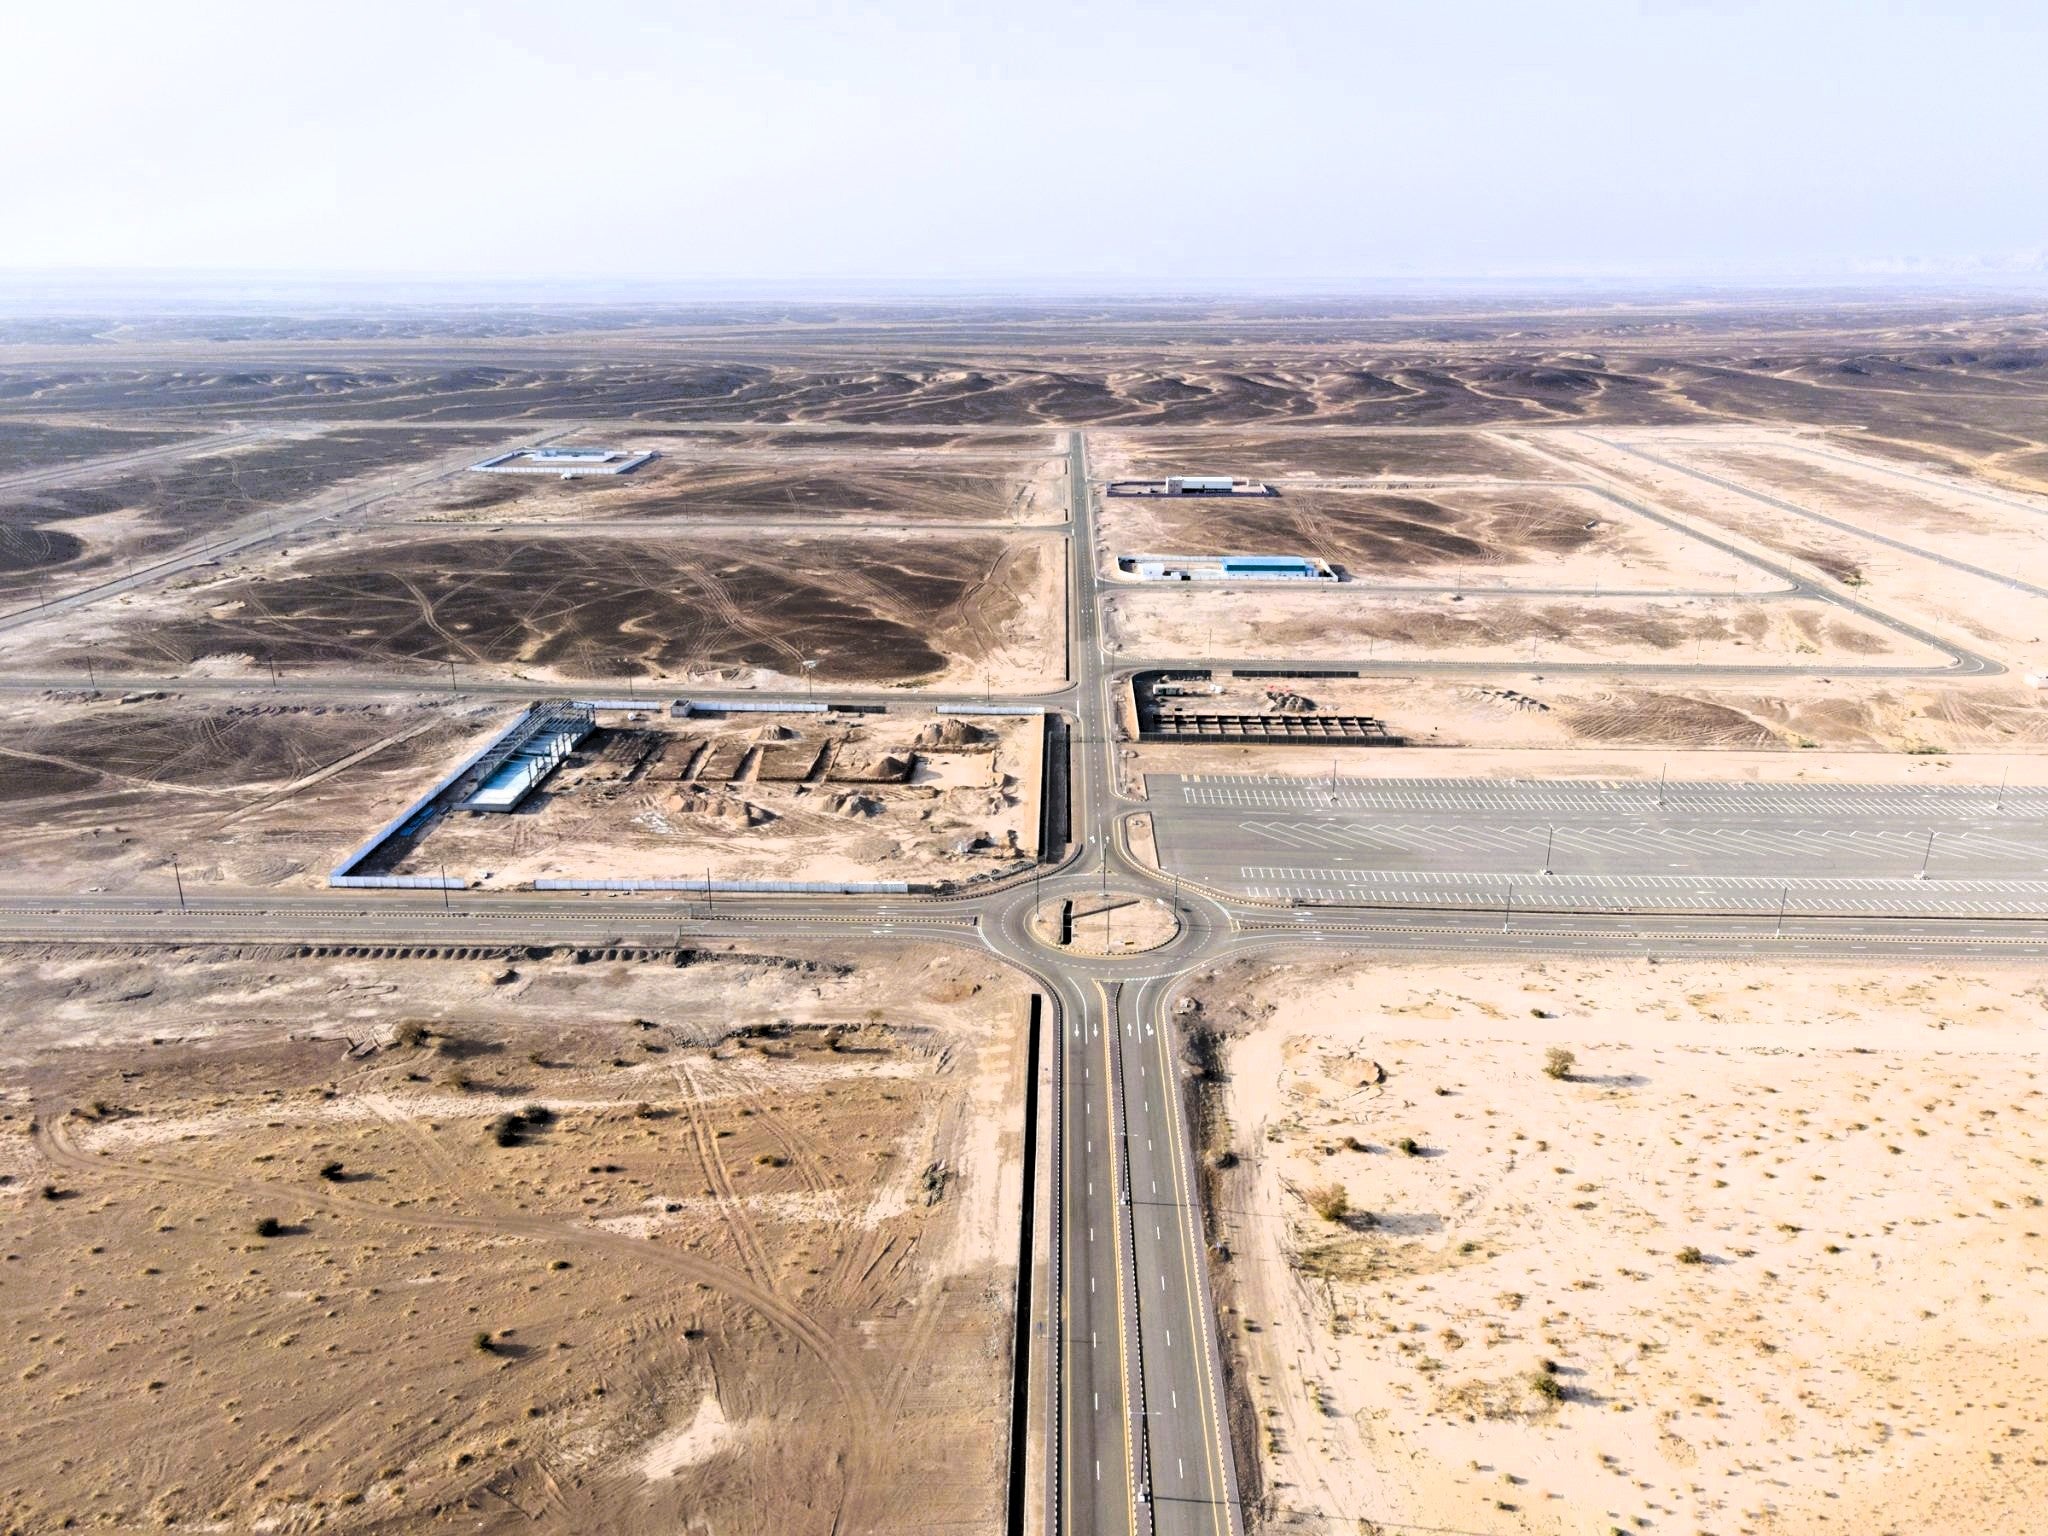
Oman’s Public Authority for Special Economic Zones and Free Zones has signed 28 investment agreements worth more than RO304m ($790m) for new projects and expansions across the country’s special economic zones, free zones and industrial cities.
The agreements cover more than 2 million square metres (sq m) of land and span industrial manufacturing, food production, logistics, recycling and commercial activities.
About $383.6m of the investment has been allocated to industrial cities operated by the Public Establishment for Industrial Estates (Madayn). Sohar Free Zone accounted for $152m, followed by the Special Economic Zone at Duqm (Sezad) with $143.1m, Salalah Free Zone with $85.6m and Khazaen Economic City with more than $27m.
The projects are expected to support Oman’s efforts to diversify its economy, expand industrial production and attract private investment in line with Oman Vision 2040.
Investment deals
In Sohar Industrial City, Atlas Steel will invest more than $291.1m in a plant producing iron and steel products on a site of about 440,000 sq m.
Fujian Mancheng Industries & Investment will invest $52m in a ceramics facility covering more than 241,000 sq m. Other investments in Madayn’s industrial cities include an $18.2m phosphate and nitrogen fertiliser plant planned by Gulf Company for Organic and Biological Fertilisers in Raysut, as well as projects involving structural metal products, paper and corrugated cardboard, and oil and gas equipment and services in Raysut, Ibri and Nizwa.
In Sohar Free Zone, Sohar Automotive & Advanced Industries Company will invest $98.8m in an automobile assembly complex covering 317,000 sq m. The complex aims to attract vehicle manufacturers, automotive supply-chain companies and advanced-manufacturing businesses.
Voltamp High Voltage Transformers has announced a $39m investment in a plant that will produce power and electrical-distribution transformers for regional and international markets.
Lalan Middle East will invest a further $3.9m to expand its medical-device manufacturing facility.
ALSO READ: Oman’s Madayn prepares $637m investment drive
In Sezad, Al-Jazir Feed Plant will invest $104m in a shrimp-feed facility to support an integrated shrimp-farming project.
In Salalah Free Zone, Al-Nawras Industries will invest $50m in a steel-structures manufacturing facility, while Integrated Gypsum Company will invest $20m in gypsum-products production. Marai Dhofar will invest $15.6m in the production of Italian cheeses and other dairy products.
Projects in Khazaen Economic City include a plant by Aleemit International Services to manufacture electric-vehicle chargers and components, with an investment of more than $8.8m, and a $6.5m facility by Joger Modular Building Technologies to produce precast-concrete building components.
Additional investments in Khazaen include construction materials, ready-mix concrete, industrial units, logistics facilities and warehouses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21016368/main.jpg -
Sabic swings back to profit in Q3 with $224m net income
30 October 2026
Register for MEED’s 14-day trial access
Saudi Basic Industries Corporation (Sabic) returned to profitability in the third quarter of the year, reporting adjusted net income of SR840m ($224m) as revenue and earnings improved from the previous quarter.
The Saudi chemicals giant had posted an adjusted net loss of $100m in the second quarter.
Revenue increased 14% on a quarter-on-quarter basis to $7.51bn, while adjusted earnings before interest, taxes, depreciation and amortisation (Ebitda) climbed 40% to $1.27bn. Adjusted Ebitda surged 434% to $578.67m.
Sabic’s net debt stood at $808m as of 30 September compared with $728m as of 30 June.
Adjusted earnings per share rose to SR0.28 ($0.07) from a loss of SR0.13 ($0.03).
The recovery occurred despite persistent margin pressure across the global petrochemicals sector and heightened geopolitical risk in the Middle East.
Additionally, Sabic said it achieved $949.33m of its broader portfolio optimisation programme target of $3bn by 2030 in positive recurring Ebitda impact from its transformation efforts.
During the third quarter, Sabic received its Local Content Certificate for 2025 from the Local Content and Government Procurement Authority, recording a score exceeding 61% – an increase of more than nine percentage points over the prior evaluation period. The company attributed the increase to domestic procurement agreements, including a memorandum of understanding with Lenovo.
Capital projects
After several years of subdued project spending, Sabic is beginning to step up investment in new production capacity, with major projects reaching key milestones this year.
In February, affiliate Petrokemya awarded China National Chemical Engineering Group Corporation the main engineering, procurement and construction (EPC) contract for a new ethylene oxide catalyst production facility. The 4,000-tonne-a-year (t/y) unit at Jubail Industrial City includes catalyst carrier washing, drying facilities and associated utilities.
Major ammonia-urea complex
In September, Sabic Agri-Nutrients awarded South Korea’s Samsung E&A a $3.465bn EPC contract for its seventh production complex in Jubail Industrial City (San VII).
The project will have an annual capacity of approximately 1.2 million metric tonnes of conventional ammonia and 2.6 million tonnes of urea, integrated with a post-combustion carbon-capture unit.
The Ministry of Energy approved feedstock allocation for the project in March. San VII will expand the company’s total urea capacity by 54%, from approximately 4.8 million t/y to 7.4 million t/y.
The development reflects a shift in project scope. Originally conceived as San VI – a low-carbon facility designed to yield 1.2 million t/y of blue ammonia alongside specialised nutrients – the scheme was re-engineered as a conventional ammonia and urea plant using carbon-capture systems to manage emissions intensity.
Construction is scheduled to begin in the fourth quarter of 2026. Commissioning is slated for the third quarter of 2030, with full commercial operation targeted before year-end 2030.
Sabic Agri-Nutrients positions the project as central to its 2040 strategy to expand export market share and support international supply chains.
Greenfield methanol plant
San VII is not the only major project moving forward.
Also in September, Sabic subsidiary Saudi Methanol Company (Ar-Razi) secured feedstock approval from the Ministry of Energy to build a 1.8 million t/y greenfield methanol plant in Jubail.
The project aligns with Sabic’s focus on scale in core petrochemical chains and provides intermediate feedstock for expanding domestic downstream manufacturing.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21015944/main2510.jpg