
GCC shelters from the trade wars
18 April 2025

The ‘Liberation Day’ tariffs that US President Donald Trump announced on 2 April have plunged global markets into turmoil, with many previously bullish investors turning bearish as a large swathe of reciprocal tariffs were announced.
A week later, Trump announced a 90-day pause on the new tariff regime for most trading partners except China, which received an increased tariff rate of 145%, which was then increased to 245%.
As global stock markets suffered some of their worst days on record, for the GCC, the main mechanism of transmission of economic pain came through the negative oil price shock. Brent crude prices dropped by about 16% and dipped below $60 a barrel for the first time since 2021.
Falling prices
For TS Lombard’s general base case, the negative impact of weaker oil demand is offset by more constructive aspects, which highlight the region’s resilience as it is relatively sheltered from the direct effects of Trump’s tariffs compared to most other emerging markets.
To focus on the negatives first, oil prices have taken a significant hit, dropping to lows unseen since before the Russia-Ukraine war.

It has been generally accepted that during the period from 2022 to February 2025, there was a $70 a barrel price floor for oil, supported by reduced Opec+ production in 2023 and 2024, coupled with geopolitical risk premium resulting from conflicts in Europe and the Middle East.
The geopolitical narrative began to untangle in 2024, and then completely unravel in 2025, as markets no longer price in any real oil shock risk.
 This story has been exacerbated in 2025 with a twofold blow in early April: Trump announced his Liberation Day tariffs, and Opec+ announced plans to raise production even further, from an increase of 114,000 barrels a day (b/d) to 411,000 b/d by May, which shocked the oil market.
It is key to note that non-oil expansion depends on crude prices to finance growth, rather than for oil’s contribution to GDP. In Saudi Arabia, for example, non-oil GDP grows at about 2% when oil is below the $60 a barrel range, versus 4.7% on average above $80 a barrel.
Low oil prices become a concern when discussing GCC government budget balances. Economic diversification and oil decoupling plans have required high levels of capital expenditure, as the region begins to brace for a future of less oil dependency – though the deadline for this remains at least 10 years away.
Although GCC markets have decoupled from oil, overall funding and spending in the GCC remains driven by oil revenues. This can be seen with the breakeven oil prices for GCC countries.
There is a wide range of fiscal breakeven points within the GCC, with states such as Bahrain and Saudi Arabia suffering the most from drops in oil revenues. Despite these variations, the outlook for oil can be summarised in four points:
- Opec+ policy creates excess supply, coupled with weak global – and namely Chinese – demand on crude;
- Pricing out of geopolitical risk;
- Tariff policy creates global uncertainty, especially in energy-intensive industries;
- An Opec decision on production numbers will hinge on the outcome of Trump’s visit to Saudi Arabia, Qatar and the UAE.
TS Lombard does not expect oil prices to fall much further. It would not be in Trump’s favour to depress oil prices too far, as it would result in too much pain for US shale producers.
Trump wants lower energy inputs; a positive supply-side factor; and to showcase a win from his campaign pledges, many of which have yet to materialise. Nonetheless, the base case for oil remains bearish this year relative to the past two years, although TS Lombard is not overly negative on expectations about current price equilibrium in the $60-$70 a barrel range.
 Potential upside
With markets remaining in a tumultuous state, and while questions are being asked about trade deals and the re-implementation of tariffs, it is key to note that oil, energy and various petrochemicals products have been exempt from US tariffs.
This means that, for a volatile and demand-dependent market, oil may see some upside towards the end of this year, as markets begin to price in tariff risk and supply-side disruption.
In terms of non-oil exports from the GCC to the US, with the exception of aluminium, little has changed from pre-Liberation Day operations.
In 2024, the US enjoyed a trade surplus with the GCC in general. For example, 91% of Saudi exports to the US in January 2025 were crude or crude-based products such as ethylene, propylene polymers, fertilisers, some plastics products, and rubber – most of which are exempt from tariffs.
For the UAE, 80% of exports to the US were similarly exempt, including supplying the US with 8% of its total aluminium demand. Significantly, Canada and China are the main aluminium exporters to the US.
With China and Canada also being major targets for Trump, countries such as the UAE and Bahrain will maintain a competitive advantage in selling to the US market, despite facing either the 10% baseline tariff, or the specific 25% aluminium tariff. The best case scenario is that both these GCC states are able to negotiate a trade deal that could exempt or curb the negative tariff effect on their aluminium exports.
Limiting impact
Although several industries have already suffered – as petrochemicals in general has suffered because of the drop in demand and oversupply in the market – the GCC finds itself in a unique position. Its economies are geared to being market- and trade-friendly, and they have low regulatory barriers, large amounts of space and energy to engage in manufacturing-intensive activities.
Coupled with strong relations with the Trump administration, the GCC has both an economic and geopolitical opportunity to act as a global intermediary. It has already been announced that Trump’s first foreign visits will be to the region, and today major global negotiations – from ceasefires to investment mandates – take place in the GCC.
A common argument being made regarding the latest output decision by Opec+ is that it is a geopolitical ploy to appease Trump’s pursuit of lower energy prices and gain favourable negotiating positions for the GCC states. Items on this docket range from civilian nuclear and drone programmes through to the approach to Iran and the Gaza-Israel question.
 Saudi Arabia’s non-oil GDP remains high, showing the resilience of the kingdom when facing economic headwinds. Specifically, the kingdom has kept up its streak of strong non-oil purchasing managers’ index performances.
With the GCC exhibiting stable conditions as the world moves towards uncertainty and erecting trade barriers, the region’s overall competitiveness could be enhanced. This is especially true in the case of the real economy, where investments still have a mostly local rather than international reliance.
Overall, the short-term story relates to oil – and namely to the capital flows that oil brings, which fund economic diversification expenditures in the GCC.
Although lower oil prices are a key detractor for the region, the story is far from being all bad news.
Improved geopolitical relations and opportunities arising from the positioning of the GCC states allows them to exploit emerging gaps in markets that were previously dominated by economies that have been targeted with tariffs.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors prepare bids for more Qiddiya infrastructure
8 October 2026
-
 Chinese contractors begin Jordan rail construction
8 October 2026
-
-
 Drilling resumes at Iraq’s Akkas field
8 October 2026
-
 Neom extends bid deadline for Oxagon wastewater plant
8 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Contractors prepare bids for more Qiddiya infrastructure
8 October 2026
Saudi gigaproject developer Qiddiya Investment Company (QIC) has tendered a design-and-build contract covering infrastructure works at District 0 in Qiddiya City.
The scope includes the design, supply, construction, testing, commissioning and defects liability period for Road I in District 17, Road Q in District 19 and the District 18 Ring Road.
In total, the package covers approximately 17.4 kilometres of roads, including 1.4km of bridge structures.
Contractors have until 14 October to submit proposals.
Beirut-headquartered Dar Al-Handasah is the lead design consultant for districts 17 and 19, with a remit that also includes potable water and recycled water storage tanks and pumping stations.
US-based Jacobs is the lead design consultant for the District 18 Ring Road.
The tender is the third infrastructure package for Qiddiya’s District 0. The first two packages, tendered in March, remain under procurement, as MEED exclusively reported.
MEED understands that bid evaluation for these packages is in its final stages and that awards are expected shortly.
QIC is also advancing plans to develop additional assets at Qiddiya City.
Last month, MEED exclusively reported that QIC had awarded an estimated $500m-$600m contract to build an e-games arena, known as the Fortress Arena.
The scope of work includes the construction of an auditorium with a capacity of about 5,100 seats, as well as commercial areas, hospitality facilities and other associated infrastructure.
The Fortress Arena is one of several major projects within the wider Qiddiya development.
Other projects include the Dragon Ball theme park, Prince Mohammed Bin Salman Stadium, a horse-racing venue, a performing arts centre, the Speed Park, the National Tennis Centre, Six Flags Qiddiya City and Aquarabia water park.
The project is a key part of Riyadh’s strategy to boost leisure tourism in the kingdom. According to UK analytics firm GlobalData, leisure tourism in Saudi Arabia has grown significantly in recent years.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20384978/main.jpg -
Chinese contractors begin Jordan rail construction
8 October 2026
Beijing-headquartered firms China Civil Engineering Construction Corporation (CCECC) and China First Highway Engineering Company (CFHEC) have started construction work on the Aqaba-Al-Shidiyeh-Maan Railway project in Jordan.
The 403-kilometre rail network is divided into six packages. CCECC is executing packages one to four, while CFHEC is undertaking packages five and six.
The scope of work covers constructing railway tracks, about 55 bridges, six tunnels and related structures.
The project aims to link Aqaba with key mining and production sites and the Maan logistics zone, establishing an integrated system for transporting bulk cargo and containers between ports, production centres and inland logistics facilities.
The network is expected to carry around 16 million tonnes of phosphate and potash each year from production sites to Aqaba’s ports.
In April 2025, a French-Swiss joint venture of Egis and Arx was awarded the project’s design consultancy contract.
The estimated $2.5bn project is being developed by the Jordan-UAE Railway Company, which is jointly owned by Abu Dhabi’s L’imad Holding and Jordanian entities including the Jordan Phosphate Mines Company, the Government Investments Management Company, the Social Security Investment Fund and the Arab Potash Company.
Jordanian and UAE officials attended a groundbreaking ceremony held earlier this week to mark the formal start of construction work.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20371915/main.jpg -
Iraq discusses starting operations at $3.78bn refinery project
8 October 2026
Iraq’s Minister of Oil, Basem Muhammad Khudair Al-Abadi, has met with Japanese officials to discuss plans to commission the fluid catalytic cracking (FCC) unit at the Basra refinery upgrade project, according to a ministry statement.
The meeting was attended by the Japanese Embassy’s executive officer as well as representatives from the Japan International Cooperation Agency (Jica) and Japan-based JGC, which is the main contractor on the project.
According to the ministry, discussions focused on direct implementation steps and coordination between Iraqi authorities and the Japanese partners to bring the unit online using Japanese refining technologies.
Iraq’s South Refineries Company (SRC) sent JGC notice of the main contract award for the Basra refinery upgrade project’s FCC package in August 2020.
JGC was awarded the contract in consortium with South Korea’s Hyundai E&C.
The official contract signing ceremony was held in Baghdad on 1 October 2020.
The contract awarded to JGC, which uses the engineering, procurement, construction and commissioning model, was worth $3.78bn.
Project delays
The project has faced issues related to the ongoing regional conflict, which started when the US and Israel attacked Iran on 28 February.
JGC evacuated its personnel from the site in the southern oil hub of Basra following the start of the regional war, stopping work on the project, which was in its final stages of construction.
In August, JGC signed an agreement to restart work.
The project will produce around 5 million litres a day of gasoline and 7 million litres a day of diesel.
The FCC package is part of a broader project to upgrade the Basra refinery.
Oil Ministry officials said in late 2025 that the Basra refinery upgrade project aims to slash Iraq’s fuel import bill and convert heavy refining residues into high-value petroleum products.
The project site is located about 12 kilometres east of Iraq’s southern city of Basra.
The wider upgrade project is installing new facilities on land adjacent to the existing Basra refinery, including a vacuum distillation unit and a diesel desulphurisation unit.
In April 2021, France’s Axens won a contract to provide four process technologies to SRC for the Basra refinery upgrade project.
The technologies that SRC selected are:
- Diesel hydrotreatment unit (Prime-D)
- Vacuum gasoil (VGO) hydrotreating unit
- VGO fluid catalytic cracker unit
- Oligomerisation unit (polynaphtha)
In addition, Axens is providing catalysts and adsorbents and proprietary equipment, training and technical services.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20366574/main.png -
Drilling resumes at Iraq’s Akkas field
8 October 2026
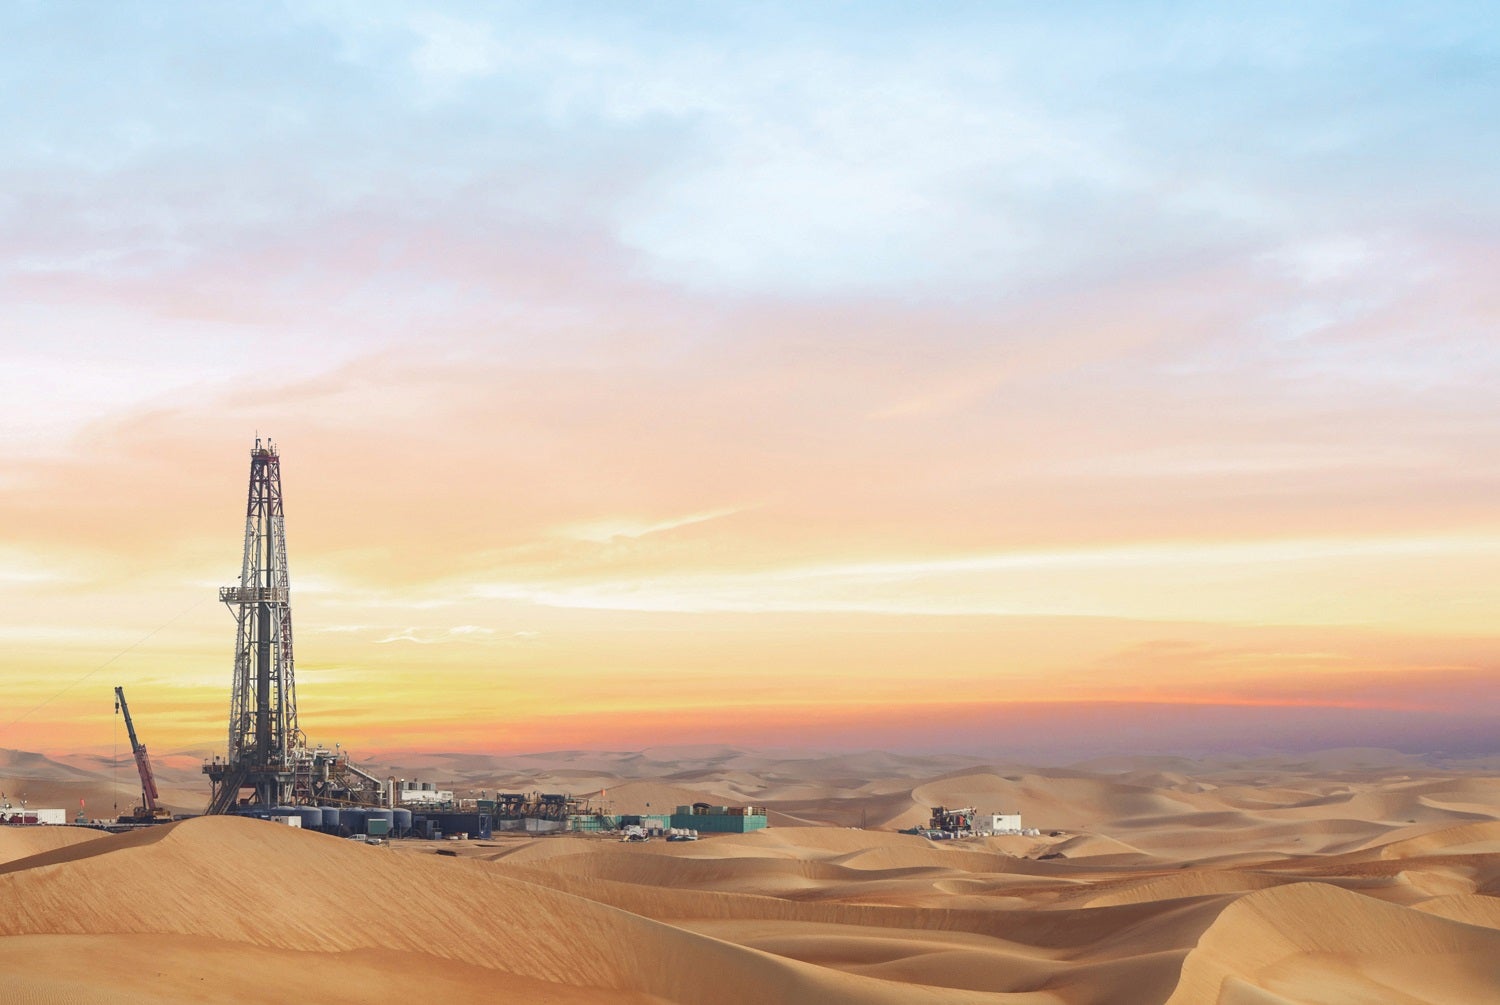
Drilling has resumed as part of the project to further develop Iraq’s Akkas gas field, according to industry sources.
In March, MEED reported that development of the field had been disrupted by security issues related to the US and Israel’s war with Iran.
Activity at the project site had been significantly reduced due to security concerns, which led to the evacuation of most non-Iraqi workers.
Now, the project is progressing and drilling at the field is ongoing, sources said.
One source said: “Many of the major issues that stopped drilling at the site have been dealt with in various ways, and the development of the field is proceeding.”
Iraq held a ceremony in January to mark the start of drilling operations under the current phase of development. In July of the previous year, the Iraqi Oil Ministry announced a contract with US-based oilfield services provider SLB to develop the field. Under the agreement, SLB is drilling wells to raise initial output to 100 million cubic feet a day (cf/d), with a long-term production target of 400 million cf/d.
The contract with SLB replaced a previous deal with Ukraine-based Ukrzemresurs, which has been terminated.
It also covers the construction of surface infrastructure and pipelines to connect Akkas to central processing units.
The gas produced at Akkas will fuel the Anbar combined-cycle power plant, which the Electricity Ministry is building.
Akkas gas field development
Located in western Anbar province, Akkas holds an estimated 5.6 trillion cubic feet of proven natural gas reserves. The field was discovered in 1992 and entered initial production in 1993, but efforts to develop it commercially have faced repeated delays.
Development rights were originally awarded to a consortium of South Korea’s Kogas and Kazakhstan’s KazMunaiGas (KMG) during Iraq’s third licensing round in 2010. After KMG withdrew, Kogas took over as sole operator under revised contractual terms before work was subsequently halted.
In April 2024, the Oil Ministry signed an agreement with Ukraine’s Ukrzemresurs targeting 100 million cf/d within two years and 400 million cf/d within four years. However, the deal faced strong domestic political resistance.
Iraq’s parliamentary Oil and Gas Committee opposed the award, with committee member Ali Al-Mashkour telling Shafaq News Agency: “This contract involves a great waste of Iraq’s wealth, and there will be a waste of Iraq’s oil, and this confirms that Iraq is once again failing to choose reputable companies to work with in the most important economic field in the country.”
He added: “We will work to uncover and expose the suspicions in this contract during the next stage, especially since this contract was made by some representatives for specific interests, which we will reveal soon with evidence.”
The deal was subsequently terminated, paving the way for the current contract with SLB.
The development of Akkas is central to Baghdad’s broader ambition to transition from a net gas importer into an exporter. Iraq remains heavily dependent on gas imports from Iran to meet domestic electricity demand. Both the US and Saudi Arabia have backed Iraq’s efforts to develop non-associated gas fields to reduce its economic and energy dependence on Tehran.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20366494/main5816.jpg -
Neom extends bid deadline for Oxagon wastewater plant
8 October 2026
Neom has extended the bid submission deadline for a contract to build a wastewater treatment plant for Oxagon, its industrial cluster.
According to a source, the new deadline is 25 October. The original deadline was 2 October.
Enowa, Neom’s energy and water utility, is tendering the contract.
The industrial wastewater treatment package will have an initial capacity of 35,000 cubic metres a day (cm/d), supplied in modular trains of 5,000 cm/d each. A separate sanitary wastewater treatment package will have a capacity of 1,000 cm/d.
The contract is structured as a design-build-operate project and covers the supply, installation and commissioning of industrial and sanitary wastewater treatment packages, as well as three years of operation and maintenance.
According to sources, local contractor Alfanar, Beijing-based PowerChina and France-based Veolia are among the companies preparing bids.
The project follows an earlier tender for the Oxagon Village Water Recycling Plant, which was cancelled despite contractors submitting bids in 2024.
MEED reported at the time that PowerChina, Alfanar and Cairo-headquartered Orascom had submitted bids for that project.
The earlier scheme included truck-receiving facilities, pretreatment, biological treatment using food chain reactor technology, tertiary treatment, sludge handling and recycled-water storage.
The latest procurement appears to take a reworked approach to wastewater treatment at Oxagon Industrial Quarter. It replaces the previous engineering, procurement and construction scheme with an interim modular and demountable facility.
The plant is designed to provide “interim wastewater treatment” capacity for Oxagon Industrial Quarter as industrial development progresses.
As MEED understands, this includes treatment systems that can be installed and subsequently removed or relocated as requirements at Oxagon evolve. The plant can be expanded to a maximum capacity of 45,000 cm/d.
The tender documents also state that Neom may consider export credit agency (ECA) financing for the project. The strength of bidders’ ECA financing proposals will form part of the commercial evaluation.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20347018/main.jpg