
Iraq enters era of resilience, reform and rising risks
11 May 2026

Iraq’s projects market is at an inflection point. The country has built a sizeable and increasingly diverse projects pipeline, backed by ambitious national plans and an improving reform narrative. But according to MEED’s newly updated Iraq Projects Market report, the near-term outlook is now being tested by renewed regional volatility and persistent structural constraints at home.
Iraq is the Middle East and North Africa’s fifth-largest economy by nominal GDP, yet it remains heavily exposed to the hydrocarbons cycle. Oil and gas generate about 90% of government revenues and more than 40% of GDP, a dependency that shapes annual capital spending and the bankability of public-private partnership (PPP) deals. Earlier this year, the IMF forecast GDP growth of 3%-4%. In light of the latest regional conflict dynamics involving the US and Israel with Iran, that growth outlook is expected to soften as investor risk perceptions rise and supply chains face renewed stress.
Even so, Iraq’s projects market is not starting from a blank slate. By the end of March 2026, almost $120bn of contracts were in execution, with a further $300.4bn in the broader pipeline. The scale of that opportunity is underpinned by enduring reconstruction requirements, urgent energy-sector needs and a policy push to translate oil wealth into long-lived productive assets.
Reconstruction needs
Nearly a decade after the official end of the Islamic State conflict, Iraq’s reconstruction gap remains substantial. Estimates put the shortfall at about $88bn, reflecting the long tail of damage to housing, utilities, public buildings and transport links. Southern and central regions dominate the live pipeline, largely because they sit close to Iraq’s oil heartlands. Basra, in particular, is pivotal, anchoring major upstream activity and vital export infrastructure.
At the policy level, Iraq Vision 2030 signals a long-term ambition to diversify into tourism, agriculture, industry and digital transformation. The government’s immediate delivery vehicle is the National Development Plan (NDP) 2024-28, which commits more than $17bn a year in capital expenditure and prioritises energy, transport, housing and water infrastructure. This shift is reinforced by Iraq’s Green Growth Framework (2026), indicating that future procurement may place greater weight on efficiency, emissions reduction and climate resilience.
Macro risk
Despite policy ambition, the most immediate determinant of Iraq’s fiscal room is the oil price. A $10-a-barrel drop can reduce government revenue by an estimated $7bn-$9bn annually. Such sensitivity matters because infrastructure spending is still largely funded by the public purse. Oil price swings affect project awards, payment cycles and the government’s willingness to assume up-front capex obligations.
Iraq’s execution environment continues to be defined by bureaucratic delays, unclear land titles and opaque procurement processes. These factors can add 12-24 months to average delivery timelines. Nevertheless, there are signs of adaptation. PPP legislation is advancing, and developer-led models are gaining traction in large housing programmes. Furthermore, there is a growing reliance on international project management consultancy (PMC) firms—such as Hill International, Worley, and AtkinsRealis—to bridge capacity gaps and improve governance, cost control and scheduling.
Hydrocarbon driver
Oil and gas upstream remains the single largest driver of capital expenditure. Major developments, including the Gas Growth Integrated Project (GGIP) and Mansouriya, sit alongside a push to reduce gas flaring and expand downstream processing. The objective is to sustain export revenues while improving domestic fuel availability.
The power sector is even more urgent. Iraq faces an estimated 8-10GW generation shortfall, which keeps electricity supply at the centre of political risk. This gap is driving rapid procurement of generation capacity and grid upgrade contracts. Beyond traditional infrastructure, Iraq is also moving on digital adoption. Smart city pilots and fibre rollouts are attracting regional technology investors, while AI-enabled data centre projects are beginning to emerge.
Investment targets
Foreign direct investment (FDI) remains below $3bn a year, a low figure relative to market size. The most active investors outside the oil sector include the UAE, Saudi Arabia and Kuwait. To convert interest into deals, the National Investment Commission (NIC) is pursuing streamlined licensing and investor-protection reforms. A “one-stop shop” approach has reportedly reduced registration timelines for foreign investors from months to weeks in key sectors.
Investor protection mechanisms, such as access to international arbitration, are being strengthened, though enforcement remains a concern. Iraq’s three free zones—Basra, Karbala and Nineveh—offer additional incentives including tax holidays and customs exemptions, provided they can be paired with reliable utilities and bankable arrangements.
Conflict premium
The latest escalation involving the US and Israel with Iran has increased Iraq’s security risk premium. This is inflating materials costs and disrupting supply chains near eastern border zones. Even where projects are far from conflict areas, contractors are pricing in higher contingency for logistics and insurance. Iraq must also balance deep economic ties with Iran—particularly in energy—with Western investor expectations and sanctions-related compliance.
With more than 60% of its population under 25, Iraq has a potential demographic dividend, but it also faces immediate employment pressure and a shortage of skilled technical labour. Iraq’s projects market outlook for 2026 is best described as cautiously constructive. The pipeline is deep and the need is undeniable, but delivery will hinge on whether Iraq can translate plans into predictable execution. If progress on procurement and contract enforcement continues, Iraq can sustain a broad-based market that extends beyond hydrocarbons.
Click here to learn more about MEED’s newly updated Iraq Projects Market report

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Expo Riyadh sets October deadline for Saudi Arabia pavilion
7 October 2026
-
 Kuwait on track to hit oil production target
7 October 2026
-
 Roshn plans new flagship development in Riyadh
7 October 2026
-
 Al-Yamamah signs Saudi 380kV transmission deals
6 October 2026
-
 Eagle Hills plans new Syria projects
6 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Expo Riyadh sets October deadline for Saudi Arabia pavilion
7 October 2026
Expo 2030 Riyadh Company (ERC), tasked with delivering the Expo 2030 Riyadh venue, has set a deadline of 25 October for bids for a contract to build the Saudi Arabia pavilion.
The tender was issued on 19 May, with an initial bid submission deadline of 26 August.
The pavilion is a major asset located within the KSA District on the eastern side of the Expo 2030 Riyadh masterplan, in the Loop of Nations district.
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Last month, MEED reported that ERC had received contractor interest on 14 September for a contract to design and build a convention centre in the site’s Collaboration District.
ERC also tendered a contract to deliver the Souq areas within the Expo site, as MEED exclusively reported on 8 September.
These areas are divided into five precincts, with a total development area of about 300,000 square metres.
Also in September, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to construct a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts for the next phase of infrastructure works at the site to local firm Al-Yamama Company.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle (EV) charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, as well as EV charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated north of the Saudi capital, the site will be near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20334856/main.jpg -
Kuwait on track to hit oil production target
7 October 2026
Kuwait is on track to meet its target of having 4 million barrels a day (b/d) of oil production capacity by 2035, according to Kuwait Petroleum Corporation (KPC) chief executive Shaikh Nawaf Al-Sabah.
Al-Sabah also said Kuwait is on course to increase non-associated gas production to 2 billion cubic feet a day by 2040.
His comments come amid an ongoing crisis in Kuwait’s oil and gas sector linked to the regional conflict that began when the US and Israel attacked Iran on 28 February.
The subsequent war has significantly disrupted shipping through the Strait of Hormuz, which is a crucial export route for Kuwaiti crude oil.
Kuwait is currently producing around 2 million b/d of oil, down from 2.6 million b/d before the US and Israel attack.
Speaking at a conference in London, Al-Sabah said: “We have the capacity to go back up to our current maximum sustainable capacity of 3 million b/d, if we have the export routes available, and this comes down to the ability to move oil through the Strait.”
KPC is investing $9bn-$10bn a year in capital expenditure to meet its oil and gas production goals, according to Al-Sabah.
He said: “We are doing this because we recognise that it is our hydrocarbons that will be most in demand a decade from now, and two decades from now – in fact, for the rest of our lifetimes.”
Project Seef
KPC is pushing ahead with the Al-Seef project, which focuses on developing three large offshore oil discoveries, Al-Sabah said.
The offshore fields are known as Nokhatha, Julaia and Jazza. The development was first announced in February this year, about two weeks before the US and Israel attack on Iran.
Al-Sabah said KPC is continuing with the project and believes the three fields collectively hold more than 3 billion barrels of recoverable oil.
He said: “We are asking international oil companies to partner with us to develop those resources under an operating services contract.
“So, we’re moving ahead according to the exact same schedule that we had put together even before the war began.”
Al-Sabah did not say which international oil companies KPC has approached to help develop the three offshore fields.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20315147/main.jpg -
Roshn plans new flagship development in Riyadh
7 October 2026
Saudi developer Roshn Group plans to develop its next flagship scheme in north Riyadh, spanning an area of 13.7 square kilometres.
Roshn is looking to appoint lead design consultants to deliver detailed design, tender documentation and construction documents across the scheme, known as Plot 1.
The scope covers all infrastructure, utilities, public realm works and site adaptation of Roshn’s residential prototypes, split across two work packages.
Part 1 covers phases A, B and E, which collectively span about 7.8 million square metres (sq m) and will comprise 17,000 units.
Part 2 includes phases C and D, which will span about 4.7 million sq m and comprise more than 15,000 units.
The development is bordered by Expo 2030, King Abdulaziz Park, the Sports Innovation Lab Zone and the National Housing Company-developed Khozam district.
It will be a residential-led mixed-use development, also featuring retail, offices, hospitality, education and civic facilities.
Connectivity is a core plank of the masterplan, with two metro stations planned: one at the existing Line 4/proposed Line 7 interchange and another dedicated Line 7 stop. The scheme would also be served by the future Qiddiya high-speed rail and a possible King Salman Road diversion.
Plot 1 builds on Roshn’s existing footprint in the capital, notably the multi-phase Sedra community, as the developer expands beyond single-family housing into mixed-use districts under its Roshn 3.0 strategy.
Last month, Roshn Group announced that it had signed a preliminary agreement with Talaat Moustafa Group (TMG) Saudi, the local subsidiary of Egyptian developer Talaat Moustafa Group, to establish a joint venture to explore and develop a mixed-use project in Riyadh.
Under the agreement, TMG will hold a 51% stake in the joint company, while Roshn Group will hold 49%.
The agreement sets out a framework for the two groups to assess a potential partnership for the project’s phased development, which is planned as a residential-led, mixed-use community featuring retail, commercial, hospitality, leisure, healthcare and education facilities, alongside parks and public spaces.
Roshn Group and TMG Saudi plan to conduct detailed master planning and develop the project’s business case.
Preliminary studies indicate the development could include more than 55,000 residential units across all phases.
Roshn Group did not disclose the exact project location in its announcement.
As a Public Investment Fund-owned developer, Roshn remains a key vehicle for delivering Vision 2030’s housing programme, which targets 70% Saudi home ownership, alongside the kingdom’s wider quality-of-life and economic diversification agendas.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19786131/main.jpg -
Al-Yamamah signs Saudi 380kV transmission deals
6 October 2026
Riyadh-headquartered Al-Yamamah Steel Industries has signed two supply contracts with Algihaz Contracting Company for the construction of 380kV ultra-high-voltage transmission lines in Saudi Arabia’s Western Region.
The contracts cover the supply of steel towers and are worth a combined SR254.28m ($67.8m).
In a disclosure to the Saudi Exchange (Tadawul), the firm said the first contract is valued at SR135.65m ($36.2m), while the second is worth SR118.63m ($31.6m).
Both contracts have a one-year duration, with supply scheduled to begin in March 2027. The financial impact of the contracts is expected to start appearing in Al-Yamamah Steel’s results in the first quarter of 2027.
Algihaz is currently carrying out construction works for several transmission projects, including Saudi Energy’s $206m Bisha 380/132kV BSP connection project, for which it was appointed the main contractor in 2025.
The project involves a double-circuit 380kV overhead transmission line connecting the Bisha PV bulk supply point to the existing bulk supply points in Aseer Province.
The deals also add to a series of steel tower contracts secured by Al-Yamamah Steel for 380kV transmission projects in the Western Region.
In September, the company signed a SR103.14m ($27.5m) contract with the Saudi branch of National Power Construction Corporation to supply steel towers for a 380kV ultra-high-voltage line. Supply under that contract is due to begin in February 2027.
Al-Yamamah Steel also signed a SR176.48m ($47.1m) contract in November 2025 with Arabian Electrical Transmission Line Construction Company to supply steel towers for another 380kV ultra-high-voltage line in the Western Region.
The company has expanded its tower production capacity in recent years to meet expected demand for steel towers used in electricity transmission lines. Its 2024 annual report said it had added production lines and a galvanising plant in Jeddah Industrial City for this purpose.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20308551/main.jpg -
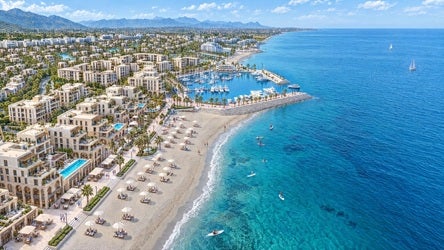
Eagle Hills plans new Syria projects
6 October 2026
Abu Dhabi-based real estate developer Eagle Hills has signed a framework agreement with Syria’s Ministry of Public Works & Housing to develop a series of residential and tourism community projects across several Syrian governorates.
The first phase will include Damascus Heights in the capital and Latakia Yachts & Marina on the Mediterranean coast.
Damascus Heights is planned as a mixed-use community comprising homes, retail, hospitality and business facilities, supported by schools, healthcare services, green areas and resident amenities.
Latakia Yachts & Marina is planned as a waterfront destination anchored by a marina, with homes, hotels, branded residences and leisure offerings.
During development and operation, the projects are expected to support economic activity and tourism, create jobs across construction, hospitality and services, and add new housing, community facilities and tourism infrastructure.
Syrian professionals and businesses are expected to play a central role in both delivery and operations, creating opportunities for contractors, suppliers and service providers, strengthening local supply chains and SMEs, and supporting skills development and knowledge transfer.
Eagle Hills is also inviting applications for investment participation from Syrians in Syria and abroad, with priority for qualified Syrian individuals, businesses and institutions.
Following the signing, both projects will proceed to implementation, with enabling and construction works expected to begin shortly in Damascus and Latakia.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20308460/main.jpg