Acwa Power tightens grip on GCC water
26 January 2024

This report also includes: Mena water delivers exceptional growth
Time-bound sustainability objectives and improving economic conditions kept the GCC region’s water sector projects buoyant in 2023.
This coincided with the key milestones achieved by independent water producer (IWP) contracts awarded between 2020 and 2021, which reached either the commissioning or commercial operation stages in 2023 following two years of disruption caused by the Covid-19 pandemic.
The UAE awarded three IWP contracts in 2023 and Saudi Arabia awarded one. This was a remarkable recovery considering that there was only one contract award in 2021 and none in 2022, barring the directly negotiated contract for the development of Shuaibah 3 in Saudi Arabia.
In contrast, there were no new awards for independent water and power producer (IWPP) projects – a model that worked successfully from the 1990s until the mid-2010s, when policies started to shift away from thermal desalination technologies and towards IWPs that rely on reverse osmosis technology for water treatment.

Source: MEED
IWP awards
The IWP contracts awarded in 2023 include Mirfa 2 and Shuweihat 4 in Abu Dhabi, Rabigh 4 in Saudi Arabia and Hassyan 1 in Dubai. The four IWP schemes have a total combined capacity of about 2.3 million cubic metres a day (cm/d).
The award of these contracts resulted in higher net and gross capacities for Saudi utility developer Acwa Power, France’s Engie and Spain-headquartered GS Inima, relative to the last MEED water developer ranking published in January 2023.
Acwa Power’s overall net capacity leapt by 20 per cent in 2023 to reach approximately 3.5 million cm/d. This resulted from its 40 per cent equity in Dubai’s Hassyan 1 IWP project, which has a capacity of over 818,000 cm/d; and its 45 per cent shareholding in the 600,000 cm/d Rabigh 4 IWP.
Engie likewise posted an impressive two-digit rise in terms of its net capacity, growing from 1.67 million cm/d to 1.87 million cm/d, thanks to its 40 per cent equity in the Mirfa 2 IWP project in Abu Dhabi.
The size of the two projects that Acwa Power won in 2023, however, meant it managed to further widen its lead over Engie and the other private water developers operating assets across the GCC states.
At 3.5 million cm/d, Acwa Power’s overall net capacity is equivalent to the total combined net capacity of the next five developers in the ranking: Malaysia’s Malakoff, Japan’s Marubeni and Sumitomo, and GS Inima, in addition to Engie.
The Saudi utility developer has also for the first time overtaken Engie in terms of gross water desalination capacity. As
of the end of 2023, its gross capacity crossed 7.7 million cm/d compared to Engie’s 7.0 cm/d.
In terms of ranking, GS Inima registered the most significant improvement among the top 10 private water developer companies, advancing three spots to rank fifth, having grown its net equity capacity nearly 50 per cent to reach close to 383,000 cm/d. This change takes into consideration that Kuwait’s Gulf Investment Corporation (GIC), which was included in the previous index, has been excluded this year due to its role as an investor rather than a developer of water desalination projects.
GS Inima will maintain a 60 per cent shareholding in Abu Dhabi’s Shuweihat 4 IWP scheme, which is expected to reach commercial operation by mid-2026.
Despite not having won any new contracts, Saudi Brothers Commercial Company and Abdulaziz al-Ajlan, both Riyadh-based, managed to land in the top 10 ranking of water developers this year, mainly due to the exclusion of both GIC and Water & Electricity Holding Company (Badeel), which is fully owned by Saudi Arabia’s Public Investment Fund.
Outlook
The next 12 months will likely be an active period for the water industry, particularly in Saudi Arabia.
This is mainly due to the target set by the kingdom’s Environment, Water & Agriculture Ministry to meet 92 per cent of Saudi Arabia’s water demand using desalinated water by 2030, to reduce reliance on ground and surface water.
Both Saudi Water Conversion Corporation, the world’s largest desalinator, which supplies 69 per cent of Saudi Arabia’s water, and Saudi Water Partnership Company (SWPC) will have to get “plants up and running as soon as possible to make this target”, says Robert Bryniak, CEO of Dubai-based Golden Sands Management Consulting.
Elsewhere – particularly in the UAE and, to a lesser extent, Oman – expiring contracted capacity and growing demand are expected to continue to drive the procurement of additional seawater reverse osmosis (SWRO) capacity.
The past few years have seen several international and local developers and investors enter the GCC’s water desalination market.
“The water industry could benefit by having more engineering, procurement and construction (EPC) contractors and developers, but I do not see this holding back procurers in launching new projects,” says Bryniak. “Having said that, there is definitely room for the water industry to accommodate more developers and EPC contractors.”
Tariff trend
Tariffs, or the long-term levelised costs that offtakers pay for water that private developers produce, are expected to trend upwards in 2024. This is due to higher interest rates and inflationary pressures on materials and supplies.
“These considerations, coupled with a limited number of experienced EPC contractors with excess contracting capacity, suggest that it will be tough seeing lower tariffs this year,” Bryniak says.
“We expect this trend due to the expected higher costs,” says another water desalination expert based in the UAE.
“The tariff for the Hassyan 1 IWP was low, but I see that as an anomaly,” says Bryniak, referring to the $cents 36.5 a cubic metre ($c/cm) tariff that Acwa Power proposed last year to develop the Hassyan 1 IWP in Dubai.
The previous tariff bid for the project was about 30 per cent lower than that proposed by Acwa Power last year, and it is likely that the bidder “had tremendous pressure to maintain a relatively low tariff to secure the project”, says Bryniak.
Future projects
SWPC issued the tender for the contract to develop the Jubail 4 and 6 IWP schemes on 1 January, and the tendering process is also under way for the Ras Mohaisen IWP. Both contracts are expected to be awarded before the end of this year.
In addition, SWPC has indicated that four more IWPs are expected to reach commercial operation by 2027, which implies that it could start seeking interest from developers for these projects in the next 12-24 months.
Under the latest plan, the Ras al-Khair 2 and 4, Al-Rais 2 and Tabuk 1 IWP projects will have a combined total capacity of 1.7 million cm/d.
In the UAE, Acwa Power is understood to be the sole bidder for the 400,000 cm/d Hamriyah IWP in Sharjah. The contract could be awarded in the first half of 2024.
In Abu Dhabi, the tendering process is under way for two SWRO plants that will be developed under one contract. The Abu Dhabi Islands SWRO projects will each have a capacity of 227,000 cm/d.
Kuwait’s two IWPPs – Al-Zour North 2 & 3 and Al-Khiran 1 – and the Facility E IWPP in Qatar include water desalination units with capacities of 695,000 cm/d and 454,000 cm/d, respectively.
MEED understands that an option is open for the bidders to use membrane technology for the desalination units of these planned facilities.
Unstoppable
Acwa Power thus appears unstoppable given its plans to further consolidate its presence in the region’s water industry, and pursue new technologies and partnerships, as its CEO Marco Arcelli told MEED in July last year.
The company plans to work with Japanese membrane technology provider Toray Industries to explore energy-saving technologies for SWRO. It is also working with other suppliers located in the US, Japan and China, as well as with Saudi Arabia’s King Abdullah University of Science & Technology to explore energy-efficient solutions for treating seawater.
The scale of the IWP projects Acwa Power has won between 2019 and 2023 enables it to outprice key competitors, or bid for projects deemed too risky by other developers.
The firm’s offer to develop Rabigh 4 for $c0.458/cm, for instance, was lower than what some of its competitors anticipated Acwa Power was capable of offering, although it lost Mirfa 2 to Engie a few months earlier.
As it is, Acwa Power won five of the 12 IWP contracts that were tendered and awarded in Saudi Arabia, the UAE and Oman during the past four years, equivalent to more than 56 per cent of the gross capacity awarded over that period.
Other developers should take note as they establish strategies to win more contracts in the future and potentially slow down Acwa Power's three-year sector dominance.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Oman signs 1GW battery storage agreement
3 November 2026
-
 Consultants bid for Roshn’s north Riyadh scheme
3 November 2026
-
 Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
-
 Sultan Al-Jaber appeals for global energy security reset
2 November 2026
-
 Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Oman signs 1GW battery storage agreement
3 November 2026
Oman's Nama Holding, a subsidiary of Oman Investment Authority (OIA), has signed a framework agreement with China's State Grid International Development to develop battery energy storage systems (bess) with a targeted capacity of 1GW.
The agreement covers two battery storage systems, each with a capacity of 500MW, at Duqm Industrial Station and Al-Subaikhi (Ibri Solar 3) Station.
It is understood that both systems will operate at 400kV and connect to Oman's national electricity transmission grid.
The deal is part of a package of economic and investment agreements signed by OIA with Chinese institutions and companies during the Oman-China conference on 2 November. OIA put the combined value of the bess projects at approximately RO384.5m ($1bn).
The agreement comes as Oman advances plans to expand its renewable energy capacity and strengthen the electricity transmission network.
Nama Power & Water Procurement Company is also procuring a separate 950MW standalone bess programme comprising five facilities in the sultanate, as MEED exclusively reported.
The wider package of agreements, signed during Sultan Haitham Bin Tariq's state visit to China, covers sectors including renewable energy, mining, logistics, digital transformation and space technology.
In the wind energy sector, Oman's O-Green and Shanghai Electric Wind Power signed a strategic partnership to establish a joint research and development centre and wind turbine testing facility at the Mawarid turbine factory in Duqm.
The partnership will focus on adapting turbine technologies to Gulf climate conditions, supporting local manufacturing and developing green ammonia projects in Oman.
The partnership is valued at RO3.85m-RO7.69m ($10m-$20m). It also identifies potential future contracts exceeding $1bn, alongside green ammonia projects and initial investment commitments in Oman exceeding $200m.
In solar, OIA signed a preliminary term sheet with Chinese firms PCG Power and Hoymiles for a partnership valued at RO38.45m ($100m).
The partnership aims to develop solar energy projects in Oman and establish a solar inverter manufacturing facility serving markets in the Middle East and North Africa.
It is also intended to support the localisation of solar-related industries, expand domestic production and develop export markets.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21102638/main.jpg -
Consultants bid for Roshn’s north Riyadh scheme
3 November 2026
Saudi gigaproject developer Roshn Group has received proposals from lead design consultants for its planned flagship development in north Riyadh.
Consultants submitted proposals on 1 November for detailed design, tender documentation and construction documents for the project’s first plot.
The planned development covers 13.7 square kilometres and will be a residential-led mixed-use scheme containing retail, office, hospitality, education and civic facilities.
The consultancy scope for plot one includes infrastructure, utilities, public-realm works and the site adaptation of Roshn’s residential prototypes. It has been divided into two work packages.
The first package covers phases A, B and E, which cover about 7.8 million square metres (sq m) and will include 17,000 units.
The second package covers phases C and D, covering about 4.7 million sq m and with more than 15,000 units.
The site is bordered by the Expo 2030 site, King Abdulaziz Park, the Sports Innovation Lab Zone and National Housing Company’s Khozam development.
Transport connectivity is a key element of the masterplan. Two metro stations are planned, including a station at the interchange between the existing Line 4 and planned Line 7, and a dedicated Line 7 station. The development could also be served by the planned Qiddiya high-speed rail link and a potential diversion of King Salman Road.
The scheme will add to Roshn’s existing development pipeline in Riyadh, which includes the multi-phase Sedra community. The developer is expanding its focus from single-family housing to larger mixed-use districts under its Roshn 3.0 strategy.
Last month, Roshn signed a preliminary agreement with TMG Saudi, the local subsidiary of Egypt’s Talaat Moustafa Group, to establish a joint venture to explore a separate mixed-use project in Riyadh.
TMG Saudi will hold a 51% stake in the proposed joint venture and Roshn will hold the remaining 49%. The companies said they will undertake detailed masterplanning and prepare a business case for the project, which preliminary studies indicate could include more than 55,000 residential units.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21101503/main.jpg -
Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
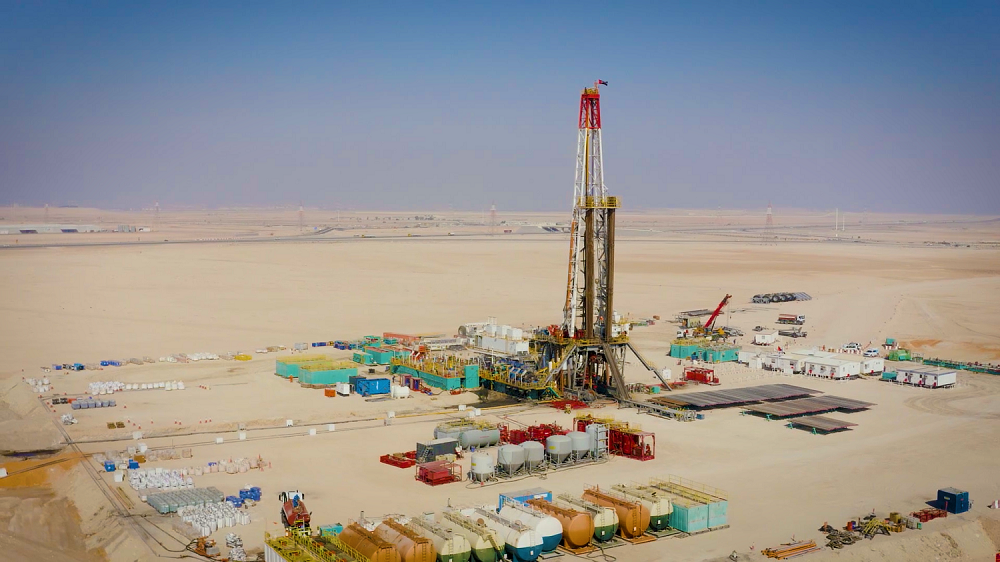
Abu Dhabi National Oil Company (Adnoc) has taken the final investment decision (FID) for the Ruwais Diyab unconventional gas development in Abu Dhabi.
The project will deliver 345 million standard cubic feet a day (scf/d) of raw gas from 2029 over a 25-year period, with the potential to reach up to 1 billion scf/d in the future.
Gas will be processed on site and connected to the UAE’s gas network through new pipeline infrastructure, “strengthening domestic supply, supporting the nation’s economic and industrial growth as well as Adnoc’s liquefied natural gas export ambitions”, the Abu Dhabi energy giant said when announcing FID on the project at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026.
According to sources, Adnoc has awarded the design, build and operate (DBO) contract for the Ruwais Diyab unconventional gas development to China-based Jereh Group.
A formal kick-off meeting between Adnoc and Jereh is expected to take place later in November, sources told MEED.
The DBO contract awarded by Adnoc to Jereh is understood to cover the second phase of the Ruwais Diyab unconventional gas development. The tendering exercise for the project started last year.
“The development [of Ruwais Diyab] follows a disciplined programme of technical studies, field testing and subsurface analysis, delivered by Adnoc Onshore under a DBO model, to reduce development risk,” Adnoc said in its statement on 2 November.
“It brings together advanced subsurface expertise, artificial intelligence-enabled drilling and completion technologies and integrated project delivery capabilities to support the efficient and responsible development of domestic gas resources,” it added.
The UAE holds the seventh-largest gas reserves in the world, with 298 trillion standard cubic feet (scf) of conventional gas reserves and 160 trillion scf of unconventional gas resources.
Adnoc holds the majority 60% stake in the Ruwais Diyab concession, the majority of which is situated onshore, while France’s TotalEnergies holds the other 40% interest.
The agreement to explore, appraise and develop the area’s unconventional gas resources was signed by Adnoc and TotalEnergies in November 2018. The partners announced first gas output at the concession, presumably on a pilot basis, two years later.
Adnoc has set a target of producing 1 billion scf/d of gas from the Ruwais Diyab concession by 2030, in line with its target to achieve self-sufficiency in overall gas production by the end of this decade.
“Ruwais Diyab’s additional unconventional gas supply will strengthen Adnoc’s gas value chain, including Adnoc Gas’s ability to meet rising domestic and international customer demand,” Adnoc said in its 2 November statement.
“Ruwais Diyab advances Adnoc’s ambition to establish a scalable unconventional gas business and create a platform for future growth,” the company added.
Ruwais Diyab first phase
Adnoc awarded the contract for engineering, procurement and construction (EPC) on the first phase of the unconventional gas development programme to local contractor Astra Engineering & Construction in early 2025, according to regional project tracker MEED Projects.
The first phase aims to achieve a gas output level of 100 million scf/d. The main structures to be built in the first phase include a central processing facility, two well pads, interconnecting well fluid pipelines, gas export pipelines and tie-in stations.
The EPC contractor will be required to provide services such as surveying, design, engineering, procurement, expediting, transportation, fabrication, construction, testing, installation, pre-commissioning, commissioning, site performance testing, operation and maintenance of all units.
The duration of the EPC works is understood to be 20 months, with the contractor also responsible for operating and maintaining the phase one facilities for 15 years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21100974/main4351.png -
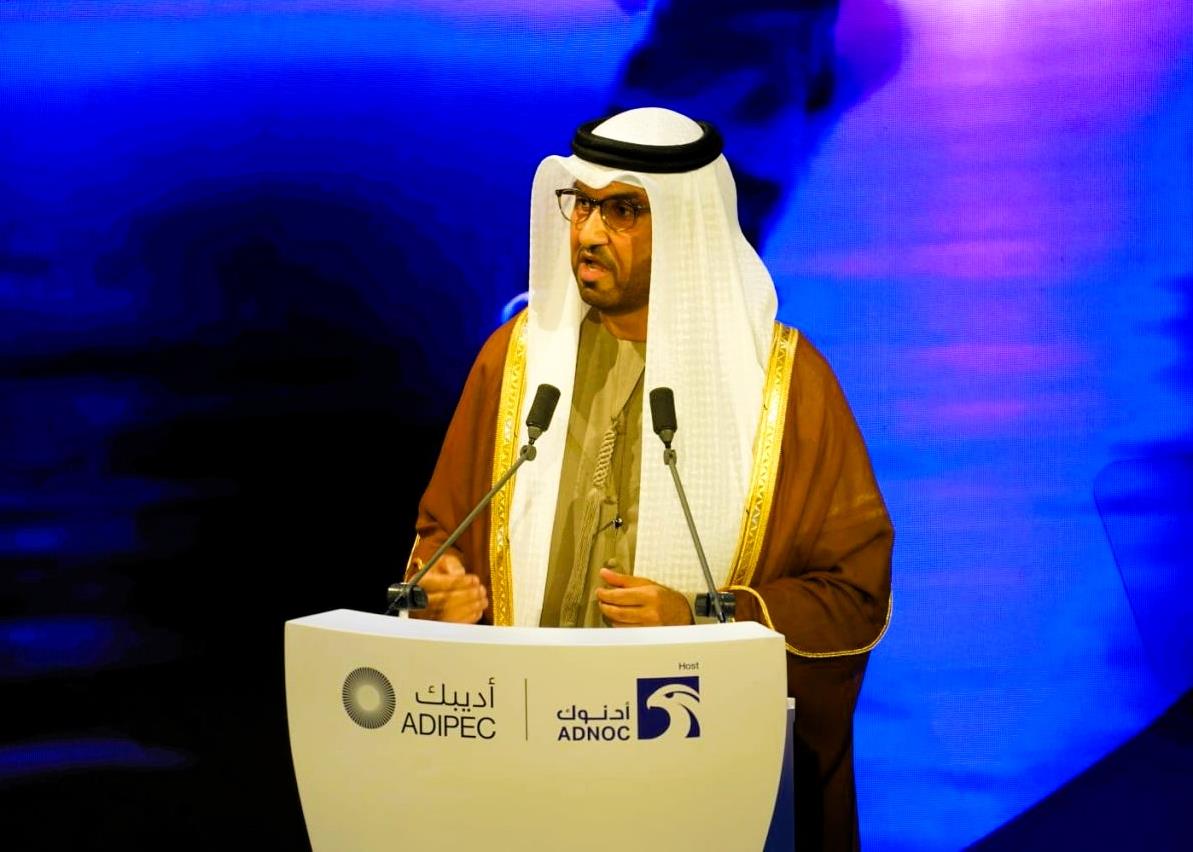
Sultan Al-Jaber appeals for global energy security reset
2 November 2026
The global energy industry must fundamentally rethink how it builds, protects and delivers secure energy, following a year of unprecedented disruption that has exposed critical vulnerabilities in international supply chains, Sultan Ahmed Al-Jaber, the UAE’s Industry & Advanced Technology Minister and managing director and group CEO of Abu Dhabi National Oil Company (Adnoc Group) has said.
Delivering the opening address at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026 on 2 November, Al-Jaber said preparedness is essential to navigating an increasingly uncertain global landscape.
“For decades, energy security was a question for specialists. It was debated in rooms like this, by people like us, in a language that few needed to learn. This year, every family, every farmer, every industry and every business owner is asking about it, and our collective job is to find the answers.”
Noting that it is not possible to control every situation and remove every risk, Al-Jaber said: “The choices we make today will determine the energy landscape a decade from now. Let’s apply the lessons we have learnt. Let’s build capacity and everything that supports it. Let’s forge partnerships that hold when it matters. And if you want a partner you can count on, you are in the right room, in the right city, in the right country. Because when it counts the most, you can count on the UAE.”
Setting out the case for a more resilient energy system, Al-Jaber said that since the disruption in the Strait of Hormuz, nearly 1 billion barrels of crude have been drained from inventories. He noted that in some markets, stocks of diesel are at their lowest seasonal level in 35 years, while others are facing a supply gap for liquefied natural gas (LNG) of 600 billion cubic feet. “Simply put, the world has eroded its supply buffers,” Al-Jaber said.
“But supply is only half the story. The other half is delivery. Before the disruption, logistics were less than 5% of the cost of a barrel. Today, they are more than 30%. In short, energy security is not only measured at the point of production. It is now also measured at the point of delivery.”
Mitigation steps
Al-Jaber outlined five steps the energy industry can take to reduce the impact of future shocks. “First, accessible supply. We need expanded strategic storage, larger stockpiles of products and flexible refining capacity closer to consumer markets.
“Second, routes to market. Supply only counts when it arrives. Infrastructure must be built before it is needed and enabled by advanced logistics.
“Third, operational intelligence. Moving from automated operations to intelligent energy systems that anticipate risk, optimise performance and drive down the cost of every barrel.
“Fourth, capital follows confidence. Policy must create it, finance must accelerate it and insurance must keep trade moving.
“Fifth, which is in my view the most important, is people. Because behind every barrel that arrives is a person who made sure it did. Systems don’t carry responsibility, people do.”
Photo credit: Adipec via LinkedIn
https://image.digitalinsightresearch.in/uploads/NewsArticle/21091189/main2954.jpeg -
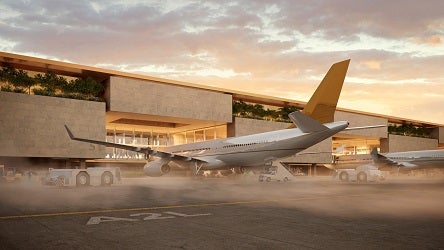
Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
Contractors are preparing bids for the main construction contract for Terminal 6 at King Salman International airport (KSIA) in Riyadh.
MEED understands that the consortiums have been given until 30 December to submit their proposals.
The participating consortiums are:
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
Last month, MEED exclusively reported that contractor teams have completed the early contractor involvement phase of the project.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
King Salman International Airport Development Company (KSIADC) is a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May 2025, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21087339/main.jpg