More pain for more gain for Egypt
7 February 2024
 This package on Egypt also includes:
> UK and Egypt sign infrastructure agreement
> Familiar realities threaten Egypt’s energy hub ambitions
> Egypt nears fresh loan agreement with IMF
> ADQ and Adnec invest in Egypt hospitality group
> Egypt’s President El Sisi secures third term
> Egypt 2024 country profile and databank

Egyptian President Abdel Fattah El Sisi might have hoped for a honeymoon period after his resounding election win in December, but has enjoyed not a bit of it.
Egypt started 2024 with an economic crisis gaining in intensity, with events in the Red Sea – sharply reducing traffic through the Suez Canal – compounding other challenges, including a foreign currency (FX) shortage, a depreciating pound on the parallel market and rising inflation.
The president’s words on 24 January were ominous: “Egyptians need to live with economic pain,” he said, indicating that 2024 would be a tough year.
With Egypt’s economic crisis worsening by the week, the siren calls for a support package from the Washington-based IMF have grown ever louder. Expectations are high that a new and larger extended fund facility (EFF) is imminent, with IMF officials visiting Cairo in January to hammer out a deal.
Analysts have suggested the EFF – initially set at $3.9bn – could now be as high as $10bn-$12bn. This increase reflects the desperate situation that Egypt is in.
It is also a sign that Egypt still has a few cards left up its sleeve – not least amid the current crisis in the Middle East that has left it playing a vital role, however ineffectually, as the main conduit for aid deliveries into Gaza.
The Red Sea crisis and the desire to keep a dependable security partner in the region afloat are also factors.
“There is a bit more political willingness to support Egypt than a year ago,” says James Swanston, Middle East and North Africa economist at Capital Economics.
Economic precipice
The immediate backdrop to the renewed EFF negotiations is the sharp deterioration in the value of the pound after a bad 2023 that saw the official rate depreciate by 25% against the dollar.
By the end of January, the pound was trading at £E68-£E70 to the dollar, more than double the official rate of nearly £E30.9 to the dollar. Although the announcement of an imminent deal with the IMF in early February led the pound to rally to £E55 to the dollar on 4 February.
The fiscal headwinds are nevertheless increasingly fierce in 2024. With about 60% of its revenues absorbed by interest payments, according to ratings agency Moody’s, the government has very limited fiscal headroom to respond to such shocks. Cairo’s dilemma is that even if the EFF is raised to the upper limit of $12bn, it will only partially cover its financing needs.
Meanwhile, ratings agencies have been busy downgrading the sovereign. Fitch Ratings cut Egypt’s long-term foreign currency rating to B- from B, with a stable outlook, in November, reflecting its perception of heightened risks to Egypt’s external financing, macroeconomic stability and the trajectory of already-high government debt.
The slow progress on reforms, including the delay in the transition to a more flexible exchange rate regime, has damaged the credibility of exchange rate policy and exacerbated external financing constraints at a time of increasing external government debt repayments, said Fitch.
External financing stresses influenced the downgrading of Egypt, says Paul Gamble, director of the sovereign group at Fitch Ratings.
“There are FX challenges becoming apparent and also concerns over the availability of foreign currency. There are significant black-market transactions and FX shortages, signalling that downward pressures on the currency have increased, and the path to policy adjustment has become more complicated, at a time of high external debt repayments.”
One particular challenge facing Egypt is that Egyptian expatriate remission inflows from the Gulf states have declined, with many getting a better deal on the parallel market than through official channels.
Then there are the Suez Canal revenues, which government officials say fell by 44% in January compared to the same month in 2023.
“The revenue collections from the Suez Canal are a very stable source of income for Egypt, so the fact that they have been hit is a bit of a concern,” says Gamble.
“The impact on investor sentiment and the parallel market rates could further complicate the transition to a more flexible exchange rate. On the other hand, the IMF is talking about upsizing its assistance programme, and Egypt is getting more bilateral attention.”
Next steps forward
Assuming the EFF is finalised, attention will then switch to what comes next.
The strings attached to that package will be substantial, incurring both political and economic costs.
Fiscal policy will see more stringency, with sharp cutbacks on spending. Major projects may lose some support. Yet, while these projects are important for job prospects in Egypt, the IMF’s message is to keep fiscal policy tight for now.
More stringency on the privatisation drive is also on the menu. Under the country’s divestment programme for state-owned enterprises (SOEs), speculators suggest that up to 150 SOEs may be sold off. However, political sensitivities over the military’s footprint in many of these assets mean delays are possible.
The most important thing in the near term is dealing with the pound, which was in virtual free fall at the end of January, forcing banks to install limits on FX transactions.
According to Capital Economics, if a staff-level agreement is announced, the central bank would move swiftly to devalue the pound by an initial 23%, to £E40 to the dollar, before allowing it to freely float.
“We feel [a rate of £E40-£E43 to the dollar] is a natural level, and it should not result in a fresh inflationary spike, but rather, inflation will fall at a slower rate,” says Swanston.
It was suggested that this could coincide with a sharp hike in interest rates of at least 300 basis points (bps), to 22.25%, and indeed, on 1 February, the central bank went ahead with this, raising the deposit rate to 21.25% and the lending rate to 22.25%.
That said, higher-for-longer prices and a 300bps interest hike will be painful for businesses to absorb, while a weaker pound will also make imports more expensive.
Yet, for all the doom and gloom, there are some green shoots. Egypt’s GDP growth is stable, with Capital Economics forecasting GDP growth of 3.5% in 2024-25.
Tourism – a valuable source of hard currency – is another recent bright spot, with arrivals to Egypt rising 9% in year-on-year terms during the first 19 days of 2024.
Egypt’s tourism numbers, spiking at approximately eight times higher than the global tourism rate of 4.5%, have been pivotal in stimulating overall growth, says property consultancy JLL. Between January and October 2023, Egypt registered about 13.9 million tourist arrivals, almost 36% higher compared to the same period last year.
“This is the medicine [the country] needs to take to lay the foundations for unlocking the economy’s potential in coming years,” says Swanston.
“They have a couple of years of slow economic growth, but if you have got an orthodox policymaking framework with a flexible exchange rate, and you bring the debt ratio down, you can start going about actually taking advantage of very good demographics of a young population.”
There will be much pain in the interim. But the consensus is that staying the course will lead to better days.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Read the October 2026 MEED Business Review
30 September 2026
-
 Aramco receives interest for major gas processing plant
30 September 2026
-
 Libya refinery expected to be worth more than $600m
30 September 2026
-
 Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
-
 Neom tenders Oxagon freight rail design
30 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Read the October 2026 MEED Business Review
30 September 2026
Download / Subscribe / 14-day trial access For all the talk of cancellations and cutbacks, Neom is still building – and its biggest completed project to date offers a clue to where the $500bn gigaproject is heading. Our October Agenda feature examines how Oxagon is moving to the centre of Neom’s strategy, as investment shifts towards projects with the potential to generate tangible commercial returns, from green hydrogen and ports to AI data centres and logistics infrastructure.
 Read the full analysis in the October issue of MEED Business Review.
As Neom reshapes its priorities, Saudi Arabia’s wider project market continues to show resilience. Contract awards have reached $68bn in 2026, despite regional conflict and economic uncertainty, with activity spanning energy, infrastructure, power and the future economy.
But with $91.5bn of projects completed this year, new awards will be crucial to maintaining momentum into 2027.
This edition also includes MEED’s 2026 power developer ranking, revealing the companies driving the region’s rapidly expanding power market.
The issue also explores key trends shaping the region, from AI’s growing demands on grid capacity and the implications of ICE Futures Abu Dhabi’s wind-down for Gulf commodity markets, to how the Hormuz crisis is redirecting oil companies’ focus to North Africa. Our Leadership feature asks whether the future city really needs to hang above the ground.
We hope our valued subscribers enjoy the October 2026 issue of MEED Business Review.
Must-read sections in the October 2026 issue of MEED Business Review include:
 > AGENDA: Oxagon takes centre stage at Neom
INDUSTRY REPORT:
MEED’s 2026 power developer ranking
> Regional power market diversifies
> Battery storage broadens IPP market> POWER: AI is creating a grid capacity problem
> LEGAL: What IFAD’s wind-down means for Gulf commodity markets
> OIL: Oil companies focus on North Africa amid Hormuz crisis
> LEADERSHIP: The future city does not need to hang above the ground
> SAUDI ARABIA MARKET FOCUS:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shift> MEED COMMENTS:
> Dubai Inc steps in as developers turn cautious
> Saudi Arabia redirects towards AI
> Kuwait plans biggest oil and gas contract award in 10 years
> Saudi Arabia battery storage awards provide fresh lift> GULF PROJECTS INDEX: Saudi Arabia and UAE lead Gulf index gains
> AUGUST 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: The boomers’ last act
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20134595/main.gif -
Aramco receives interest for major gas processing plant
30 September 2026
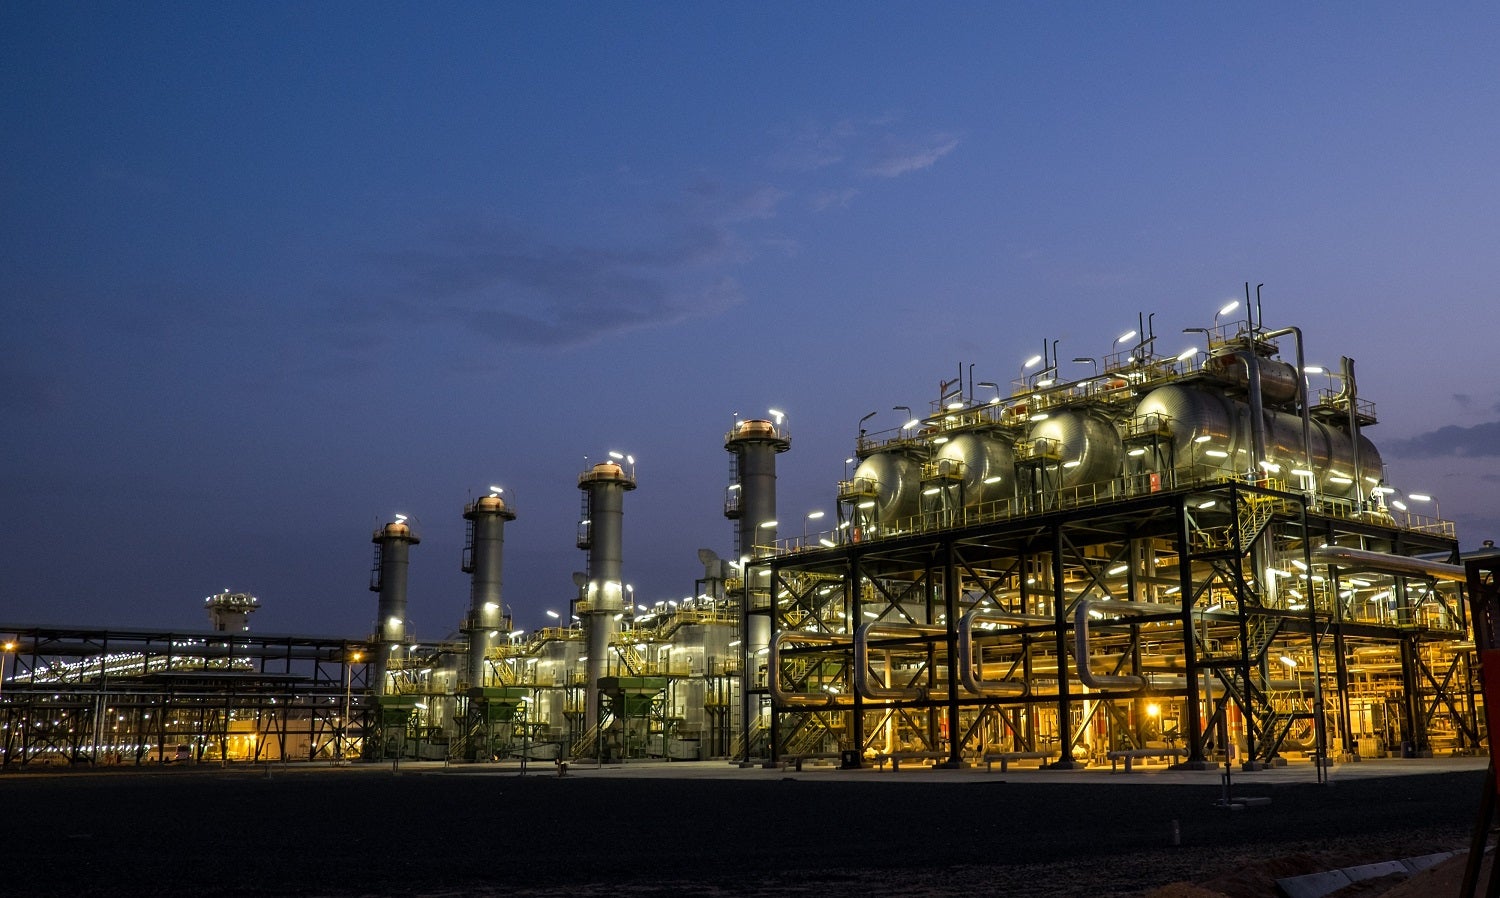
Saudi Aramco has received expressions of interest from contractors to participate in the main tendering exercise for a project to expand the Alhada gas processing plant, located about 85 kilometres northwest of Jubail in Saudi Arabia’s Eastern Province.
The Alhada gas processing plant expansion is critical to Aramco’s goal of increasing gas production capacity by 80% by 2030 from a 2021 baseline.
Aramco issued a solicitation of interest document for the main tendering exercise in early September, with contractors submitting responses by 17 September, sources told MEED.
The engineering, procurement and construction (EPC) scope of work has been divided into three main packages, sources said.
The first EPC package relates to the main gas treatment facilities, primarily three processing trains, along with:
- Three acid gas removal units
- Triethylene glycol (TEG) dehydration unit
- Two high-pressure and two low-pressure flares
- Two flare gas recovery units
- Two T&l flares
- Two burn pits
- A digital twin
The acid gas removal units will treat sour gas by removing hydrogen sulphide and carbon dioxide to produce sales gas, as well as acid-gas feed for the downstream acid gas enrichment unit and sulphur recovery unit.
The acid gas removal units will also process gas from the flare gas recovery units through a dedicated amine contactor to meet specifications for use as fuel gas. The TEG dehydration unit will then remove water from the treated gas to meet sales-gas specifications.
The project’s second EPC package covers the sulphur recovery units. The third package involves inlet channels for monoethylene glycol, as well as common utilities and supporting structures.
ALSO READ: Contractors express interest in sixth Jafurah expansion phase
https://image.digitalinsightresearch.in/uploads/NewsArticle/20127671/main4900.jpg -
Libya refinery expected to be worth more than $600m
30 September 2026
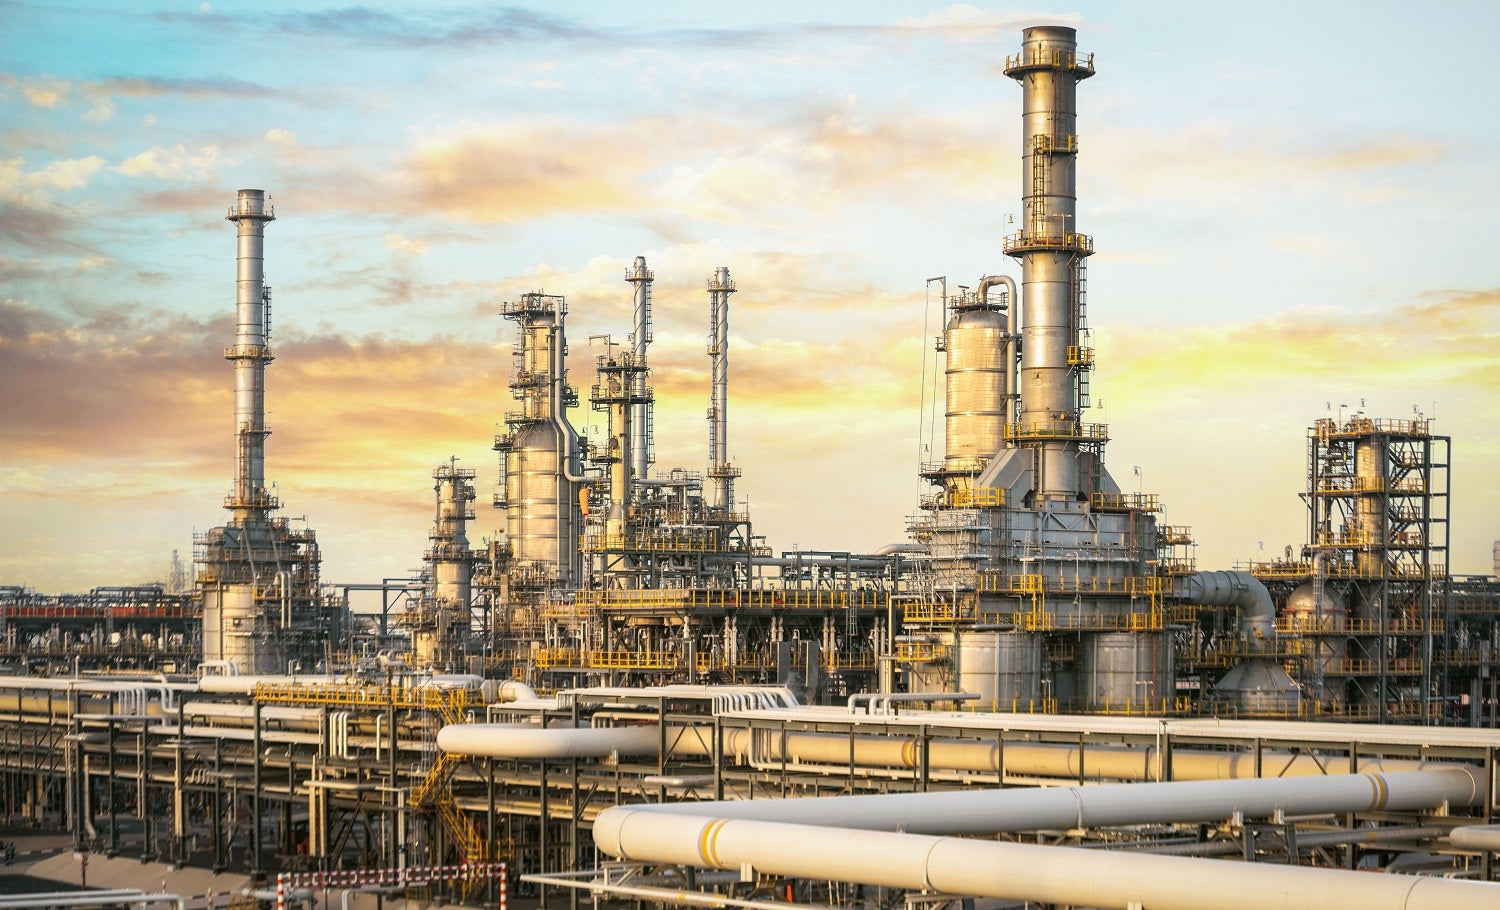
The main contract for Libya’s planned South Refinery project is expected to be worth more than $600m, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year. The main contract is expected to be procured under an engineering, procurement and construction (EPC) model.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20124329/main.jpg -
Joint venture wins $230m Ras El-Hekma buildings
30 September 2026
A joint venture of UK-based Innovo Build and Egypt’s Redcon Construction has won a contract worth about E£12bn ($230m) to carry out infrastructure and construction works for the DP03 East package of the Wadi Yemm development at Ras El-Hekma on Egypt’s North Coast.
Wadi Yemm is being developed by the UAE’s Modon Development as the first phase of its Ras El-Hekma masterplan, which will comprise 17 planned districts.
DP03 East has a built-up area of 323,000 square metres and is scheduled for completion within 21 months.
The scope of work includes more than 660 residential units – comprising standalone villas and townhouses – as well as public service areas, lakes, a commercial mall, landscaping and roadworks.
The delivery of units at Wadi Yemm is expected to begin in the third quarter of 2029.
Ras El-Hekma is located on a spur of land on Egypt’s northern Mediterranean coast, about 240 kilometres west of Alexandria.
Abu Dhabi-based holding company ADQ appointed Modon Holding as master developer for the Ras El-Hekma project in 2024. Modon will oversee the overall development, which covers more than 170 million square metres (sq m).
Modon will develop the first phase, covering 50 million sq m. The remaining 120 million sq m will be developed in partnership with private developers, under the supervision of the recently established ADQ subsidiary Ras El-Hekma Urban Development Project Company and Modon.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20123189/main.jpg -
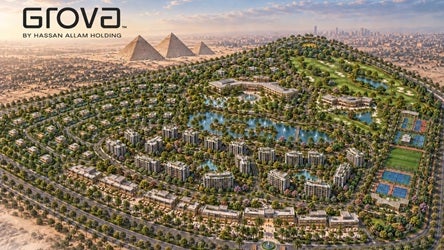 Hassan Allam wins $1bn Cairo mixed-use project deal
30 September 2026
Register for MEED’s 14-day trial access
Grova Developments, the real estate development arm of Egypt’s Hassan Allam Holding, has awarded Hassan Allam Construction a $1bn contract to deliver the Grova Westfields project in West Cairo.
Hassan Allam Construction’s scope of work includes a 150-key five-star hotel, branded residences, luxury villas and apartments, as well as infrastructure and landscaping works.
The project spans about 1.2 million square metres and is being developed in partnership with the Egyptian Kuwaiti Company for Real Estate Development.
Broadway Malyan has been appointed to lead the master planning and architectural design.
In October last year, Hassan Allam Construction announced that it had won a $550m contract to build another mixed-use development spanning more than 128 hectares in New Cairo.
That development comprises villas, townhouses, commercial and office space, mixed-use buildings, infrastructure and other associated facilities.
Hassan Allam Properties is co-developing the project with Grova Developments.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20123048/main.jpeg