Mena economies living dangerously
27 December 2023

 Gaza conflict puts the region on edge once again
Middle East and North Africa (Mena) economies enter 2024 in a state of flux. While most are well placed to continue their post-pandemic growth trajectory, albeit in the context of weaker oil sector growth, some states – Egypt and Tunisia notable among them — are under pressure to undertake painful reforms in order to elicit IMF funding packages.
Overall, hopes are high that growth in the Mena region will at least outpace the sluggish performance of the past year. Policymakers across the region will also be looking to double down on the private sector dynamism that saw non-oil growth outpace hydrocarbons performances in 2023.
The overall rear-view mirror is not especially encouraging. The IMF’s Regional Economic Outlook has Mena real GDP slowing to 2 per cent in 2023 from 5.6 per cent in 2022, a decline attributed to the impact of lower oil production among exporters and tighter monetary policy conditions in the region’s emerging market and middle-income economies. Geopolitical tensions – not least the Gaza conflict – and natural disasters in Morocco and Libya have also weighed on regional economies.
GDP growth
The World Bank estimates that in per capita terms, GDP growth across the region decreased from 4.3 per cent in 2022 to just 0.4 per cent in 2023. By the end of 2023, it says, only eight of 15 Mena economies will have returned to pre-pandemic real GDP per capita levels.
Much hinges on developments in the oil market. The Opec+ decision on 30 November to agree voluntary output reductions that will extend Saudi and Russian cuts of 1.3 million barrels a day (b/d), is designed to shore up prices, but it will come at a cost.
Saudi Arabia’s GDP data for the third quarter of 2023 revealed the full impact of output restraint, as the economy contracted at its fastest rate since the pandemic. Saudi GDP notably declined by 3.9 per cent in the third quarter compared to the previous quarter – after the kingdom implemented an additional voluntary 1 million b/d oil output cut.
As a whole, GCC economic growth has been tepid, despite a resurgence in services hotspots such as the UAE, where retail and hospitality sectors have boomed. The World Bank’s Gulf Economic Update report, published in late November, sees GCC growth at just 1 per cent in 2023, although this is expected to rise to 3.6 per cent in 2024.
Oil sector activity is expected to contract by 3.9 per cent in 2024 as a result of the recurrent Opec+ production cuts and global economic slowdown, according to Capital Economics. However, weaker oil sector activity will be compensated for by non-oil sectors, where growth is projected at a relatively healthy 3.9 per cent in 2024, supported by sustained private consumption, strategic fixed investments and accommodative fiscal policy.
“There has not been much GDP growth this year, but the non-oil economy has been surprisingly robust and resilient, despite the fact that the liquidity has not been as much of a driver as it was a year earlier,” says Jarmo Kotilaine, a regional economic expert.
“Of course, the cost of capital has gone up and there have been some liquidity constraints. But we do have a lot of momentum in the non-oil economy.”
In Saudi Arabia, beyond its robust real estate story, the ventures implemented under the national investment strategy are unfolding and semi-sovereign funds are playing a key role in ensuring continuity. “You are seeing more of these green energy projects across the region. It really has been a surprisingly positive story for the non-oil economy,” says Kotilaine.
Government spending
Fiscal policy will remain loose, at least among Mena oil exporters, whose revenues endow them with greater fiscal fire-power.
Saudi Arabia’s 2024 pre-budget statement bakes in further budget deficits, with government spending for 2023 and 2024 expected to be 34 per cent and 32 per cent higher, respectively, than the finance ministry had projected in the 2022 budget. This is not just higher spending on health, education and social welfare, but also marked increases in capital expenditure, including on the kingdom’s gigapojects.
That luxury is not open to the likes of Bahrain and Oman, the former recording the highest public debt-to-GDP ratio in the region at 125 per cent in 2023. Those two Gulf states will need to maintain a closer watch on their fiscal positions in 2024.
There are broader changes to fiscal policy taking place in the Gulf states, notes Kotilaine, some of which will be registered in 2024. “There are areas that the government will play a role in, but in a much more selective and focused manner. Much less of the overall story now hinges on government spending than it used to in the GCC,” he says.
For 2024, a consensus is emerging that the Mena region should see GDP growth of above 3 per cent. That is better than 2023, but well below the previous year and, warns the IMF, insufficient to be strong or inclusive enough to create jobs for the 100 million Arab youth who will reach working age in the next 10 years.
The Mena region’s non-oil buoyancy at least offers hope that diversification will deliver more benefits to regional populations, reflecting the impact of structural reforms designed to improve the investment environment and make labour markets more flexible.
“The labour market in the region continues to strengthen, with business confidence and hiring activity reverting to pre-pandemic levels,” says Safaa el-Tayeb el-Kogali, World Bank country director for the GCC. “In Saudi Arabia, private sector workforce has grown steadily, reaching 2.6 million in early 2023. This expansion coincides with overall increases in labour force participation, employment-to-population ratio, and a decrease in unemployment.”
El-Kogali adds that non-oil exports across the GCC region continue to lag, however. “While the substantial improvement in the external balances of the GCC over the past years is attributed to the exports of the oil sector, few countries in the region have also shown progress in non-oil merchandise exports. This requires close attention by policymakers to further diversify their exports portfolio by further promoting private sector development and competitiveness.”
Regional trade
There is a broader reshaping of the Gulf’s international trading and political relations, shifting away from close ties with the West to a broader alignment that includes Asian economies. The entry of Saudi Arabia, the UAE and Iran to the Brics group of emerging market nations, taking effect in 2024, is a sign of this process.
The decision of the Saudi central bank and People’s Bank of China in November 2023 to agree a local-currency swap deal worth about $7bn underscores the kingdom’s reduced reliance on the Western financial system and a greater openness to facilitating more Chinese investment.
“You want to be as multi-directional, as multi-modal as you can,” says Kotilaine. “For the Gulf states, it is almost like they are trying to transcend the old bloc politics. It is not about who your best friend is. They want to think of this in terms of a non-zero sum game, and that worked very well for them during the global financial crisis when they had to pivot from the West to the East.”
Near-term challenges
While long-term strategic repositioning will influence Mena economic policy-making in 2024, there will be near-term issues to grapple with. High up that list is the Gaza conflict, the wider regional impacts of which are still unknown.
Most current baseline forecasts do not envisage a wider regional escalation, limiting the conflict’s impacts on regional economies. The initial spike in oil prices following the 7 October attacks dissipated fairly quickly.
Egypt is the most exposed to a worsening of the situation in Gaza, sharing a land border with the territory. However, the Gaza crisis is not the only challenge facing the North African country
Elections set for 10 December will grant President Abdelfattah al-Sisi another term in office, but his in-tray is bulging under a host of economic pressures.
Inflation peaked at 41 per cent in June 2023. A currency devaluation is being urged, as a more flexible pound would offer a better chance of attracting much-needed capital inflows.
The corollary is that it would have to be accompanied by an interest rate hike. Capital Economics sees a 200 basis point increase to 21.25 per cent as the most likely outcome, ratcheting up the pain on Egyptian businesses and households.
A deal with the IMF would do much to settle Egyptian nerves, with a rescue plan worth $5bn understood to be in the offing. But Egypt has to do more to convince the fund that it is prepared to undertake meaningful fiscal reforms. Privatisations of state assets, including Egypt Aluminum, will help.
Other Mena economies will enjoy more leeway to chart their own economic path in 2024. Iraq has achieved greater political stability over the past year, and may stand a better chance of reforming its economy, although weaker oil prices will limit the heavily hydrocarbons-dominated economy’s room for manoeuvre.
Jordan is another Mena economy that has managed to tame inflation. Like Egypt, however, the country is also heavily exposed to what happens in Gaza.
Few could have predicted the bloody events that followed the 7 October attacks. Mena region economic strategists will be hoping that 2024 will not bring further surprises.
|
Can the Gulf build back better? The GCC has done much to put itself on the global map through effective reputation building. But, notes regional economic expert Jarmo Kotilaine, the focus of policy will now have to change from building more to building better, making the existing infrastructure and systems operate with greater efficiency. Above all, the region will need dynamic and adaptable companies and an economically engaged workforce. “The reality is the GCC has a lot of capital committed to the old economy. There is the question of how much of that should be upgraded, or made to work better, because fundamentally, one of the region’s big challenges is that local economies have very low levels of productivity.” It is by upgrading what the GCC has, by incorporating technology and energy efficiency, that the region can make productivity growth a driver, he tells MEED. “One area where GCC economies have started to make progress is in services: logistics, tourism, financial services. This is bringing money to the region,” he says. “We are also starting to see new potential export streams with things like green energy, and obviously green hydrogen. But the Gulf states have to manufacture more, and they have to manufacture better.” |

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
-
 Sultan Al-Jaber appeals for global energy security reset
2 November 2026
-
 Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
-
 Contractors prepare bids for Morocco power line
2 November 2026
-
 Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
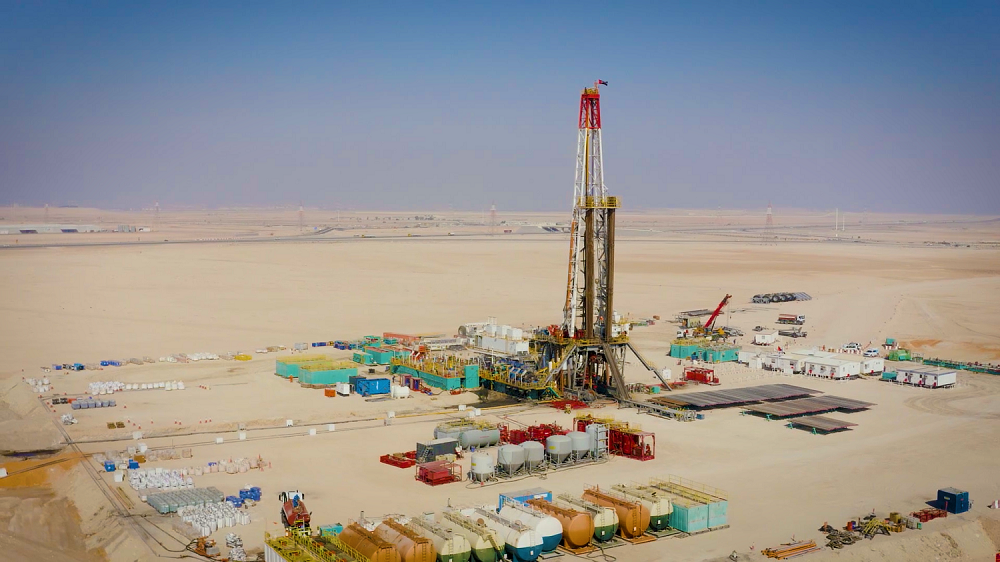
Abu Dhabi National Oil Company (Adnoc) has taken the final investment decision (FID) for the Ruwais Diyab unconventional gas development in Abu Dhabi.
The project will deliver 345 million standard cubic feet a day (scf/d) of raw gas from 2029 over a 25-year period, with the potential to reach up to 1 billion scf/d in the future.
Gas will be processed on site and connected to the UAE’s gas network through new pipeline infrastructure, “strengthening domestic supply, supporting the nation’s economic and industrial growth as well as Adnoc’s liquefied natural gas export ambitions”, the Abu Dhabi energy giant said when announcing FID on the project at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026.
According to sources, Adnoc has awarded the design, build and operate (DBO) contract for the Ruwais Diyab unconventional gas development to China-based Jereh Group.
A formal kick-off meeting between Adnoc and Jereh is expected to take place later in November, sources told MEED.
The DBO contract awarded by Adnoc to Jereh is understood to cover the second phase of the Ruwais Diyab unconventional gas development. The tendering exercise for the project started last year.
“The development [of Ruwais Diyab] follows a disciplined programme of technical studies, field testing and subsurface analysis, delivered by Adnoc Onshore under a DBO model, to reduce development risk,” Adnoc said in its statement on 2 November.
“It brings together advanced subsurface expertise, artificial intelligence-enabled drilling and completion technologies and integrated project delivery capabilities to support the efficient and responsible development of domestic gas resources,” it added.
The UAE holds the seventh-largest gas reserves in the world, with 298 trillion standard cubic feet (scf) of conventional gas reserves and 160 trillion scf of unconventional gas resources.
Adnoc holds the majority 60% stake in the Ruwais Diyab concession, the majority of which is situated onshore, while France’s TotalEnergies holds the other 40% interest.
The agreement to explore, appraise and develop the area’s unconventional gas resources was signed by Adnoc and TotalEnergies in November 2018. The partners announced first gas output at the concession, presumably on a pilot basis, two years later.
Adnoc has set a target of producing 1 billion scf/d of gas from the Ruwais Diyab concession by 2030, in line with its target to achieve self-sufficiency in overall gas production by the end of this decade.
“Ruwais Diyab’s additional unconventional gas supply will strengthen Adnoc’s gas value chain, including Adnoc Gas’s ability to meet rising domestic and international customer demand,” Adnoc said in its 2 November statement.
“Ruwais Diyab advances Adnoc’s ambition to establish a scalable unconventional gas business and create a platform for future growth,” the company added.
Ruwais Diyab first phase
Adnoc awarded the contract for engineering, procurement and construction (EPC) on the first phase of the unconventional gas development programme to local contractor Astra Engineering & Construction in early 2025, according to regional project tracker MEED Projects.
The first phase aims to achieve a gas output level of 100 million scf/d. The main structures to be built in the first phase include a central processing facility, two well pads, interconnecting well fluid pipelines, gas export pipelines and tie-in stations.
The EPC contractor will be required to provide services such as surveying, design, engineering, procurement, expediting, transportation, fabrication, construction, testing, installation, pre-commissioning, commissioning, site performance testing, operation and maintenance of all units.
The duration of the EPC works is understood to be 20 months, with the contractor also responsible for operating and maintaining the phase one facilities for 15 years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21100974/main4351.png -
Sultan Al-Jaber appeals for global energy security reset
2 November 2026
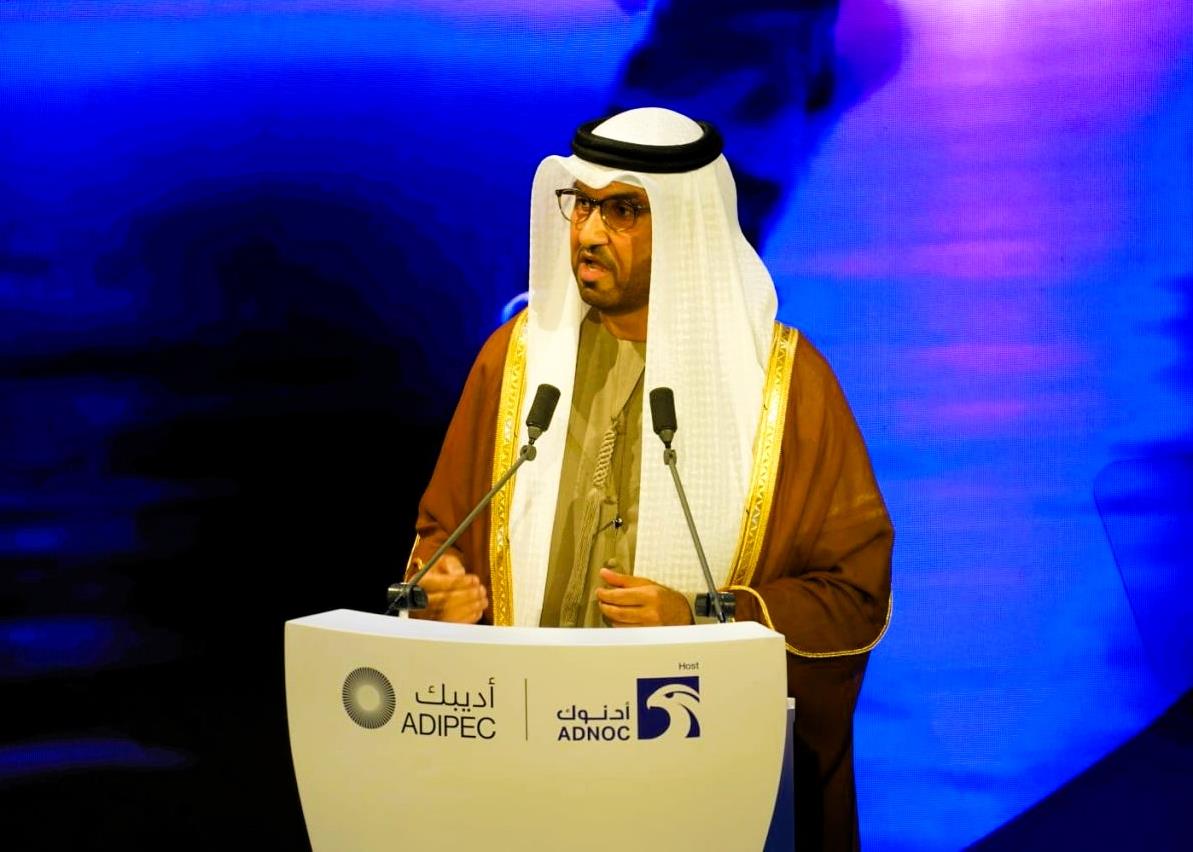
The global energy industry must fundamentally rethink how it builds, protects and delivers secure energy, following a year of unprecedented disruption that has exposed critical vulnerabilities in international supply chains, Sultan Ahmed Al-Jaber, the UAE’s Industry & Advanced Technology Minister and managing director and group CEO of Abu Dhabi National Oil Company (Adnoc Group) has said.
Delivering the opening address at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026 on 2 November, Al-Jaber said preparedness is essential to navigating an increasingly uncertain global landscape.
“For decades, energy security was a question for specialists. It was debated in rooms like this, by people like us, in a language that few needed to learn. This year, every family, every farmer, every industry and every business owner is asking about it, and our collective job is to find the answers.”
Noting that it is not possible to control every situation and remove every risk, Al-Jaber said: “The choices we make today will determine the energy landscape a decade from now. Let’s apply the lessons we have learnt. Let’s build capacity and everything that supports it. Let’s forge partnerships that hold when it matters. And if you want a partner you can count on, you are in the right room, in the right city, in the right country. Because when it counts the most, you can count on the UAE.”
Setting out the case for a more resilient energy system, Al-Jaber said that since the disruption in the Strait of Hormuz, nearly 1 billion barrels of crude have been drained from inventories. He noted that in some markets, stocks of diesel are at their lowest seasonal level in 35 years, while others are facing a supply gap for liquefied natural gas (LNG) of 600 billion cubic feet. “Simply put, the world has eroded its supply buffers,” Al-Jaber said.
“But supply is only half the story. The other half is delivery. Before the disruption, logistics were less than 5% of the cost of a barrel. Today, they are more than 30%. In short, energy security is not only measured at the point of production. It is now also measured at the point of delivery.”
Mitigation steps
Al-Jaber outlined five steps the energy industry can take to reduce the impact of future shocks. “First, accessible supply. We need expanded strategic storage, larger stockpiles of products and flexible refining capacity closer to consumer markets.
“Second, routes to market. Supply only counts when it arrives. Infrastructure must be built before it is needed and enabled by advanced logistics.
“Third, operational intelligence. Moving from automated operations to intelligent energy systems that anticipate risk, optimise performance and drive down the cost of every barrel.
“Fourth, capital follows confidence. Policy must create it, finance must accelerate it and insurance must keep trade moving.
“Fifth, which is in my view the most important, is people. Because behind every barrel that arrives is a person who made sure it did. Systems don’t carry responsibility, people do.”
Photo credit: Adipec via LinkedIn
https://image.digitalinsightresearch.in/uploads/NewsArticle/21091189/main2954.jpeg -
Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
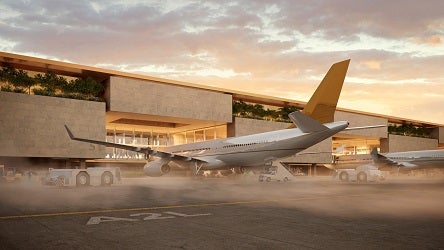
Contractors are preparing bids for the main construction contract for Terminal 6 at King Salman International airport (KSIA) in Riyadh.
MEED understands that the consortiums have been given until 30 December to submit their proposals.
The participating consortiums are:
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
Last month, MEED exclusively reported that contractor teams have completed the early contractor involvement phase of the project.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
King Salman International Airport Development Company (KSIADC) is a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May 2025, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21087339/main.jpg -
Contractors prepare bids for Morocco power line
2 November 2026
Contractors are preparing bids for a 160-kilometre (km), 400kV transmission line linking Guercif and Fes East in Morocco, following a site visit on 1 October.
The project is being developed by the Office National de l'Electricite et de l'Eau Potable (Onee) to connect the Saka solar photovoltaic power plant to the national electricity grid.
According to sources, at least eight contractors attended the site visit last month, including:
- Butec (Lebanon)
- CEEC Northeast Electric No.2 (China)
- Cegelec (France)
- EPME Electric (Morocco)
- Hideleco (Egypt)
- Kec International (India)
- PowerChina (China)
- Transrail (India)
The project comprises two lots. The first involves a 90km transmission line between Guercif and Taza, while the second covers a 70km section between Taza and Fes East.
The scope of work includes the construction of tower foundations, installation of transmission supports and conductors, and associated high-voltage equipment. It also includes optical fibre cables for communications and monitoring, access roads and other supporting infrastructure.
The tender was issued in September with bids originally due by 21 October. The deadline has now been extended to 25 November.
The project is part of a wider programme by Onee to expand Morocco's electricity transmission network and accommodate additional renewable energy capacity.
In June, the utility commissioned a 274km, 400kV transmission line linking Chemaia and Mediouna, near Casablanca.
Onee plans to expand its high- and extra-high-voltage transmission network from more than 30,700km to 37,000km by 2030.
In August, it approved a $26.4bn investment programme for the 2026-30 period, covering electricity and drinking water infrastructure.
The programme has allocated about $21.9bn to electricity projects and $4.5bn to drinking water infrastructure, with about 72% of the investment to be financed by the private sector, according to Onee.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083507/main1257.jpg -
Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
The onshore business of Abu Dhabi National Oil Company (Adnoc Onshore) has allowed contractors more time to prepare proposals for a project to tie in gas-producing and injection wells at the gas cap reservoirs of Abu Dhabi’s onshore Bab field.
The well tie-in scope, estimated to be worth more than $800m, forms part of Adnoc Group’s wider integrated Bab gas cap development programme.
The overall programme is being led and overseen by Adnoc Gas, another Adnoc Group subsidiary. Its central element is the construction of gas-processing infrastructure to handle incremental gas output expected from developing the Bab gas caps.
Adnoc Onshore issued the main tender for engineering, procurement and construction (EPC) works on the project in late September, MEED previously reported.
Contractors have been given until 16 November to submit technical bids for the project, according to sources. The previous deadline was 29 October.
MEED previously reported that Adnoc Onshore issued an expressions of interest (EoI) notice for the Bab gas production and injector well tie-in project on 13 May, with contractors submitting responses by 20 May.
The scope of work on the project covers the following:
- Tie-in of 99 new wells from Bab gas cap reservoirs KH-2, SH-1 and LK-1 (60 gas producers and 39 gas injectors);
- Installation of well gathering structures: 10 gas pads, six well bays and three virtual pads;
- Installation of a gas gathering network and a gas injection network;
- Rerouting of the LK-3 production from the existing trunkline in Remote Manifold Station 3 (RMS-3) to the project’s production trunkline, Bab Gas TL-2;
- Demolition of the existing 10-inch trunkline from RMS-3 to onshore gas development phase one.
In the EoI document, Adnoc Onshore said it intends to award the EPC contract in the last quarter of the year, with a 45-month duration of works.
Bab gas cap project infrastructure
As part of its 2030 upstream production increase goals, Adnoc Group is working to extract gas from four underdeveloped gas cap reservoirs at the Bab onshore field development – Thammama A, Thammama B, Thammama F and Thammama H.
While the Thammama A, B and H reservoirs are estimated to collectively produce 1.45 billion cubic feet a day (cf/d) of gas, output from the Thammama F gas cap is expected to be at a rate of 396 million cf/d.
Existing trains at the Habshan processing complex in Abu Dhabi will be unable to handle the new gas volumes. Therefore, Adnoc Gas is required to build new facilities to process an additional volume of up to 1.85 billion cf/d of raw gas.
Adnoc Gas is planning to build a gas processing plant in the Bab area, about 170 kilometres from Abu Dhabi, along with associated pipeline networks and other ancillary units, as part of the broader Bab gas cap development project. It has divided the EPC scope of work on the project into four packages:
- EPC package 1 – Main Bab gas cap plant
- EPC package 2 – Early civil works
- EPC package 3 – Pipelines
- EPC package 4 – Non-process area works
Abu Dhabi Securities Exchange-listed Adnoc Gas issued the tender for the main Bab gas cap plant on 25 June and set an initial deadline of 17 July for contractors to submit technical bids. The company then extended the technical bid submission deadline by four months, until 16 November, MEED previously reported.
Following a reshuffle of the consortiums gearing up to bid for the main Bab gas plant EPC package, estimated to be worth more than $6bn, the following teams have formed to compete in the main contract tendering round:
- Larsen & Toubro Energy Hydrocarbon (India) + Petrofac Emirates (UAE)
- Technip Energies (France) + JGC Corporation (Japan) + Sinopec (China)
- Tecnimont (Italy) + China Petroleum Engineering and Construction Corporation (CPECC)
The other three packages of the Bab gas cap project are also in the main contract tendering stages.
Prior to issuing the EoIs for the project packages, Adnoc Gas completed an early engagement process with contractors in September and October last year, as MEED previously reported.
In December last year, Adnoc Gas awarded the front-end engineering and design (feed) works for the development project to Australia-based consultancy Worley. The feed contract has a duration of more than 1.2 million man-hours, making it the largest-ever engineering job awarded by Adnoc Gas.
Bab Gas Cap concession
In addition to Adnoc Gas overseeing the main EPC tendering exercise for the gas processing plant, Abu Dhabi’s Supreme Council for Financial and Economic Affairs (SCFEA) awarded concession agreements in June for the development and production of the Bab gas cap reserve.
Adnoc will hold the majority 60% participating interest in the concession. The remaining stakes will be held by France’s TotalEnergies (10%), the UK’s BP (10%), China National Petroleum Corporation International (8%), Japan Oil Development Company Onshore (5%), China ZhenHua Oil (4%) and Korea GS E&P (3%).
According to the SCFEA, the Bab gas cap development and production concession represents the largest gas cap development project of its kind globally, the Abu Dhabi Media Office said in a report.
A gas cap refers to the free natural gas that sits above an underlying oil reservoir – in this case, the Bab onshore oil field in Abu Dhabi.
The project, operated by Adnoc Onshore, is expected to have a production capacity of approximately 1.5 billion cf/d of natural gas, equivalent to about 15% of Adnoc Gas’ total operational gas processing capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083343/main.jpg