Global LNG demand set for steady growth
30 August 2024

The low density of natural gas makes it costlier to contain and transport compared to other fossil fuels such as coal or crude oil.
For more than a century after gas was recognised as a viable energy source, producers were unable to utilise the fundamental infrastructure that facilitated international oil trade – marine transportation.
Prior to the development of liquefied natural gas (LNG) technology, the transportation of gas was limited to movement by pipeline. The development of LNG revolutionised the manner in which gas is transported and consumed worldwide.
The first experimental shipment of LNG was made from Lake Charles in the US state of Louisiana to Canvey Island in the UK in 1958, aboard the vessel the Methane Pioneer. Since then, with improvements in technology and cost efficiencies, LNG has become an internationally traded commodity, the demand for which has risen through the years.
 LNG production and transmission
LNG is natural gas that has been reduced to a liquid state by cooling it to a cryogenic temperature of -160 degrees Celsius. Natural gas is converted to a liquid in a liquefaction plant, or train.
Train sizes tend to be limited by the size of the available compressors. In the early years of development, train sizes had capacities of about 2 million tonnes a year (t/y), and a greenfield facility would often require three trains to be economically viable.
Improvements in compressor technology in this century have made it possible to design larger trains, to benefit from economies of scale. In the early 2000s, Qatar’s state-owned companies Qatargas and RasGas, in partnership with Western companies such as ExxonMobil and TotalEnergies (which was known as Total at the time), started operating trains with capacities of 7.8 million t/y.
When natural gas is in a liquid form, it takes up approximately one 600th of the space it would occupy as a vapour. Reducing its volume and its weight by half makes it easier and safer to transport across long distances on specially designed double-hull ships or vessels.
In the final stage of transmission, LNG is offloaded from a marine jetty to cryogenic storage tanks at the receiving terminal. It remains at -160 degrees Celsius during this process.
Benefits and applications
A slew of benefits and applications in various industries has fuelled the growth of LNG in the global economy.
LNG produces 40% less carbon dioxide than coal and 30% less than oil, therefore offering lower carbon emissions.
The LNG liquefaction process also releases very little nitrogen oxide, a harmful greenhouse gas, and sulphur dioxide, which can cause significant damage to terrestrial and atmospheric ecosystems.
With an energy density 600 times greater than natural gas, LNG can be used as an alternative fuel for sectors such as shipping. This helps to reduce the carbon footprint of industries that are slower to decarbonise.
On the socioeconomic front, LNG sales have facilitated the economic progress of producer nations, as witnessed in Australia, Qatar and Nigeria. Consumer countries also get access to a source of affordable and environmentally sustainable energy.
Separately, investments in LNG – in the form of LNG infrastructure building, as well as the expansion of production facilities – spur economic growth and help to stimulate job creation.
LNG is primarily used as a major source for electricity generation in powering industries, households and social infrastructure.
The chemicals industry is also one of the largest consumers of LNG, where it is mainly used for steam production and for heating, cracking and reforming units.
In the transport sector, meanwhile, LNG is one of the foremost sources of fuel, particularly for marine tankers and heavy surface vehicles, due to its high energy density compared to conventional fuels, coupled with its low emissions.
In addition, in food manufacturing, LNG is used as fuel for intense processes such as the steaming and drying of food produce.
 Buoyant demand outlook
According to Shell’s LNG Outlook 2024, the global demand for LNG is estimated to rise by more than 50% by 2040, as industrial coal-to-gas switching gathers pace in China, and as South and Southeast Asian countries use more LNG to support their economic growth.
Global trade in LNG reached 404 million tonnes in 2023, up from 397 million tonnes in 2022, with tight supplies of LNG constraining growth while maintaining prices and price volatility above historic averages.
Demand for natural gas has already peaked in some regions but continues to rise globally, with LNG demand expected to reach about 625-685 million t/y in 2040, according to the latest industry estimates.
“China is likely to dominate LNG demand growth this decade as its industry seeks to cut carbon emissions by switching from coal to gas,” says Steve Hill, executive vice president for Shell Energy, in the company’s LNG Outlook 2024.
“With China’s coal-based steel sector accounting for more emissions than the total emissions of the UK, Germany and Turkiye combined, gas has an essential role to play in tackling one of the world’s biggest sources of carbon emissions and local air pollution.”
Over the following decade, declining domestic gas production in parts of South and Southeast Asia could drive a surge in demand for LNG as these economies increasingly need fuel for gas-fired power plants or industry. However, these countries will need to make significant investments in their gas import infrastructure, Shell said in the report.
The Shell LNG Outlook 2024 also notes that gas complements wind and solar power in countries with high levels of renewables in their power generation mix, providing short-term flexibility and long-term security of supply.
Three stages of growth
UK-based consultancy Wood Mackenzie, in its global gas strategic planning outlook, identifies three distinct phases of LNG market growth in the coming decade.
First, it says that continued market volatility will remain for the next couple of years as limited supply growth amplifies risk.
The pace of LNG supply growth and demand across Europe and Asia provide both upside and downside risks. Uncertainty over Russian gas and LNG exports further complicates the matter, making 2025 a potentially tumultuous year for supply, and therefore for prices.
This phase could be followed by a major wave of new supply, ushering in lower prices from 2026, Wood Mackenzie says in the report.
A muted demand response to lower prices across Asia would undoubtedly draw out the market imbalance. Conversely, supply risks cannot be ruled out. An anticipated escalation of Western sanctions on Russian LNG threatens to impact the overall supply growth scenario, increasing the potential for a stronger-for-longer market.
Beyond 2026, as LNG supply growth slows, prices will recover again before a new wave of LNG supply triggers another cycle of low prices in the early 2030s, Wood Mackenzie predicts.
Much will depend on long-term Asian demand growth. Booming power demand and a shift away from coal makes gas and renewables the obvious choice.
However, if LNG prices are too high, Asia’s most price-sensitive buyers could quickly return to coal.
On the upside, delays or cancellations to the expansion of Central Asian and Russian pipeline gas into China will push Chinese LNG demand higher for longer.
 Region advances LNG projects with pace

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
-
 Contractors submit bids for Libya refinery
5 October 2026
-
 Dubai tenders sewage and stormwater projects
5 October 2026
-
 Arabian Drilling wins $533m contract for Neutral Zone rigs
2 October 2026
-
 QatarEnergy gives North Field West topside bidders more time
2 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Rabigh 2 IPP expansion secures $2.58bn financing
5 October 2026
Saudi Arabia's Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion has reached financial close.
In a disclosure to the Saudi Exchange, Acwa said it had secured SR9.69bn ($2.58bn) in long-term financing for the project, which has a generation capacity of 2,313.5MW.
In April, MEED reported that Acwa and Saudi Energy (formerly Saudi Electricity Company) had signed a 31-year power purchase agreement (PPA) with Saudi Arabia’s principal buyer, Saudi Power Procurement Company (SPPC), for the project.
The project involves the development of a combined-cycle gas turbine (CCGT) plant in the Mecca region. It is being developed by Al-Morjan Two Electricity Company, with Acwa and Saudi Energy each owning a 40% stake in the project.
The contract is valued at SR11.5bn ($3.07bn), the companies said in separate stock exchange filings at the time. The carbon-capture-ready power plant will be implemented under a build, own and operate contract.
The financing has a tenor of about 34 years and was provided by a consortium of local, regional and international lenders.
The lenders are:
- Abu Dhabi Commercial Bank
- Alinma Bank
- Boubyan Bank
- China Minsheng Banking Corporation, Hong Kong Branch
- Commercial Bank of Dubai
- HSBC Bank Middle East
- Industrial and Commercial Bank of China
- Industrial Bank, Beijing Branch
- National Bank of Greece, Cyprus
- Riyad Bank
- Saudi Awwal Bank
- Saudi National Bank
- Standard Chartered Bank, Taiwan
- Sumitomo Mitsui Trust Bank, London Branch
The project scope also includes financing and expansion of a 380kV electrical substation.
According to regional project tracker MEED Projects, construction works have commenced on the project and a joint venture of Egypt's Elsewedy Electric and China's Sinohydro has been working as the main contractor.
Rabigh 1 extension
In January, Saudi Energy announced a spearate energy conversion agreement with SPPC for the purchase of electricity from the Rabigh 1 power plant expansion.
The contract is valued at SR5.33bn ($1.42bn).
It covers the development, financing, construction, ownership and operation of the gas-fired power plant, which will have a generation capacity of 1,179MW.
A joint venture of Elsewedy Electric and Germany’s Siemens Energy is undertaking the engineering, procurement and construction work for the project, which is expected to be completed by the end of 2026.
US/India-based Synergy Consulting is the financial advisory consultant to Saudi Energy on this project.
Acwa also recently started initial commercial operations at the Taiba 1 and Qassim 1 combined-cycle gas turbine (CCGT) power plants, as reported by MEED.
The plants have a combined generation capacity of about 3.8GW and are two of four projects procured under the first round of Saudi Arabia’s gas-fired independent power producer (IPP) programme by Saudi Power Procurement Company.
A team of Saudi Energy, formerly Saudi Electricity Company, and Acwa won the contract to develop and operate the projects in 2023.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20270643/main.jpg -
Contractors submit bids for Libya refinery
5 October 2026
Bids have been submitted for the main contract for Libya’s planned South Refinery project and are currently under technical evaluation, according to industry sources.
The project, located in Ubari in southern Libya, has gained momentum over the past year, and the main contract is anticipated to be worth more than $600m.
The main contract is expected to use the engineering, procurement and construction (EPC) model.
The EPC work is expected to take 50 months, and the facility will be designed to process 30,000 barrels a day (b/d) of crude oil.
In March, US-based engineering company KBR was awarded a contract by Zallaf Exploration, Production & Refining of Oil & Gas Company to provide project management and technical services for the project.
Under the terms of the contract, KBR will provide contract management, project management and supporting technical services throughout the project’s EPC phases.
The refinery is expected to produce:
- Propane and butane for domestic and industrial uses
- Gasoline
- Kerosene
- Diesel
- Fuel oil
In March, KBR said that the project was aligned with its “long-standing commitment to advancing vital oil and gas infrastructure in Libya”.
Libya currently operates five main refineries with a combined nameplate capacity of 380,000 b/d, but actual throughput is closer to 180,000 b/d due to poor maintenance and damage from military clashes.
In addition to the South Refinery project, Libya also plans to upgrade the Zawiya refinery and carry out projects at the Serir, Brega, Tobruk and Ras Lanuf refineries.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20267178/main.jpg -
Dubai tenders sewage and stormwater projects
5 October 2026
Register for MEED’s 14-day trial access
Dubai Municipality has issued tenders for a 3,000-cubic-metre-a-day sewage treatment plant (STP) and a strategic stormwater drainage system.
The first tender is for the design and construction of the Al-Lissaily STP.
The project, identified as DS311/1, covers the design, supply, installation, construction and commissioning of the plant in the Al-Lissaily area.
Dubai Municipality’s Sewerage and Recycled Water Projects Department is issuing the tender. The bid submission deadline is 29 October.
The facility is located near residential communities and farming areas. The project will therefore include measures for odour control, treated effluent quality, noise mitigation and environmental performance.
The municipality said the plant will incorporate landscaping and architectural features designed to reflect Dubai’s heritage character and the surrounding farming environment.
The second tender is for project TF-07-C1, a strategic stormwater drainage system covering more than 100 million square metres.
The project area extends from Sheikh Mohammed Bin Zayed Road (E311) to the north to Emirates Road (E611) to the south, and from Expo Road in the west to Dubailand in the east.
The project will provide stormwater infrastructure and service connections for more than 20 private developers, as well as the Al-Yalayis 5 community.
It will also support major roads in the Jebel Ali area, including Sheikh Mohammed Bin Zayed Road, Emirates Road, Sheikh Zayed Road, Sheikh Zayed Bin Hamdan Al-Nahyan Road, Hessa Street, Al-Yalayis Road and Al-Fay Road.
The scope includes a major stormwater gravity drainage system, with pipeline diameters of up to 3,000mm.
Dubai Municipality said the project is intended to increase drainage capacity, improve relief for existing and new stormwater systems, and strengthen protection against extreme rainfall events.
The bid submission deadline is 22 October.
The municipality also recently invited contractors to bid for a contract to upgrade and rehabilitate the stormwater system in Abu Hail.
The project comprises a stormwater pumping station with a total discharge capacity of 26 cubic metres a second. It is estimated to cost up to $163m.
Bid submissions are due by 15 October.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20266881/main.jpg -
Arabian Drilling wins $533m contract for Neutral Zone rigs
2 October 2026
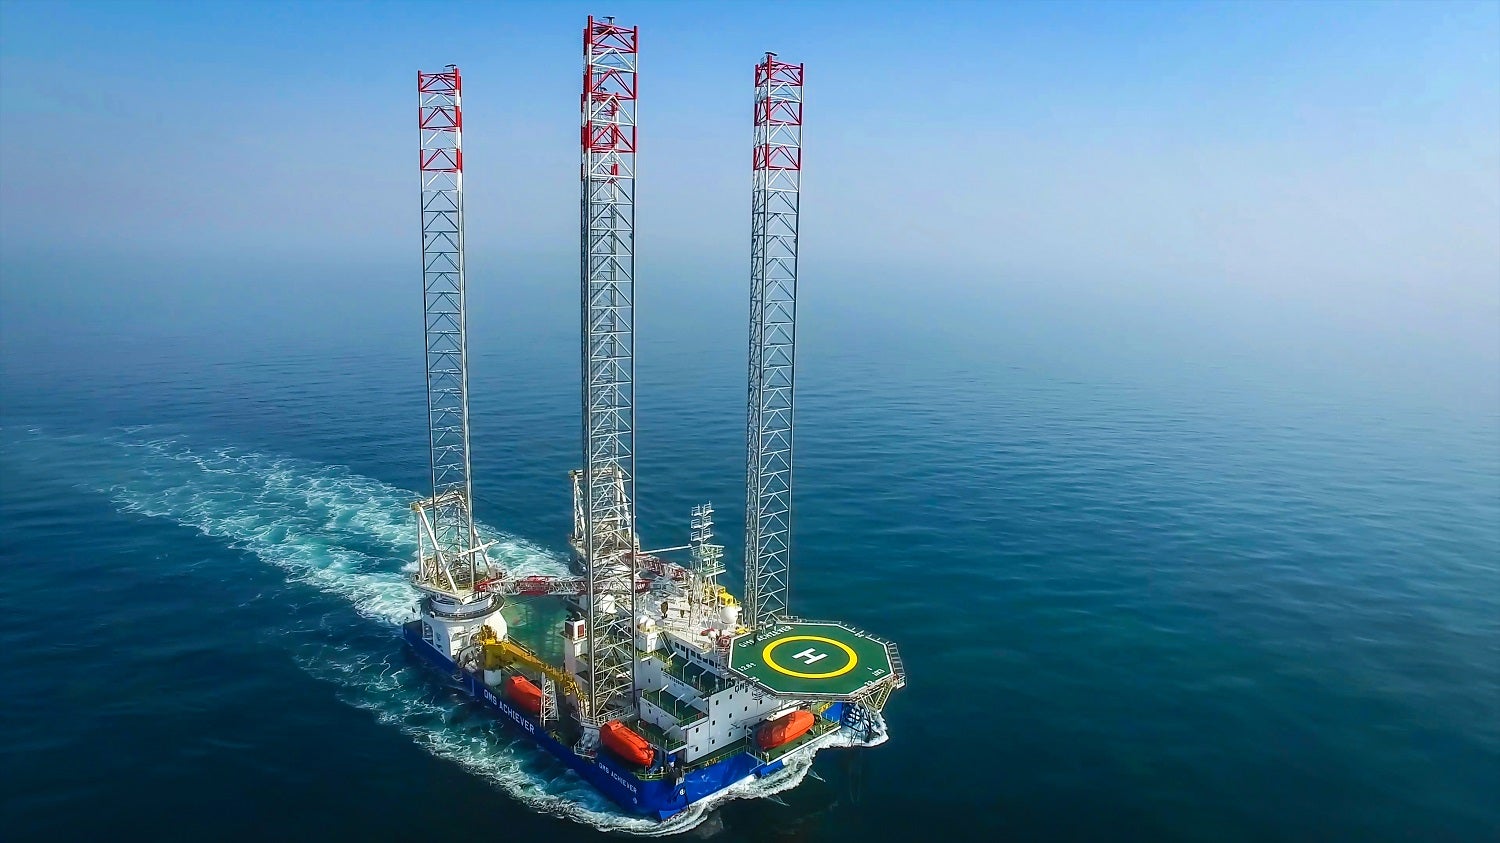
Saudi Arabia-based Arabian Drilling has announced that it has won a four-year contract from Al-Khafji Joint Operations (KJO) to provide four high-specification offshore jack-up drilling rigs to support KJO’s offshore drilling operations in its concession area in the Saudi-Kuwait Neutral Zone.
The contract is valued at approximately SR2bn ($533.33m) and “will contribute to the company’s revenues and financial results commencing at the end of the fourth quarter of 2026”, Arabian Drilling said in a statement.
Following the award, Arabian Drilling’s total backlog will increase to approximately SR18bn ($4.8bn), “providing enhanced revenue visibility and supporting the company’s long-term growth strategy”, the Saudi Exchange (Tadawul)-listed company said.
KJO is jointly owned by Saudi Aramco subsidiary Aramco Gulf Operations Company and Kuwait Petroleum Corporation subsidiary Kuwait Gulf Oil Company.
Saudi Arabia and Kuwait have been producing oil from the Neutral Zone – primarily from the onshore Wafra field and the offshore Khafji field – since at least the 1950s. With a growing need to increase natural gas production, they have been working to exploit the Dorra offshore field, understood to be the Neutral Zone’s only gas field.
Discovered in 1965, the Dorra gas field is estimated to hold 20 trillion cubic metres of gas and 310 million barrels of oil. The two countries have been pressing ahead with their plan to jointly produce 1 billion cubic feet a day of gas from the Dorra gas field through multibillion-dollar projects.
KJO divided the engineering, procurement and construction (EPC) scope of work for the Dorra field gas production project into four packages – three offshore and one onshore. It awarded contracts for all the EPC packages, worth approximately $6.5bn in total, in August.
ALSO READ: ADES completes acquisition of Saipem’s Saudi drilling business
https://image.digitalinsightresearch.in/uploads/NewsArticle/20215339/main5848.jpg -
QatarEnergy gives North Field West topside bidders more time
2 October 2026
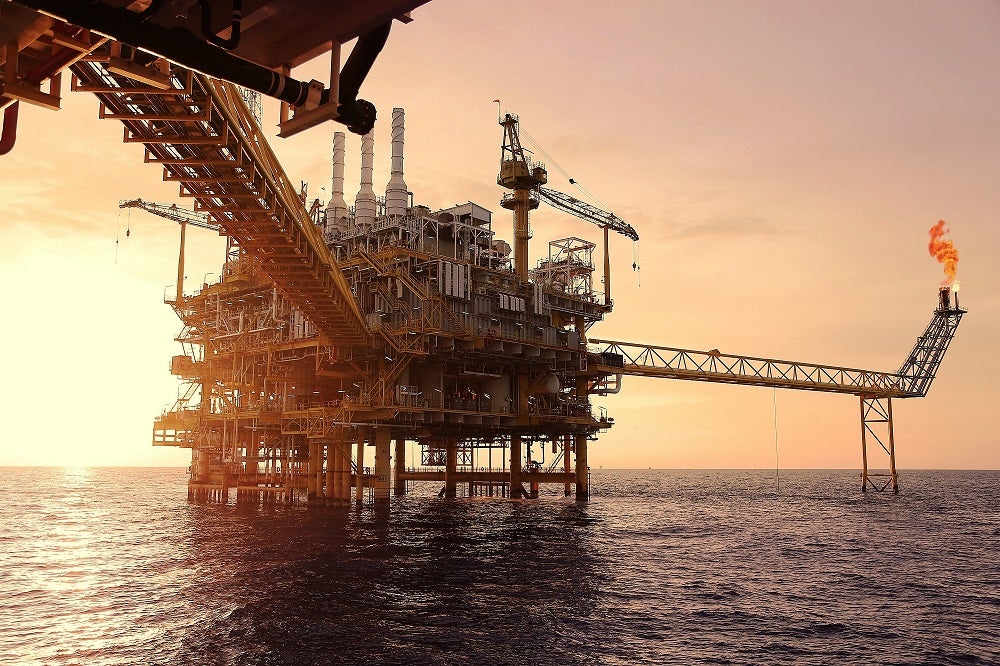
QatarEnergy has granted contractors more time to prepare bids for a tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors now have until 12 October to submit technical bids for the project, according to sources. Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The PDMs will increase gas production from North Field reservoirs and provide additional gas feedstock for the NFW liquefied natural gas (LNG) development.
The tender, issued earlier this year, forms part of the wider NFW project, the third and final phase of the state enterprise’s North Field LNG expansion programme.
The previous deadlines for technical bids were 30 August, 15 September and 28 September, while commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott a contract for the EPCI of four offshore jackets that will also support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20208200/main.jpg