World to add 5.5TW of renewables
9 October 2024
The world is set to add more than 5,500GW of new renewable energy capacity between 2024 and 2030, almost three times the increase between 2017 and 2023.
According to a new report by the Paris-based International Energy Agency (IEA), China will account for almost 60% of all renewable capacity installed worldwide between now and 2030, based on current market trends and today’s policy settings by governments.
The IEA Renewables 2024 report added: “That would make China home to almost half of the world’s total renewable power capacity by the end of this decade, up from a share of a third in 2010.”
However, while China is adding the biggest volumes of renewables, India is growing at the fastest rate among major economies.
In terms of technologies, solar photovoltaic (PV) alone is forecast to account for a massive 80% of the growth in global renewable capacity between now and 2030 – the result of the construction of new large solar power plants as well as an increase in rooftop solar installations by companies and households.
Despite ongoing challenges, the wind sector is also poised for a recovery, with the rate of expansion doubling between 2024 and 2030 compared with the period between 2017 and 2023.
As a result of these trends, the report cites that nearly 70 countries, collectively accounting for 80% of global renewable power capacity, are poised to reach or surpass their current renewable ambitions for 2030.
The report forecasts global capacity will reach 2.7 times its 2022 level by 2030, which still falls short of the target set by nearly 200 governments at the Cop28 climate change conference in December 2023 to triple the world’s renewable capacity this decade.
IEA analysis indicates that “fully meeting the tripling target is entirely possible if governments take near-term opportunities for action”.
This includes outlining bold plans in the next round of Nationally Determined Contributions under the Paris Agreement, due next year, and bolstering international cooperation on reducing high financing costs in emerging and developing economies, which are restraining renewables’ growth in high-potential regions such as Africa and Southeast Asia.
“Renewables are moving faster than national governments can set targets for. This is mainly driven not just by efforts to lower emissions or boost energy security – it’s increasingly because renewables today offer the cheapest option to add new power plants in almost all countries around the world,” said IEA executive director Fatih Birol.
“This report shows that the growth of renewables, especially solar, will transform electricity systems across the globe this decade.
“Between now and 2030, the world is on course to add more than 5,500 gigawatts of renewable power capacity – roughly equal to the current power capacity of China, the European Union, India and the United States combined. By 2030, we expect renewables to be meeting half of global electricity demand.”
Renewables are on course to generate almost half of global electricity by 2030, with the share of wind and solar PV doubling to 30%, according to the forecast.
Curtailing curtailment
However, the report emphasises the need for governments to ramp up their efforts to securely integrate variable renewable sources such as solar PV and wind into power systems.
Recently, rates of curtailment – where renewable electricity generation is not used – have been increasing substantially, reaching around 10% in several countries today.
The IEA suggests focusing on integration measures such as increasing power system flexibility to address this.
It added: “Making a concerted push to address policy uncertainties and streamline permitting processes – and to build and modernise 25 million kilometres of electricity grids and reach 1,500GW of storage capacity by 2030, as highlighted in previous IEA analysis – would enable even larger shares of generation from renewables.”
Renewable shares in consumption
Overall, led by the massive growth of renewable electricity, the share of renewables in final energy consumption is forecast to increase to nearly 20% by 2030, up from 13% in 2023.
Meanwhile, renewable fuels are lagging, underscoring the need for dedicated policy support to decarbonise sectors that are hard to electrify.
Meeting international climate goals would require not only accelerating the rollout of renewable power, but also significantly speeding up the adoption of sustainable biofuels, biogases, hydrogen and e-fuels, the report notes.
Since these fuels remain more expensive than their fossil counterparts, their share in global energy is set to stay below 6% in 2030.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 BP and PetroChina cut budgets for Iraq oil projects
5 November 2026
-
 Read the November 2026 MEED Business Review
4 November 2026
-
 UAE economy shows resilience
4 November 2026
-
 Kuwait appoints KPMG for ports strategic plan
4 November 2026
-
 Combined Group signs Kuwait upstream contract
4 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
BP and PetroChina cut budgets for Iraq oil projects
5 November 2026

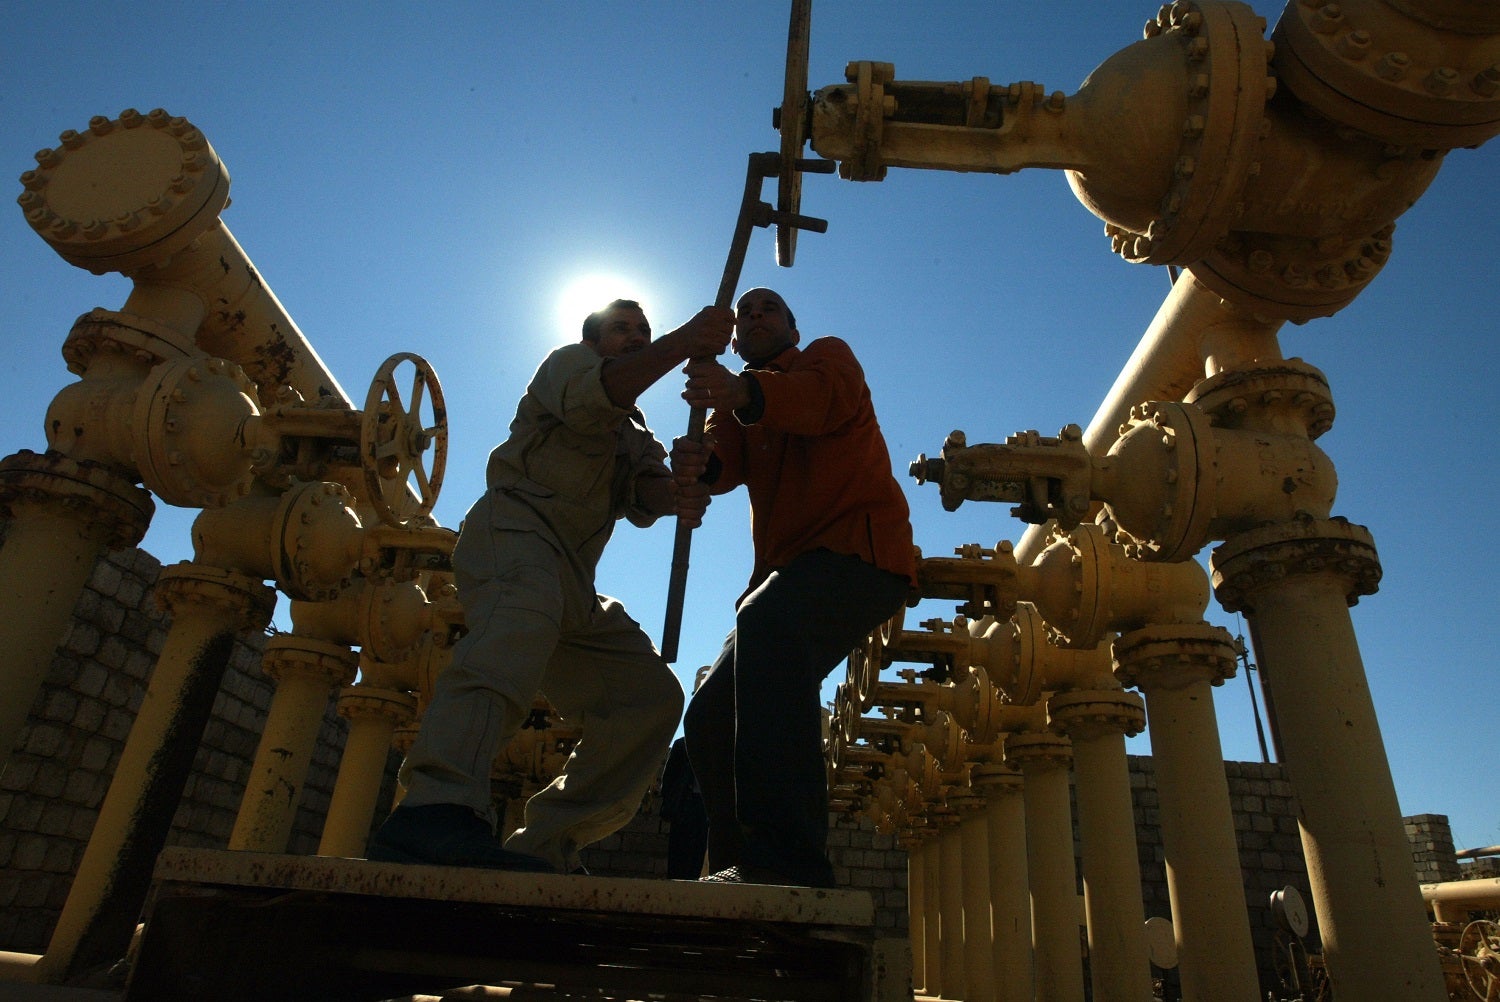
London-headquartered BP and PetroChina have agreed with Turkish contractor Tekfen to reduce the monthly allocated budgets for two upstream oil projects at the Rumaila field, according to industry sources.
Rumaila Operating Organisation (ROO) operates the Rumaila field.
ROO is a joint venture formed by state-owned Basra Oil Company; Iraq’s State Oil Marketing Organisation (Somo); and Basra Energy Company, a joint venture owned by UK-based oil company BP and PetroChina.
PetroChina is the listed arm of state-owned China National Petroleum Corporation.
As part of the agreement between ROO and Tekfen, progress on the projects will continue at a slower pace.
The two projects are both also suffering from delays due to problems importing equipment through the Strait of Hormuz, sources said.
One source said: “These projects are really barely alive. They are progressing very slowly after the monthly budgets were cut by the client. The project is still continuing, but at a slow pace. The budgets are very limited.”
Sources said that although the monthly budget payments were reduced, they were still being made on time.
Most of the problems that the projects at the oil field are facing are connected to the regional war, which started on 28 February when the US and Israel attacked Iran.
One source said: “The budget issues and financial problems are significant. There are also security concerns connected to reported US plans for a potential strategic nuclear strike on Iran and how that might impact operations at the Rumaila field, which is only around 60 kilometres from the Iranian border.”
The two projects have a combined value of less than $100m, and the project scopes include developing new facilities as well as upgrading and repairing existing upstream infrastructure.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21153848/main.jpg -
Read the November 2026 MEED Business Review
4 November 2026
Download / Subscribe / 14-day trial access The GCC projects market continues to show resilience against a deteriorating macroeconomic backdrop, with clients committing capital despite the regional fallout from the US-Iran conflict.
 According to the IMF, every GCC economy except Oman is projected to contract in 2026. Yet government-backed infrastructure spending has cushioned the blow, led by the UAE, where contract awards are up 6.1% year-on-year.
But beneath the headline figures, signs of a slowdown are emerging. Falling residential activity, a retreat in Saudi Arabia’s gigaproject spending and a sharp decline in tendering suggest that the market faces a tougher test as the conflict continues.
Read more in our November issue Agenda feature.
Our 22-page market focus on the UAE examines how state-backed capital, greater freedom to increase oil production following the UAE’s exit from Opec, and continued investment in energy, transport and water infrastructure are helping the country absorb the economic shock of the Iran conflict.
It also looks at how Abu Dhabi is adjusting its diplomatic approach, and the risks that remain for the wider economy.
This month’s industry report turns to project finance, examining how Gulf lenders are reassessing risk amid regional instability, higher costs and tighter credit limits. While infrastructure funding needs remain undiminished, the conflict is changing the way projects are financed, with lenders paying closer attention to physical security, insurance and risk allocation.
The report also examines the slowdown in public-private partnership activity across the Middle East and North Africa, where the value of awards has fallen sharply despite a pipeline of major deals still to come.
We also speak to WSP’s regional president Dean McGrail about the resilience of the Gulf construction market, the shift towards infrastructure investment and the opportunities emerging in aviation.
H&H chairman Shahab Lutfi discusses how the Dubai developer is pressing ahead with contract awards despite rising costs and softer sales, while the UAE Ministry of Energy & Infrastructure’s Mohammed Al-Mansoori explains how the country is strengthening supply-chain resilience and maintaining infrastructure delivery in the face of disruption.
Elsewhere, we examine the global stadium construction market, where annual spending is forecast to jump by 39% in 2027 as governments prepare for major sporting events, and look at the economic consequences of the Strait of Hormuz closure.
We hope our valued subscribers enjoy the November 2026 issue of MEED Business Review.
Must-read sections in the November 2026 issue of MEED Business Review include:
> AGENDA: GCC projects market holds its nerve
> INTERVIEW: Stability holds as project work continues
> INTERVIEW: H&H continues to deliver Dubai projects
INDUSTRY REPORT:
Project finance
> Project financiers hold the line
> PPP activity fades amid regional instability> INTERVIEW: Building resilience into infrastructure delivery
> STADIUMS: Stadium spending set to jump 39% in 2027
> REGIONAL CONFLICT: Hormuz closure wipes out growth in 2026
 > UAE MARKET FOCUS:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into production> MEED COMMENTS:
> Regional tensions strengthen the case for GCC rail
> Focus turns to the Northern Emirates
> Gulf data centre ambitions face delivery test
> Qatar buys LNG reliability beyond Hormuz> GULF PROJECTS INDEX: Saudi Arabia drives Gulf projects market higher
> SEPTEMBER 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: When football meets politics
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21089562/main.gif -
UAE economy shows resilience
4 November 2026
 Commentary
Colin Foreman
EditorState-backed capital is carrying the UAE projects market through the economic shock of the Iran conflict. Government and government-related entities have accounted for $22.4bn of the $34.6bn of contracts awarded in Dubai so far this year, almost two-thirds of the total, according to regional project tracker MEED Projects. Private developers have deferred new launches, and off-plan residential sales in the emirate fell from $9bn in February to $4bn in August.
In Abu Dhabi, state-affiliated developers and cultural agencies are accelerating destination projects on Yas and Saadiyat islands, including the $1.7bn Sphere Abu Dhabi venue.
The energy sector is adding momentum. The UAE’s exit from Opec in May has freed Abu Dhabi National Oil Company (Adnoc) to make greater use of its spare crude capacity, and the company is on course to exceed its 2024 upstream project spending this year. Adnoc Gas has awarded $8.2bn of contracts for the second and third phases of its rich gas development programme.
The $3bn Taweelah C combined-cycle gas turbine plant accounted for most of the $4.17bn of power contracts awarded by early September, while Dubai’s AED30bn ($8.1bn) Tasreef stormwater programme is driving water sector activity.
MEED Projects tracks $103bn of transport schemes at pre-execution stages, including rail links that would give exporters routes that avoid the Strait of Hormuz.
Non-oil activity is also holding up. The UAE purchasing managers’ index compiled by financial information and analytics provider S&P Global reached a 20-month high of 55.3 in September. Net profits at the 10 biggest UAE banks rose 7% to AED47.8bn ($13bn) in the first half, supported by loan growth of 21%.
Meanwhile, Abu Dhabi is repairing relations with Riyadh after a year of friction over Yemen and Sudan. On 8 October, the two countries signed a memorandum of understanding covering power grid interconnection and freight rail.
Risks remain. The Washington-based IMF expects the GCC economy to contract by 3.8% this year, with recovery dependent on shipping through Hormuz returning to normal. US scrutiny of Iran-linked transactions is also tightening compliance demands on UAE banks. That said, there are reasons to be hopeful. The IMF expects the economy to rebound in 2027 with 7.7% GDP growth.
MEED’s November 2026 report on the UAE includes:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into productionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20947110/main.gif -
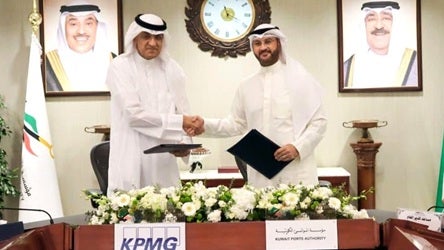
Kuwait appoints KPMG for ports strategic plan
4 November 2026
Register for MEED’s 14-day trial access
Kuwait Ports Authority (KPA) has appointed the local office of UK-headquartered KPMG to develop its ports strategic plan, which aims to improve the competitiveness, connectivity and performance of Kuwait’s commercial ports.
KPMG will act as lead consultant on the strategic consultancy engagement, with Netherlands-based Haskoning Nederland and local engineering firm Dar Gulf Consult providing engineering consultancy support.
KPMG will consolidate the three consultants’ work into a single strategic plan. It will lead the market, commercial and organisational analysis, as well as develop and implement the strategy.
The scope is split into two workstreams. The first covers strategy development, planning and an implementation framework, including an assessment of KPA’s current market position and performance.
The resulting strategic options and roadmap will be developed into detailed functional plans, supported by key performance indicators, a risk framework and a monitoring plan.
Under the second workstream, KPMG will set up and lead a strategic technical support office for 36 months. The office will provide KPA with strategic oversight, technical advisory services and integrated project management support.
KPA operates Kuwait’s three main commercial ports: Shuwaikh Port, Shuaiba Port and Doha Port.
In line with the New Kuwait Vision 2035 development strategy, KPA is transitioning its operations into high-efficiency smart ports by investing heavily in automated machinery, deeper navigational channels and significant berth capacity expansions.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21106611/main.jpg -
Combined Group signs Kuwait upstream contract
4 November 2026
Register for MEED’s 14-day trial access
Kuwait-headquartered Combined Group Contracting Company has signed a contract to repair and revamp production facilities in West Kuwait, according to a company statement.
State-owned upstream operator Kuwait Oil Company (KOC) awarded the contract, valued at KD9.7m ($31.4m).
The contract has a five-year term.
KOC issued the invitation to bid on 5 October 2025. The initial bid deadline was 4 January 2026, and a pre-tender meeting was scheduled for 4 November 2025.
The contract award to Combined Group was approved on 13 September 2026.
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruptions are the result of a regional war that started on 28 February when the US and Israel attacked Iran.
The disruptions to shipping in the Strait of Hormuz are also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the waterway.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21120792/main.png