Contractors vie for schemes worth $270bn
21 December 2023
Following one of the best years for project contract awards in the Middle East and North Africa (Mena) region in a decade, 2024 has a lot to live up to if it is to generate a similar amount of project activity.
By mid-December, the value of contract awards in 2023 had exceeded $230bn and was just $10bn shy of the $240bn-worth of regional contract awards let in 2014 – the best year on record to date. It was also on track to exceed that record year, with $36bn of projects in bid evaluation and expected for award by year’s end.
Nevertheless, 2024 has the potential to be an even better year for the Mena projects markets than 2023, with more than $270bn-worth of projects in the bidding phase and either overdue, due for award in the final weeks of 2023 – at the mid-December mark – or set for award at some point during 2024.
On top of this significant value of projects in the bidding stage, the region also has an estimated $250bn-worth of work in the design phase, with project trajectories that could quite reasonably see the schemes proceed through the prequalification, tendering and main contract award phases within the next 12 months.
Of the $270bn of value in the bidding stage, $126bn is in bid evaluation, with the main contract imminently due for award. A further $67bn is at the bid submission stage and $77bn is at the prequalification stage.
Imminent awards
Among the projects that are in the bidding phase and due for award in 2024 are six projects worth $4bn or more – all of which are in the GCC, with three in the UAE and one in each of Kuwait, Qatar and Saudi Arabia. They include three oil and gas projects, two power plants and one transport scheme.
The largest project contract in both the bidding phase, and specifically bid evaluation, is the estimated $7bn scheme for the development of surface facilities as part of the UZ1000 expansion programme by the offshore arm of Abu Dhabi National Oil Company (Adnoc Offshore) at the UAE’s Upper Zakum oil field.
Bids for the project have been submitted by the UK’s Petrofac, the local Target Engineering Construction Company and Spain’s Tecnicas Reunidas.
The next largest project in the bidding phase is the $6bn first package of the Duwaiheen nuclear power plant project, which entails the construction of two 2,800MW nuclear reactors on behalf of the Saudi special purpose vehicle Duwaiheen Nuclear Energy Company. Expected bidders include France’s EDF, China National Nuclear Corporation, Korea Electric Power Corporation and Russia’s Rosatom.
The third largest scheme, and one that is at the prequalification stage, is the estimated $4.8bn Blue Line for the Dubai Metro, tendered by the Roads & Transport Authority after the project was greenlit in November 2023. Expressions of interest for the 12-station line are being sought from three consortiums.
Close behind this is the $4.5bn Ruwais liquefied natural gas terminal, which is being tendered by Adnoc Gas Processing, and for which more than half a dozen companies have submitted bids.
In Kuwait, the $4bn combined phases two and three of Al-Zour North independent water and power project are being tendered by the Ministry of Electricity & Water via the Kuwait Authority for Partnership Projects. Five bidders have submitted prequalification documents for the scheme.
Pending in Qatar, there is the $4bn phase two, scope D of works on the North Field production sustainability project, for which submissions to QatarEnergy LNG are due by the end of December.
Top markets
The country with the highest value of project work in the bidding phase – and more than double that of the next most active projects market – is Saudi Arabia, which alone has schemes worth $107bn. This includes $46.5bn-worth of work in bid evaluation, $34.3bn in bid submission and $26.4bn at the prequalification stage.
The work in Saudi Arabia is concentrated in the hands of several large clients, led by Saudi Aramco, which has $22bn-worth of work under bid, and Neom, which has $19bn of associated projects under bid.
There is a further $8.6bn-worth of work associated with the four other official gigaprojects: Diriyah Gate, Qiddiya, the Red Sea Project and Roshn. There is also $7.7bn-worth of work in the bidding phase as part of the Saudi Power Procurement Company’s renewable energy programme.
The projects market with the second-largest value of imminently pending work is the UAE, with $51.5bn-worth of work under bid, including schemes worth about $30bn in bid evaluation. This work is led by the oil and gas sector, with $22.6bn of work being tendered by Adnoc Group.
Elsewhere in the GCC, Kuwait, Oman and Qatar have, respectively, $19.8bn, $17.9bn and $15.7bn of projects under bid. Overall, the GCC markets account for $216bn or 80 per cent of the $270bn total of work under bid, with Saudi Arabia and the UAE alone accounting for $159bn-worth of work, or 59 per cent of the total.
Close behind these markets is Algeria, which has $15.3bn-worth of schemes in the bidding phase, alongside lesser values in Egypt and Iraq, at $10.7bn and $7.7bn, respectively. There is then a further $24bn-worth of work under bid spread across the other countries in the Mena region.
Strongest sector
Segregated by industry, of the $270bn-worth of work in the bidding stage, there are: projects in the construction and transport sector worth a combined $97.7bn; schemes worth $97.6bn in the power, water and utilities sector; and programmes worth $74.8bn in energy industry.
This breaks down further into $53.1bn of transport projects, $44.6bn of construction projects, $59.7bn of power projects, $37.8bn of water projects, $32.9bn of gas projects, $29.2bn of oil projects, and $12.6bn of chemicals and other industrial schemes.
Top clients
The top 10 project clients in the region by value of projects currently in the bid stage account for $103bn or 38 per cent of the $270bn of total project value under bid. Out of this group of regional heavyweight project owners, five are Saudi entities: Saudi Aramco, Neom, Saudi Power Procurement Company (SPPC), Duwaiheen Nuclear Energy Company (DNEC) and Saudi Electricity Company (SEC).
The top project client outside of Saudi Arabia is the UAE’s Adnoc, which comes second only to Saudi Aramco in terms of the value of projects in the bidding stage. Adnoc is accompanied in its representation of the UAE in the ranking by Dubai’s Road & Transport Authority (RTA).
The list is then rounded out by Algeria’s Sonelgaz and two Kuwaiti entities: Kuwait Authority for Partnership Projects (Kapp) and Kuwait Oil Company (KOC).
Both Saudi Aramco and Adnoc have more than $20bn-worth of projects under bid, followed closely by Neom, which has $17.6bn-worth of projects across its constituent masterplans, led by Oxagon, Trojena and The Line.
The three Saudi utilities sector clients, SPPC, DNEC and SEC, then have $7.3bn, $6.5bn and $6.3bn under bid, respectively. Sonelgaz is close behind, with $6.2bn under bid, followed by Kapp, the RTA and KOC, with $6bn, $5.4bn and $4.9bn, respectively, under bid.
The line-up reflects the broader pattern of a strong concentration of project activity in the Mena region within the GCC, and especially within Saudi Arabia and the UAE, as the pre-eminent GCC projects markets.
 Top pending projects in 2024 (to be published on 27 Dec 2023)

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Bahrain construction activity remains subdued
5 November 2026
-
 Bahrain creaks under the strain of war
5 November 2026
-
 Sharjah opens first phase of new Dubai road connection
5 November 2026
-
 Engie completes refinancing of Oman power plants
5 November 2026
-
 Aramco seeks to expand East-West crude pipeline
5 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Bahrain construction activity remains subdued
5 November 2026

Bahrain’s construction and infrastructure sector remains subdued, with project awards still depressed despite a modest uptick this year.
Data from regional projects tracker MEED Projects shows that $737m-worth of construction and infrastructure contracts had been awarded in the kingdom by 29 October 2026. While this exceeds the $686m recorded across the whole of 2025, it confirms that the market remains in a prolonged downturn.
Between 2016 and 2020, Bahrain recorded more than $2bn in annual awards, peaking at nearly $3.9bn in 2016 when major packages for the Bahrain International airport expansion were signed. Awards then fell to $912m in 2021 before rebounding to almost $2bn in 2022. The recovery was short-lived, with awards declining to $1.66bn in 2023, $1.57bn in 2024 and $686m in 2025.
Major awards
Activity this year has been supported by several housing and transport packages.
The largest award was an estimated $400m contract secured by a joint venture of local developer Naseej and China Machinery Engineering Corporation for the Madinat Khalifa project. Procured under the Mega Government Land Development Programme, the scheme involves the design, financing, construction, marketing and sale of more than 2,500 housing units on two government-owned land parcels, alongside roads and electricity, water, sewage and drainage networks.
Road infrastructure also produced a major commitment. The Ministry of Works amended its award for package four of the Busaiteen Link project, appointing a joint venture of Nass Company and Nasser Hazza Al-Subaei Contracting Company under a BD65m ($172m) contract. The three-year deal replaces a BD69.7m ($185m) award made in January to a consortium of Haji Hassan Group, Saudi Arabia’s Alomaier Trading & Construction Company and Greece’s Terna.
The package includes a signature bridge connecting Muharraq with the North Manama Causeway and Bahrain Bay, as well as road works between junctions four and five.
Residential projects provided further volume. Mohammed Abdulmohsin Al-Kharafi & Sons secured a $112.4m contract to build 512 social apartment units on Madinat Salman’s Island 12. Binaa Al-Bahrain also appointed Kooheji Contractors to build Bayview in Manama, a development comprising four residential buildings and 489 apartments.
Early-stage commitments included a BD5m ($13.5m) consultancy contract awarded to US-based Populous for the planned Sports City at Sakhir. The scope covers the masterplan, internal infrastructure, phase 1A design and tender documents. Lebanon’s Dar Al-Handasah won a QR28m ($7.7m) contract to conduct feasibility studies for the proposed 40-kilometre Qatar-Bahrain Causeway, also known as the Friendship Bridge.
Transport links
Transport is the most promising near-term outlet for the market, with a pipeline valued at about $15bn, according to MEED Projects data.
Cross-border rail has re-emerged as a strategic focus. Bahrain has introduced legislation to establish a framework for constructing, operating, maintaining and regulating railway networks, including licensing, safety, cross-border services, and passenger and freight tariffs.
The move comes as Gulf states prepare to advance the GCC railway network, which is expected to begin operating by the end of 2030. Bahrain’s proposed rail link to Saudi Arabia is expected to run via the planned King Hamad Causeway, a second fixed connection between the two countries alongside the King Fahd Causeway.
Road expansion is also progressing. In September, the Bahrain Tender Board received bids from Nass Contracting, Haji Hassan Group, Almoayyed Contracting Group, Mohammed Abdulmohsen Al-Kharafi & Sons, Eastern Asphalt & Concrete Production, Cebarco Bahrain and Kingdom Asphalt for the upgrade of two kilometres of the Sheikh Jaber Al-Ahmed Al-Sabah Highway. The works involve a four-lane dual carriageway with service roads.
Industrial and maritime infrastructure is advancing, too. The Ministry of Works received five bids for engineering and quantity surveying services linked to reclamation works at Salman Industrial City and Bahrain Logistics Zone.
Dar SSH International Engineering Consultants submitted the lowest offer at BD778,580 ($2.1m), followed by Aecom at $2.2m, Ansari Engineering Services at $2.3m, Millet Engineering Bureau at $2.4m and Ayesa at $2.8m. The project involves reclaiming about 1.13 million square metres of land using 9.67 million cubic metres of fill near Khalifa Bin Salman Port.
The government is also preparing the Bahrain Northern Link Road as a public-private partnership. The 29.5km highway will connect the North Manama Causeway with Suhaila Island and the King Hamad Causeway, creating a parallel east-west route to Sheikh Isa Bin Salman Highway and improving links between Khalifa Bin Salman Port and Saudi Arabia.
Building pipeline
Outside transport, Bahrain’s construction pipeline exceeds $6bn. The most prominent project is the Bahrain International Sports City development in Sakhir. In September, 21 local and Saudi Arabian contractors were prequalified for the first-phase construction contract, which is expected to include Bahrain’s largest sports stadium and a multipurpose indoor sports arena.
The planned National Assembly Building in Manama is another significant civic project. Bids submitted earlier this year included three options from Cebarco Bahrain, ranging from $163.8m to $200.3m, alongside offers of $239.4m from Nass Contracting and $316.4m from Kooheji Contractors.
The four-storey complex will be built on a reclaimed island and will include a main hall for joint sessions, separate debating chambers, administrative offices, an auditorium, library, museum, meeting rooms, public spaces, underground parking and supporting facilities.
These projects provide a route out of Bahrain’s multi-year downturn. The market’s recovery, however, will depend on whether the government converts feasibility studies, advisory mandates and prequalification exercises into construction awards.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21181473/main.gif -
Bahrain creaks under the strain of war
5 November 2026
With a small economy and exports almost wholly reliant on passage through the Strait of Hormuz, Bahrain has been painfully exposed to the turmoil caused by the Iran war. The country’s social makeup – with a Shia majority ruled by a Sunni-dominated regime – is also showing signs of strain.
The economy is expected to contract by 11.3% this year, according to the IMF’s latest Regional Economic Outlook report. That is not quite as bad as some of its neighbours, such as Kuwait and Qatar, but it is well above the 4.8% fall expected for the GCC as a whole.
Just as importantly, Bahrain also starts from a much weaker base than its Gulf peers, with a smaller economy, limited hydrocarbon resources and high levels of government debt.
“Countries with the largest reserve declines since the start of the conflict generally entered the shock with comfortable reserve positions, with Bahrain as a notable exception,” the IMF noted in its 22 October report.
Physical disruption
Iran’s closure of the Strait of Hormuz this year has cut Bahrain off from its most important trade route for both exports and imports. In addition, major industrial and military targets have been hit by Iran on multiple occasions, including the US naval base and the Aluminium Bahrain (Alba) plant.
The latter suffered a 32% year-on-year drop in sales volumes and a 61% fall in output in the first half of the year as a result of the Iranian attacks – although higher aluminium prices and lower costs meant that the company’s revenues held steady and profits actually increased year-on-year.
Other areas of the economy have been badly affected too, with the Bapco oil refinery, a desalination plant and an Amazon data centre all hit in Iranian strikes. The IMF also noted that Bahrain has seen one of the worst declines in hotel occupancy rates during the year. Inflation has also been rising, reaching an annual rate of 3% as of July.
As a result, the government’s already weak financial position is under even more pressure. The Central Bank of Bahrain’s reserves have slumped sharply since the start of the war, falling from BD1.8bn ($4.8bn) as the war broke out, to a low of BD568m three months later. They recovered some of the ground lost in the following months, but remain well below the pre-war level. Reserves stood at BD887m by September, supported by drawing on a BD2bn ($5.4bn) currency swap line provided by the UAE in early April.
Total public debt had reached BD20.3bn at the end of August, the most recent data available, up from BD18.2bn a year earlier. That is significantly larger than the country’s GDP, which stood at BD15.7bn in 2025 and is expected to end this year at just BD13.9bn.
To make matters worse, the markets have been pushing up Bahrain’s borrowing costs to levels not seen since 2018, when the government had to turn to Kuwait, Saudi Arabia and the UAE for a bailout to avoid a potential sovereign default.
External support
With no easy way to reduce its debts or plug its budget deficit, Bahrain is likely to seek more assistance from its wealthy neighbours – although any aid will likely come with demands for spending restraint and other reforms that will be uncomfortable for the government to accept.
The appetite of some neighbouring states may also be more limited than in the past, given their own economies have been weakened by the war, but King Hamad Bin Isa Al-Khalifa’s close ties with the UAE leadership in particular are likely to ensure some help is forthcoming.
Asharq Bloomberg reported in late October that Manama has been holding talks with neighbouring states for a fresh round of support, with the UAE expected to emerge with a leading role. However, the timing and scale of any bailout remain unclear.
Without external assistance, the country’s finances are likely to deteriorate further. Ratings agency Capital Intelligence said in an October report that it expected debt levels to rise further in 2027-28, with the budget deficit averaging 9.3% of GDP in those years.
“The burden of government debt on the budget is also very high, with interest payments projected to average 30.7% of revenues in 2026-28, up from 27.1% in 2025,” it noted.
King Hamad Bin Isa Al-Khalifa’s close ties with the UAE leadership in particular are likely to ensure some help is forthcoming
Political tensions
Politically, Manama has appeared increasingly cautious towards its own citizens, with planned elections for both municipal councils and the Council of Representatives delayed until next year. Announcing the postponement of the council elections in mid-October, deputy prime minister Sheikh Khalid Bin Abdulla Al-Khalifa referred vaguely to “the current circumstances and their resulting effects” as the reason for the delay.
The postponement removes a formal channel for the public to express grievances about the country’s current situation. At the same time, the authorities have moved against perceived support for Iran during the conflict. More than 600 people have been arrested this year on charges including espionage and supporting an enemy state, according to the Bahrain Institute for Rights and Democracy (Bird), a London-based advocacy group that is critical of the government. Dozens of people have also had their citizenship revoked.
“Since the outbreak of the Iran war, repression in Bahrain has intensified sharply,” said Bird advocacy director Sayed Ahmed Alwadaei.
Some analysts warn that the crackdown could prove counterproductive. The Bahrain researcher at conflict monitoring group Acled said that tensions between the government and its Shia opposition were gradually placing the country at high risk of instability.
The economic outlook could change quickly if a resolution to the Iran-US conflict is found. The IMF predicts that the economy could rebound to a growth rate of 13.9% next year, before settling back to a more sustainable 3.1% the year after – but that depends on Gulf trade routes reopening and energy production normalising. The country’s political tensions will be harder to resolve.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21173733/main.gif -
Sharjah opens first phase of new Dubai road connection
5 November 2026
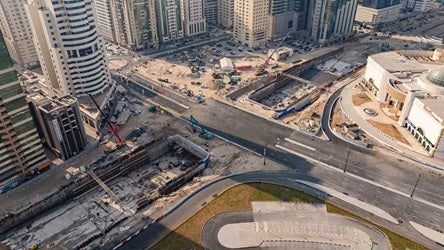
Sharjah’s Roads & Transport Authority (SRTA) has partially opened the first phase of a major road development project designed to improve connectivity between Sharjah and Dubai.
The initial opening includes the partial launch of the Al-Taawun interchange, alongside several bridges and junctions providing one-way traffic flow from Sheikh Mohammed Bin Zayed Road toward Expo Centre Sharjah.
Tunnel construction in the Al-Taawun area is also progressing under the scheme. The 500-metre-long tunnel will run beneath the Al-Taawun roundabout, providing three lanes in each direction to link Al-Taawun Street to Al-Nahda Bridge and onward to Dubai.
The project will also include a signalised intersection designed to handle approximately 4,200 vehicles an hour in each direction. In addition, the tunnel will provide access to Expo Centre Sharjah and form part of a transport corridor linking to Al-Noor Road.
The Al-Taawun tunnel project is the centrepiece of a broader AED750m ($204m) road development programme in Sharjah, which comprises a network of tunnels, bridges and intersection upgrades.
The other projects that form part of the programme include:
- Al-Noor Road: Extends from Al-Orooba Street into Dubai via Al-Nahda Bridge, serving residential and commercial communities in Sharjah and adjacent districts in Dubai.
- Industrial Streets 1 and 2 bridges: Involves constructing two 130-metre-long bridges with two lanes in each direction. These will connect to Maleha Road, Sheikh Khalifa Bin Zayed Road and Al-Waset Road, adding capacity of roughly 2,800 vehicles an hour in each direction.
- Industrial Street 3: Encompasses two new bridges linking Sharjah’s industrial zones to the Ring Road. The 2.7-kilometre scheme will add dedicated turning lanes toward Maleha Road, Sheikh Khalifa Road and Al-Dhaid Road, along with a culvert linking Industrial Street 3 to the Ring Road. It will increase capacity by about 5,200 vehicles an hour across both directions, improving links between Sheikh Mohammed Bin Zayed Road, Al-Khan Street and Al-Ittihad Road.
- Sheikh Mohammed Bin Zayed Road Interchange: Entails upgrading the existing interchange to improve connections between the highway and the Al-Taawun, Al-Khan and Al-Buhaira districts.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21172614/main.jpg -
Engie completes refinancing of Oman power plants
5 November 2026
French developer Engie has announced that it has reached financial close on the refinancing of the Sohar 2 and Barka 3 independent power projects (IPPs) in Oman.
The transaction follows 15-year extensions to the plants’ power purchase agreements (PPAs) in March, securing their long-term operations through to 2043.
As previously reported by MEED, the new agreements for the 750MW Sohar 2 and 750MW Barka 3 IPPs will take effect on 1 April 2028.
The refinancing aligns the projects’ debt profiles with the extended PPA terms and establishes a long-term financing framework to support future capital expenditure. This includes refurbishment works aimed at improving the reliability and long-term performance of both assets.
Al-Batinah Power Company and Al-Suwadi Power Company operate the Sohar 2 and Barka 3 power plants, respectively.
According to regional projects tracker MEED Projects, Nama PWP signed the original PPA for the Barka 3 project in 2010 with a consortium led by Gaz de France (GDF) Suez under a special purpose vehicle called Al-Suwadi Power Company.
The shareholders comprised GDF Suez (46%), Bahwan Engineering Company (22%), Shikoku Electric Power Corporation (11%), Sojitz Corporation (11%) and the Public Authority for Social Insurance (10%).
In 2015, GDF Suez was rebranded as Engie following a strategic shift towards low-carbon energy and utilities.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21170932/main.jpg -
Aramco seeks to expand East-West crude pipeline
5 November 2026
Saudi Aramco is planning to expand its East-West oil pipeline network, aiming to strengthen the kingdom’s ability to transport crude oil while bypassing the Strait of Hormuz.
Aramco operates the 1,200-kilometre East-West pipeline from Abqaiq in the Eastern Province to Yanbu on the Red Sea coast. The pipeline currently has an oil transportation capacity of 7 million barrels a day (b/d).
The pipeline was targeted by Houthi missiles in September and by Iran in April. Aramco resumed crude oil exports through the pipeline at the start of October.
“With regard to the expansion to our East-West pipeline and the additional networks that we are building, this work has already started,” Amin Nasser, Aramco’s president and CEO, told analysts on a call following the company’s announcement of its Q3 2026 financial results on 3 November.
Nasser had previously said in an interview with Al Arabiya Business that Aramco had begun engineering work on the East-West pipeline expansion project during the early stages of the US-Iran conflict.
In October, Saudi Energy Minister Prince Abdulaziz Bin Salman said that the kingdom was looking to expand its crude oil export capacity by pipeline to as much as 10 million b/d. The plans would involve repurposing a domestic gas pipeline and investing in the existing East-West pipeline network.
Aramco uses three main routes to export crude oil: the Gulf, via the Strait of Hormuz; the Red Sea, via the Bab El-Mandeb strait; and the Mediterranean, via Sidi Kerir in Egypt. The company also uses overseas oil-storage facilities in South Korea, Japan, the Netherlands and Sidi Kerir, and is working with partners to expand storage capacity, particularly in Asia.
Aramco is also undertaking engineering work on additional export routes, Nasser said.
He added that the company would not disclose details of the proposed routes until it made final investment decisions.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21156806/main0615.jpg