Uncertainty and instability damage Libyan oil sector optimism
24 February 2025

Register for MEED’s 14-day trial access
Optimism among stakeholders in Libya’s oil and gas sector has evaporated in recent months as the approval of the country’s budget has been delayed and instability has undermined operations at state-owned oil and gas companies.
In early February, the UN Support Mission in Libya (Unsmil) called for all the conflicting parties in the North African country to start work immediately on agreeing on a unified state budget.
It said a transparent and equitable budget is crucial for strengthening fiscal responsibility, optimising resource allocation and ensuring economic stability in Libya.
Unified budget
A unified budget is also expected to enhance the ability of the Central Bank of Libya to implement effective monetary policies, stabilise the exchange rate and manage public spending sustainably.
Several meetings have been held to attempt to reach an approval on a unified budget for 2025, but little progress has been made by Libya’s rival political factions towards reaching an agreement.
In December, Stephanie Koury, acting UN special representative for Libya, said: “A unified budget is essential to establish clear spending limits and ensure transparent management of public resources.”
Libya’s oil and gas industry is one of the most important sectors, in terms of generating government revenues, that has been impacted by the budget delays.
One industry source said: “If a unified budget isn’t approved within the next 30 days, the consequences are going to be very serious.
“You can forget about all of the progress that has been made in the country’s oil and gas sector over the last two or three years – we are going to set right back to square one.”
Without a budget being approved, state-owned oil companies are struggling to push forward with their investment plans and the development of projects.
Licensing round
As well as ongoing delays to projects and approvals in Libya’s oil and gas sector, the country’s plans for its first oil and gas licensing round in 15 years are being delayed.
In January 2024, Libya’s National Oil Corporation (NOC) announced its plan to launch the round.
The bid round for exploration and production agreements was expected to offer exploration blocks in the Murzuq, Ghadames and Sirte basins.
As well as ongoing delays to projects and approvals in Libya’s oil and gas sector, the country’s plans for its first oil and gas licensing round in 15 years are being delayed.
Throughout much of 2024, there was significant optimism that the round would be launched without major delays and that it could support the country’s plans to boost oil and gas production.
In 2024, NOC announced a plan to execute 45 greenfield and brownfield projects to try to boost the country’s oil production from 1.25 million barrels a day (b/d) to 2 million b/d.
Libya is aiming to hit its 2 million b/d target within three years.
It was initially expected that the planned licensing round would be launched in late October or early November of 2024.
However, in October, delays started to be announced – and now stakeholders have significant doubts about whether the round will be launched before the end of 2025.
The budget delays and other ongoing disagreements between the country’s rival political factions are damaging the image of the country’s oil and gas sector and are likely to make international companies less interested in participating in the bidding round, if it is eventually launched.
One industry source said: “In the middle of last year, a lot of big international companies were showing interest, but now it is all negativity.
“People were talking about the licensing round and new projects, as well as expanding existing projects.
“Now, all of those discussions have evaporated.”
Sentiment is also being damaged by clashes in the country.
In 2024, there were several violent clashes between militias, including in Zawiya in July.
These were followed by further hostilities in the same region in December, which occurred next to the Zawiya refinery and caused a major fire at the facility.
Oil sector leadership
Instability in Libya’s oil and gas sector has been exacerbated by major changes in senior positions within the country’s publicly owned oil and gas companies and the oil ministry.
In June 2024, Libya's sidelined oil minister Mohamed Oun called on Tripoli-based Prime Minister Abdelhamid Dbeibeh to clarify who was in charge of the ministry.
Exactly who ran the oil ministry became unclear after Oun returned to work on 28 May 2024, following the lifting of a temporary suspension by a state watchdog.
During his absence, Oun was replaced by oil ministry undersecretary Khalifa Rajab Abdulsadek, who represented Libya at an Opec+ meeting on 2 June.
Oun complained that Dbeibeh refused to recognise him as oil minister after his return to work, and Oun then cut off all communication with him, making it impossible to carry out his duties.
Oun was ultimately officially replaced by Abdulsadek, who continues to run the ministry.
NOC has seen other major changes. The resignation of chairman Farhat Bengdara was accepted in January and he has been replaced by acting chairman Massoud Suleman.
NOC subsidiaries have also seen tumultuous changes in recent months.
In mid-February, the chairman of Libya’s state-owned Waha Oil Company, Fathi Ben-Zahia, was detained on several charges, sparking concerns about the future of oil and gas projects in the country.
Waha is one of the biggest and most active subsidiaries of NOC and is responsible for some of the country’s biggest active oil projects.
The charges against Ben-Zahia include a LD770m ($156m) contract fraud, according to a statement issued by the country’s Attorney General’s Office.
The statement said that preliminary research by the attorney general’s deputy public prosecutor had revealed that the Waha chairman had awarded a contract worth LD770m for sea defences at the Sidra oil port, when a lower bid of LD339m was submitted by another company competing for the contract.
Prior to the arrest of Ben-Zahia, Waha was seen as one of the best-performing state oil companies in the country.
In November last year, Waha Oil Company reported its highest crude production level in 11 years.
The company recorded a daily output of 350,549 barrels, contributing to Libya’s total daily production of 1.4 million barrels.
Private sector
While the country’s public sector oil companies have run into more problems in recent months, and struggled to deal with issues related to the delays to the unified budget, Libya's first private company to export oil has seen significant growth.
Arkenu Oil Company, which was set up in 2023 and is linked to the faction that controls eastern Libya, has exported oil worth at least $600m since May 2024, according to shipping records and UN experts.
According to experts, this means that some of the country's oil revenue is likely being channelled away from the central bank.
One industry source said: “The activities of Arkenu Oil Company are worrying because it shows that institutions like NOC and the central bank are losing their grip on the country’s oil and gas sector.”
Economic problems
Projects in Libya are also suffering from broader economic issues that could get a lot worse if there are further delays to the approval of a unified budget for 2025.
NOC is already suffering from major cash flow issues that will be exacerbated by further delays.
It is also likely that value of the Libyan dinar against the US dollar on the black market will be weakened, and more pressure will be put on the country’s foreign exchange reserves.
Further currency weakness is likely to make it harder to import materials and equipment for new projects, as well as making it more difficult to get spare parts for existing facilities.
One source said: “Right now, the dialogue about oil and gas projects in Libya is changing dramatically.
“Before, we were talking about which new projects were going to get developed and how quickly. Now, we are no longer talking about new projects and there are concerns that existing facilities will face major problems.”
The ongoing challenges in Libya, and the failure to deal with key issues, means that in the future the country could see declines in upstream production rates and refinery throughput, rather than the expansions that were previously expected.
 READ MEED’s YEARBOOK 2025
MEED’s 16th highly prized flagship Yearbook publication is available to read, offering subscribers analysis on the outlook for the Mena region’s major markets.
Published on 31 December 2024 and distributed to senior decision-makers in the region and around the world, the MEED Yearbook 2025 includes:
|
> PROJECTS: Another bumper year for Mena projects
> GIGAPROJECTS INDEX: Gigaproject spending finds a level
> INFRASTRUCTURE: Dubai focuses on infrastructure
> US POLITICS: Donald Trump’s win presages shake-up of global politics
> REGIONAL ALLIANCES: Middle East’s evolving alliances continue to shift
> DOWNSTREAM: Regional downstream sector prepares for consolidation
> CONSTRUCTION: Bigger is better for construction
> TRANSPORT: Transport projects driven by key trends
> PROJECTS: Gulf projects index continues ascension
> CONTRACTS: Mena projects market set to break records in 2024
|

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 H&H continues to deliver Dubai projects
29 October 2026
-
 Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
-
 Iraq oilfield water scheme to hit milestone next year
29 October 2026
-
 Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
-
 Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
H&H continues to deliver Dubai projects
29 October 2026
Dubai-based developer H&H has launched Water Gardens, a mixed-use development in Dubai International Financial Centre (DIFC), and expects to award most of the construction contracts for its wider pipeline before summer 2027.
Water Gardens comprises four buildings designed by UK architect David Chipperfield, arranged around a central garden and pedestrian-friendly public realm. The scheme combines offices, residences, hospitality and retail offerings, including the Four Seasons Private Residences Dubai at DIFC and residences under H&H’s Eden House brand.
 Construction is under way, and the developer says the project is scheduled for completion in 2028. DIFC Investments describes it as one of the final components of the original Gate District masterplan.
Speaking to MEED at the launch, H&H chairman Shahab Lutfi said the office building and Eden House are due for completion in about 18 months. The Four Seasons residences are scheduled for delivery at the end of 2028, with a five-star hotel following later.
Water Gardens is one of several projects H&H has under way. The company undertakes a selective portfolio of high-end real estate developments in prime locations in Dubai. These include the Carlyle Residences in DIFC; an Eden Hills villa community in Mohammed Bin Rashid City; and Dubai Peninsula, a waterfront scheme in the Jumeirah area that will include hotels operated by Aman and Rosewood.
“We are awarding day in, day out,” says Lutfi. “I think we are awarding most of our contracts from now until summer next year.”
Most of the company’s construction volume is in DIFC and Dubai Peninsula, with the Eden Hills villas accounting for a smaller share. Lutfi says H&H is talking to several of the emirate’s biggest contractors about upcoming packages.
We are awarding [contracts] day in, day out
Staged procurement
H&H is managing cost pressures by splitting up its procurement. It awards main contracts covering concrete works with a large number of provisional sums, then tenders further packages as designs are completed. “We are taking on some of the risk, but we know how to manage the risk instead of just offloading it on the contract,” says Lutfi.
He does not expect construction costs to fall in the next 12 months. Global inflation, driven by fuel prices and logistics costs, is already factored into the company’s plans.
“Waiting and trying to award at a cheaper price is not an option for us,” he says.
Lutfi says rising costs need not erode margins for developers that keep unsold stock to sell at higher prices later in a project. Developers that sell out early are more exposed. “If you have already sold out two years ago, you are hurting your profitability,” he says.
H&H is comfortable leaving 15%-20% of a project to sell on completion. The market usually expects developers to sell out before handover.
The company has not revised its masterplans or product mix in response to market conditions and continues to focus on large units.
Supply chains have been a challenge this year, but Lutfi says the company is over that hurdle. H&H has sourced more materials locally and planned logistics further in advance.
Materials are reaching Dubai through bonded routes from Oman, Fujairah and Khor Fakkan in the UAE, and Jeddah in Saudi Arabia.
“It takes a little bit longer, but at least things are coming in,” he says.
H&H relies on a relatively small group of contractors that work on most of its projects, and treats them as long-term partners.
Lutfi says contractors are attracted by the company’s financial stability and volume of work. “That can keep some people busy for the next five or six years,” he says.
Lutfi notes that sales in the Dubai market have dropped, although enquiries have picked up since the summer as buyers weigh whether it is the right time to purchase. The distressed sales that some had expected have not materialised.
“A 5% discount in some units is not really a distress sale,” he says. “It is just someone trying to get a discount because of the region’s situation, which actually builds confidence.”
For Water Gardens, H&H has sold 85% of Four Seasons Private Residences Dubai at DIFC since sales began in 2024. The company launched sales at the Carlyle Residences before the regional disruption and has since sold units one-to-one to selected clients. More Four Seasons units have been sold in the past two weeks.
“Branding makes a big difference,” says Lutfi.
The company markets its branded residences through a global network of brokers rather than via public campaigns or launch events. Eden Hills, which is aimed mainly at Dubai residents, is marketed more widely.
Lutfi expects buyers to be more cautious about buying off-plan. H&H is building new sales centres at Dubai Peninsula and in DIFC so that clients can see the product before they commit.
“People have to come in, know exactly what they are buying, and they will feel comfortable paying the price – instead of just having a pretty brochure,” he says.
He expects demand for villas to become more local and regional, while branded residences will continue to attract international buyers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21012636/main.gif -
Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
Expo 2030 Riyadh Company (ERC), responsible for delivering the Expo 2030 Riyadh venue, has allowed contractors until 11 November to submit bids for a contract to deliver the Souq areas within the Expo site.
The tender was floated on 30 July, with an initial submission deadline of 9 October.
The Souq areas are divided into five distinct precincts, with a total development area of about 300,000 square metres (sq m).
The scope includes the five precincts and their associated vertical elements, infrastructure and public realm works.
The precincts comprise:
- Precinct 1 – The Icon: 41,417 sq m
- Precinct 2 – Place & Planet: 62,306 sq m
- Precinct 3 – Culture of Wisdom: 67,112 sq m
- Precinct 4 – Kingdom of Saudi Arabia: 45,967 sq m
- Precinct 5 – Adaptation & Innovation: 82,358 sq m
The package will interface with three public parks. It will also tie into the Natural Corridor, including bridges.
The Souq areas will form a mixed-use destination at the centre of Expo 2030 Riyadh, connecting the site’s iconic and thematic assets.
The development will include rented and partnership pavilions, alongside a range of food and beverage, retail and visitor-experience offerings.
Site progress
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to build a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts to local firm Al-Yamama Company for the next phase of infrastructure works at the site.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, and electric vehicle charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20998514/main.jpg -
Iraq oilfield water scheme to hit milestone next year
29 October 2026
China Petroleum Pipeline Engineering (CPP) expects to start laying pipeline for Iraq’s Common Seawater Supply Project (CSSP) in Basra in mid- or late next year, according to industry sources.
The project is behind schedule, partly because importing sections of pipeline is proving challenging due to disruptions to shipping through the Strait of Hormuz.
The project is being managed by state-owned Basra Oil Company (BOC), with Australia’s ILF acting as a project management consultant after completing the front-end engineering design (feed).
Under current plans, the pipelines will be buried, which is expected to make them more secure than if they were installed on the surface.
Phased development
The client for the first phase of the CSSP is France’s TotalEnergies in partnership with QatarEnergy and BOC.
The first phase is split into two packages currently under execution and will ultimately have the capacity to transport 5 million barrels a day (b/d) of water.
The first package focuses on developing pipelines, and the second on developing a water treatment facility.
CPP is executing the pipeline package contract.
It signed a $2.5bn contract with BOC for the package in September last year.
Also in September 2025, South Korea’s Hyundai announced that it had signed a contract worth 4.39tn won ($3.16bn) for the processing plant package.
In September this year, MEED reported that early groundworks had started for both packages of the first phase of the CSSP.
Phase one of the project is scheduled to start up in late 2028 or early 2029.
Earlier this month, US-headquartered Exxon Mobil signed a memorandum of understanding related to the project’s second phase, which is expected to add 2.5 million b/d of water capacity.
The CSSP will inject processed water into several of Iraq’s biggest oil fields. These include Rumaila, Zubair, West Qurna 1, West Qurna 2 and Majnoon. Water from the project will also be used in the Maysan and Dhi Qar fields.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20981033/main.jpg -
Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
Dubai Municipality has invited contractors to bid for a contract to build sewerage and stormwater infrastructure in New Al-Awir 1st.
The project (DS317-C1) comprises about 95 kilometres of sewerage gravity network, excluding house connections, and about 105km of stormwater pipelines. The scope also includes house connection pipes, a stormwater pond and oil interceptors.
According to tender documents seen by MEED, the tender was issued on 23 October, with a bid submission deadline of 12 November.
The project comes amid wider residential and infrastructure development in Al-Awir 1. In January 2025, Dubai’s Roads & Transport Authority (RTA) announced plans to build 16.5km of internal roads in the area, including a new entrance from Emirates Road.
In February 2025, MEED exclusively reported that the RTA had selected a local firm to undertake the road construction works.
The Mohammed Bin Rashid Housing Establishment has also reported progress on housing projects in Al-Awir as part of a wider programme to develop residential communities across Dubai.
The sewerage and stormwater project is relatively large compared with recent stormwater tenders, with the total cost estimated at up to AED1bn ($272m).
The works will include approximately 69.2km of house connection pipes and 4,630 inspection chambers. The sewerage network will also include about 1,511 manholes, while the stormwater network will comprise approximately 1,247 manholes.
Contractors will also be required to use no-dig construction methods for sections of the pipeline. The scope includes ground investigations, utility protection and traffic management.
The bill of quantities specifies a stormwater pond with a composite volume of approximately 1.2 million cubic metres.
Earlier this week, Dubai Municipality confirmed it had awarded contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects are part of Dubai’s AED30bn Tasreef programme and will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom.
The overall programme aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20977734/main.jpg -
Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
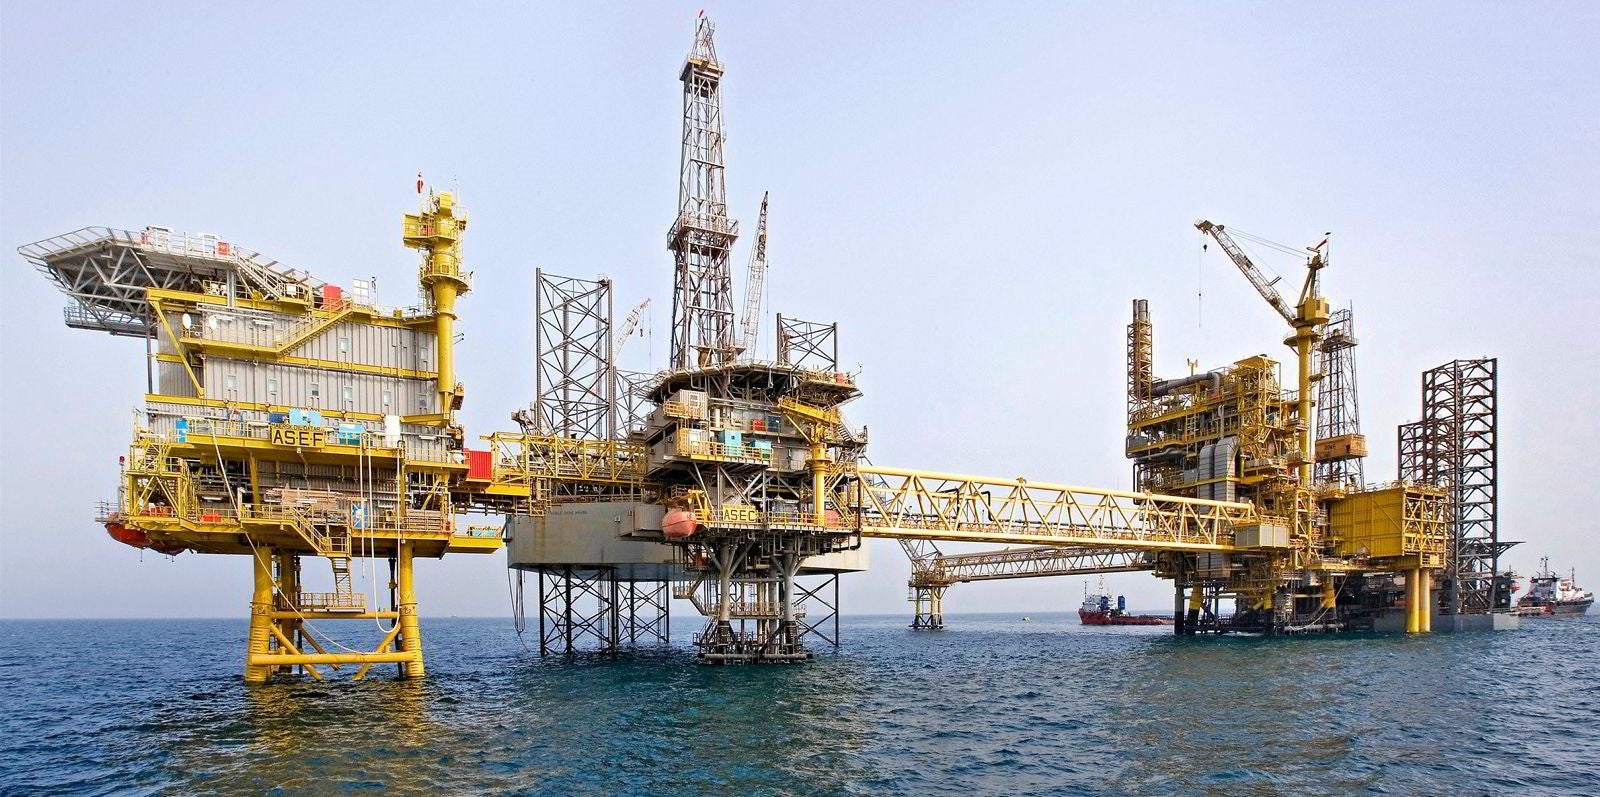
QatarEnergy has received technical bids from contractors for a key tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors submitted their technical bids by the 26 October deadline, according to sources.
Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The modules will increase gas production from North Field reservoirs and supply additional gas feedstock to the NFW liquefied natural gas (LNG) development.
Issued earlier this year, the tender forms part of the wider NFW project, the third and final phase of QatarEnergy’s North Field LNG expansion programme.
The technical-bid deadline has been extended several times, from 30 August to 15 September, 28 September, 12 October and 19 October. Commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott an EPCI contract for four offshore jackets to support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20973187/main.jpg