UAE maintains regional economic edge
14 January 2025

Heading into 2025, the UAE and Saudi Arabia continue to maintain their significant lead in the MEED Economic Activity Index. These opportune markets sit alongside three of their GCC peers – Oman, Qatar and Kuwait – as economies whose real GDP is supported by relatively robust hydrocarbon revenues.
In 2025, the GCC economies are forecast to grow by an unweighted real GDP growth rate average of 3.3%, compared to just 1.4% in 2024, according to the latest IMF estimates. Across the countries featured in the index, the figure for 2025 was 3.2%, compared to 1.8% in 2024.
One significant reason for this uptick is the subsiding of the Red Sea shipping disruption. Risks remain, but a year of intensive maritime patrols by several international naval coalitions has reduced the risk to commercial vessels. The shipping route has not seen a sinking since the first half of 2024, and there has not been a serious incident involving a Houthi strike on a vessel since September.
At the same time, logistical workarounds by the commercial transport sector have mitigated the disruption and overall risk to regional trade activity.
In terms of the hydrocarbons sector, the IMF expects the average price of oil to be $72.84 a barrel in 2025, compared to $81.29 a barrel in 2024. Alongside continuing Opec+ restrictions on oil production, this points to a slight weakening of oil revenues this year. Government spending plans among the region’s oil exporters are unlikely to be duly affected in the short term however, as such variables have already been factored into near-term expenditures.
Strong lead
The UAE tops the January 2025 MEED Economic Activity Index, with a forecast real GDP growth rate of 4.5%, broad fiscal surplus and strong non-oil growth backed by the ongoing strengthening of its projects market, which saw the award of $82bn-worth of contracts in 2024. This value exceeded project completions in the market in 2024 by almost $50bn and sits well above the long-term average.
Looking ahead, there are projects worth an estimated $8bn in the bidding phase.
Saudi Arabia’s real GDP is projected to grow by a similarly buoyant 4.6% in 2025. Although the kingdom is expected to run a fiscal deficit this year, this is largely a function of the government’s expansionary spending on strategic projects and development programmes.
Riyadh’s project spending hit new heights in 2024, with contract awards reaching a record value of $142bn and exceeding the value of project completions in the market by almost $90bn. The country also has an extraordinary $250bn-worth of project value currently under bid.
Moderate activity
Fellow GCC members Oman, Qatar and Kuwait follow in the index in a tight cluster, supported by real GDP forecasts in the 2-3% range, fiscal projections for top-line surpluses and moderate projects market activity.
Oman’s projects market is the most buoyant, with contract awards growing to $11bn in 2024 – double the $5.5bn in completions.
Qatar’s project award activity meanwhile dipped to $16bn in 2024, below the country’s long-term averages, though it still outpaced the $9bn in project completions last year.
Kuwait’s project activity grew from $6.3bn in awards in 2023 to $9bn in 2024, outpacing completions by $3.5bn and broadly matching long-term contract award averages.
All three countries have strong project pipelines, with $15bn-$25bn-worth of tenders each in the bidding phase.
Much improved
Morocco, Algeria and Iraq follow with sharply improved scores compared with mid-2024, in part due to more buoyant economic projections, including real GDP growth forecasts in the 3%-4% range in 2025.
Though weighed upon by serious fiscal imbalances, all three countries have strongly improved project markets, with contract awards surging from $2.4bn to $8bn in Morocco between 2023 and 2024, from $3.7bn to $21bn in Algeria, and from $14bn to $24bn in Iraq. The awards in all three countries also surpassed last year’s project completions and historic award averages.
Market stragglers
Bahrain comes next in the index as the lowest-performing GCC nation for reasons unrelated to its real GDP performance, which sits around 3%, but instead due to its fiscal and project sector weakness.
Manama is overspending, but not on critical infrastructure. The result is a projects sector that saw just $2.6bn-worth of awards in 2024, well below the $7.5bn in completions, which included the end of work on the $4bn Sitra Refinery, and below the $3.8bn long-term average.
The index is rounded out by Jordan, Egypt and Tunisia, whose economic situations are all fragile.
Jordan has a 2.5% growth projection, but high fiscal imbalance and unemployment. Subdued project activity in the country barely recovered to long-term averages in 2024 – after a dismal performance in 2023 – due to a $1bn liquefied natural gas terminal contract award.
Egypt, while projected for 4.1% growth in 2025, is grappling with 30% inflation, a deep fiscal deficit and a contracting projects sector. There were $19bn of awards in 2024, falling below both the 2023 figure and the long-term average for the market.
Tunisia, with a growth projection of just 1.6%, is failing across most metrics as it continues to grapple with a political and economic crisis. The country’s projects activity is no exception, with the value of contract awards in 2024 falling below 25% of the long-term average.
ABOUT THE INDEX
MEED’s Economic Activity Index, first published in June 2020, combines macroeconomic, fiscal, social and risk factors alongside data from regional projects tracker MEED Projects on the project landscape, to provide an indication of the near-term economic potential of Middle East and North African markets.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractor groups prequalify for Dubai Metro Gold Line
13 October 2026
-
 Egypt discusses technology cooperation with SLB
13 October 2026
-
 Kuwait tenders gas export pipeline
13 October 2026
-
 Developers prepare bids for 1GW Oman bess scheme
12 October 2026
-
 Frontrunner emerges for Saudi Arabia’s GCC rail link design
12 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Contractor groups prequalify for Dubai Metro Gold Line
13 October 2026
Six contracting groups submitted prequalification statements on 9 October for the contract to build Dubai Metro’s new Gold Line.
The Roads & Transport Authority (RTA) issued the request for qualification notice for the project in June, as MEED exclusively reported.
The consortiums formed to bid for the main contract are:
- Alstom / China Railway Engineering Corporation / National Projects Construction / Dogus Construction (France/China/local/Turkiye)
- CRRC / Limak / Mapa Group (China/Turkiye/Turkiye)
- Hitachi / China Harbour Engineering Company / China State Construction Engineering Corporation (Japan/China/China)
- Siemens / Petrojet / Concord Engineering & Contracting / Rowad Modern Engineering (Germany/Egypt/Egypt/Egypt)
- Hassan Allam / IC Ictas / Siemens (Egypt/Turkiye/Germany)
- Larsen & Toubro / Powerchina / Wade Adams (India/China/local)
Dubai officially announced the Gold Line in April.
In a post on social media site X, Sheikh Mohammed Bin Rashid Al-Maktoum, UAE Vice President and Prime Minister and Ruler of Dubai, said the project would cost about AED34bn ($9.2bn).
The Gold Line will increase the Dubai Metro network’s total length by 35%. The project is scheduled to be completed in September 2032.
The fully underground line will extend for more than 42 kilometres and include 18 stations. It will pass through 15 areas of Dubai and serve 1.5 million residents.
The project is expected to connect more than 55 under-construction real estate developments.
The Gold Line will begin at Al-Ghubaiba in Bur Dubai and terminate at Jumeirah Golf Estates. It will connect with the existing Red and Green lines and integrate with the Etihad Rail passenger network.
The contractor will be responsible for the design and construction of all civil works, electromechanical equipment, rolling stock and rail systems. The selected contractor will also be required to support systems maintenance and operations during an initial three-year period.
In October last year, MEED exclusively reported that the RTA had selected US-based engineering firm Aecom to provide consultancy services for the Dubai Metro Gold Line project.
Stage one covers concept design; stage two, preliminary design; stage three, tender-document preparation; stage four, construction supervision; and stage five, the defects-liability period.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20531469/main.png -
Egypt discusses technology cooperation with SLB
13 October 2026
Egypt is in talks with US-based oilfield services company SLB to expand technical cooperation in the country’s oil and gas sector, according to a statement from the Ministry of Petroleum & Mineral Resources.
Egyptian Minister of Petroleum and Mineral Resources Karim Badawi met SLB chief executive Olivier Le Peuch in Riyadh, the ministry said.
During the meeting, they discussed ways to strengthen their strategic partnership and expand cooperation in technology and digital transformation.
They also discussed how SLB could support exploration and production activities, with the aim of increasing output and attracting further investment in Egypt’s oil and gas sector.
Badawi emphasised the importance of extending the existing partnership with SLB, including its role in technology transfer and the development of technical capabilities in Egypt’s oil sector, according to the statement.
He said Egypt should build on existing areas of cooperation and deploy advanced technological solutions to reduce exploration risk, increase recovery and production rates from existing fields, and improve operational efficiency.
Badawi and Le Peuch also discussed progress on a seismic survey project being undertaken by SLB in partnership with France-based Viridien.
The project includes an ocean-bottom node seismic survey covering about 95,000 square kilometres of Egypt’s eastern Mediterranean waters.
The discussion focused on the data processing and analysis schedule, the steps required to prepare and release preliminary results, and the drilling schedule.
Badawi and Le Peuch also discussed expanding the use of horizontal drilling technologies in Egypt. This would involve identifying suitable locations and developing a commercial and contractual model for their deployment.
The Ministry of Petroleum & Mineral Resources and SLB are also exploring opportunities to expand the use of artificial intelligence in reservoir management and production optimisation.
This work is being explored in partnership with the Egyptian General Petroleum Corporation and Egyptian Natural Gas Holding Company.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20517735/main.jpg -
Kuwait tenders gas export pipeline
13 October 2026
State-owned upstream operator Kuwait Oil Company (KOC) has tendered a contract to develop a gas export pipeline.
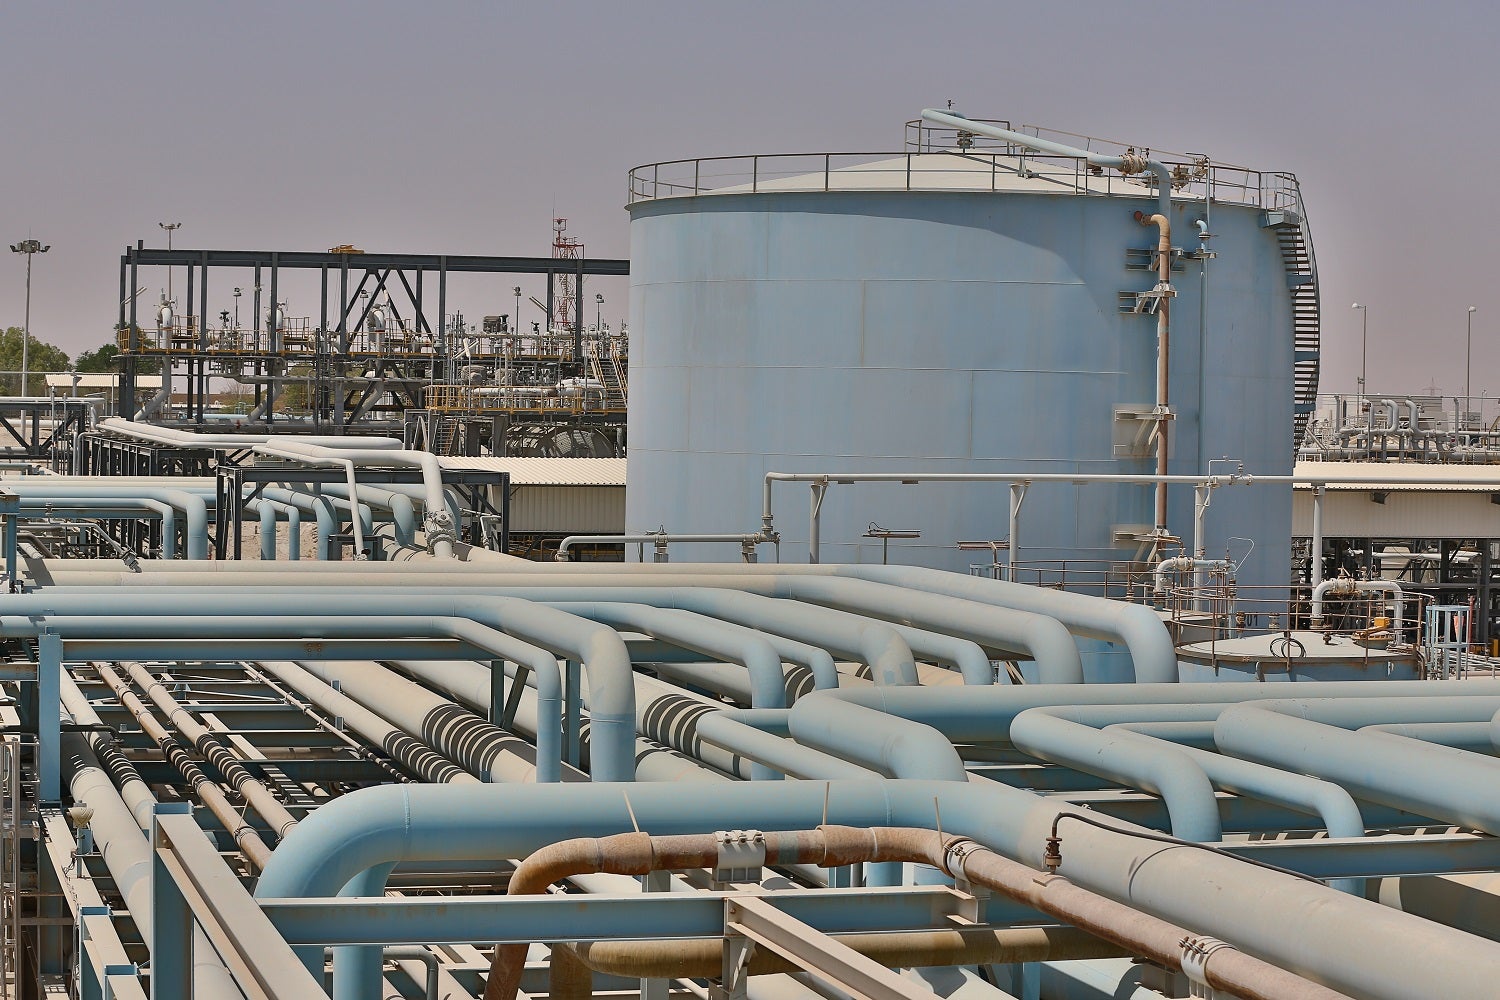
The 24-inch-diameter pipeline will extend from Booster Station 171 (BS-171) to the Intermediate Slug Catcher (ISC) facility in southeastern Kuwait, passing through the tie-in point known as TP-1.
The bid deadline is 5 January 2027. A preliminary online meeting to discuss the project is scheduled for mid-November.
BS-171 was inaugurated in February 2018. It serves as a central gas-treatment facility for gas and condensate from several gathering centres in West Kuwait and other areas.
The feeder gathering centres include GC-17, GC-27, GC-28 and GC-16.
BS-171 was Kuwait’s first facility designed specifically to handle acid gas.
The ISC facility is located about 80 kilometres from BS-171.
KOC announced plans to tender the project last year. At the time, it said that the scope would include the installation of bidirectional pig traps above the new pipeline.
A pig trap is a section of piping that enables a pipeline pig – a device used to clean, inspect or maintain a pipeline – to be launched or received.
The chosen contractor will need to provide:
- Valves
- Piping
- Fittings
- Civil services
- Structural services
- Electrical and instrumentation services
- Tie-ins
- Testing services
- Pre-commissioning services
- Commissioning services
The ISC facility is a major gas-handling facility in Kuwait’s Burgan area. It receives sour gas from West Kuwait oil fields before the gas is transported onwards to the Mina Al-Ahmadi gas-processing facilities.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20517716/main.jpg -
Developers prepare bids for 1GW Oman bess scheme
12 October 2026
Developers are preparing to submit bids for almost 1GW of standalone battery energy storage (bess) projects in Oman, a source close to the project has confirmed to MEED.
The independent power producer (IPP) scheme includes the installation of five bess facilities with a combined power capacity of 950MW and storage capacity of 3,800MWh. Nama Power & Water Procurement Company (PWP) is procuring it.
According to sources close to the project, a developer’s tender was floated in the summer. An initial bid submission deadline has since been extended, with bids expected to be submitted in the coming weeks.
The largest project is a 500MW facility in Sohar, Al-Batinah North governorate, with a storage capacity of 2,000MWh. The Sohar facility is expected to connect to the grid at 220kV. The site covers approximately 149,535 square metres.
Four further installations are planned at Al-Mabellah in Muscat governorate, Ayjah in South Al-Sharqiyah, the Jalan Bani Bu Ali wind farm site in South Al-Sharqiyah, and Sadah in Dhofar.
The Al-Mabellah and Ayjah facilities are each planned to have a capacity of 100MW and storage capacity of 400MWh. Both are expected to connect to the grid at 132kV.
The Jalan Bani Bu Ali installation is planned to have a capacity of 150MW and storage capacity of 600MWh. It is expected to connect to the Sadah wind farm and Jalan Bani Bu Ali wind farm substations.
The Sadah installation is planned to have a capacity of 100MW and storage capacity of 400MWh. It is expected to connect to the Sadah wind farm substations at 132kV.
US/India-based Synergy Consulting is the financial adviser for the procurement; Germany’s Fichtner is the technical adviser; and Germany-headquartered CMS is the legal adviser.
Utility-scale storage
In May, Oman’s Authority for Public Services Regulation (APSR) opened technical bids for a consultancy contract supporting a planned 1,000MW/four-hour bess project.
As previously reported, APSR issued the request for proposals in April as part of wider plans to increase the share of renewable energy in the sultanate.
The sultanate’s first utility-scale solar photovoltaic (PV) plant integrated with battery energy storage (Ibri 3) entered construction at the beginning of the year, comprising a 500MW solar PV plant and a 100MWh bess system.
Also in May, state offtaker Nama Power & Water Procurement Company signed a power purchase agreement with local firm O-Green for Oman’s first round-the-clock renewable energy project.
Renewable energy is expected to increase from 4% of the generation mix in 2024 to 30% by 2030, driving the push for more utility-scale storage projects.
Over roughly the same period, demand is forecast to double, reaching 10 terawatt-hours by 2031.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20511976/main.jpg -
Frontrunner emerges for Saudi Arabia’s GCC rail link design
12 October 2026
French engineering firm Systra has emerged as the frontrunner to provide design consultancy services for the Saudi Arabian section of the GCC railway network, which is intended to link all six member states.
The tender covers the concept, preliminary and issued-for-construction design stages. Saudi Arabia Railways (SAR) requires the selected consultant to review, update and complete the existing preliminary design.
Consultants submitted proposals on 14 July, as MEED reported.
The consultants who submitted bids included:
- AtkinsRealis with Khatib & Alami
- Deutsche Bahn with ARX
- Egis with Sener
- Idom with Dar Al-Handasah
- Systra
Saudi Arabia’s section of the railway will start at Al-Khafji in the Eastern Province, near the border with Kuwait, and end at Al-Batha, on Saudi Arabia’s border with the UAE.
Tendering is also ongoing for a separate contract involving design management and review to oversee engineering works on the GCC railway network.
The tender was issued on 9 September, with a submission deadline of 18 October, as MEED exclusively reported.
The tender seeks a consultant to manage, audit and verify deliverables produced by SAR’s separately appointed design services consultant, rather than carry out the design itself.
Construction will be tendered separately through competitive bidding once designs are approved.
The GCC railway will run for about 672km inside Saudi Arabia, linking the kingdom’s existing network to Kuwait, Qatar, the UAE and Bahrain, with four sections of about 141km, 200km, 151km and 21km, respectively.
The line is planned as a single-track, non-electrified corridor for mixed freight and passenger traffic, with a maximum axle load of 32.4 tonnes and passing loops for bidirectional working.
GCC railway line
Under the overall plan, the railway will run from Kuwait, pass through Dammam in Saudi Arabia, reach Bahrain via a planned causeway, and continue from Dammam to Qatar, the UAE and, ultimately, Muscat via Sohar in Oman. The railway is reported to cover about 2,186km in total.
The route length within each member state is as follows:
- UAE – 684km
- Saudi Arabia – 672km
- Oman – 306km
- Qatar – 283km
- Kuwait – 145km
- Bahrain – 36km
The railway is designed for passenger trains travelling at 220 kilometres an hour (km/h) and freight trains operating at 80km/h–120km/h.
With high levels of project activity, governments in spending mode and renewed cooperation under the Al-Ula Declaration, the latest efforts to restart the GCC railway project may make more progress than previous attempts. If completed, the railway could prove transformational for a region that is globally connected but still divided by national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20510318/main.gif