UAE lenders chart a route to growth
10 April 2023

International markets may have been spooked by challenges in the global banking system that provide an eery reminder of past problems, but UAE lenders have little reason to fear that this year will interrupt the progress seen in 2022 as profits swelled on the back of an economy in recovery mode.
Contagion fears may be misplaced. UAE banks had minimal exposure to the collapsed Silicon Valley Bank. Unlike Saudi Arabia and Qatar, there was no UAE exposure to Credit Suisse – the troubled Swiss lender swallowed up by its larger rival UBS last month.
Although UAE lending rates are not as vibrant as some of its neighbours, with nothing to rival the housing finance-linked boom in Saudi Arabia, the country’s banks have nonetheless shown some impressive performance metrics. Overall sector profits grew by 31 per cent in 2022, while assets grew by 10.6 per cent, according to figures collated by KPMG.
Profitability of the four largest lenders, First Abu Dhabi Bank (Fab), Emirates NBD, Abu Dhabi Commercial Bank (ADCB) and Dubai Islamic Bank (DIB), which control almost three-quarters of the banking system, exceeded pre-pandemic levels in 2022 – reflecting strong growth in interest income and normalised provisioning charges, according to Moody’s Investors Service.
Leading the pack, Emirates NBD showed a 40 per cent profit growth to AED13bn ($3.5bn), helped by a notably strong fourth-quarter performance that saw profits up by 94 per cent in year-on-year terms to AED3.9bn ($1.06bn) amid improving margins and a lower cost of risk.
DIB, the other Dubai lender of the big four UAE lenders, reported net profits up 26 per cent to AED5.5bn ($1.5bn), while ADCB reported a 23 per cent increase to AED6.4bn ($1.74bn). Fab, the UAE’s largest lender, had a more modest 7 per cent increase in net profits to AED13.4bn ($3.65bn).
Stabilising fundamentals
Banks can be confident that the prime source of their impressive profitability is unlikely to fade this year, given the global interest rate cycle. This continues last year’s picture. Net interest margins (NIMs) for UAE-listed banks grew 26 basis points (bps) in the fourth quarter of 2022, reaching 3 per cent for the first time, according to Kamco Invest Research.
“The interest rate environment reversed in 2022, driving aggregate growth of 28 per cent in the banks’ net interest income,” says Nitish Bhojnagarwala, senior credit officer at Moody’s.
“The growth reflected increasing asset yields, driven by rising interest rates, which more than offset higher funding costs.”
While the banks’ funding costs have increased, says Bhojnagarwala, they did not do so at the same rate, reflecting efforts to optimise their deposit mix and achieve strong zero or low-cost current and savings account balances, supporting margin growth.
NIMs should remain strong this year, not least given the continued cycle of rate rises emanating from the US Federal Reserve, which the UAE Central Bank tracks. The latter hiked its base rate by 25 bps to 5.5 per cent in March after the Fed hiked its base rate by a quarter per cent.
Some UAE lenders have also flagged priorities beyond fattening the bottom line. DIB said that given the rate environment and surplus liquidity, it had made a deliberate tactical move to support large corporate and public sector entities in adjusting and aligning their balance sheet in the new medium-term environment.
Elevated provisioning
Despite the strong conditions for profit growth, UAE banks will have a conservative strain in their approach to 2023, conscious of still elevated non-performing loan (NPL) ratios.
The big four banks’ NPL ratio declined to 5.3 per cent as of December 2022 from 5.9 per cent a year earlier.
“It remains high relative to the Gulf Cooperation Council region owing to the slower write-off policy of the UAE banks,” says Bhojnagarwala.
Coverage ratios have increased for the big four banks, standing at 100 per cent at year-end 2022, from 80 per cent a year earlier. Dubai’s ENDB was the standout bank here, with a coverage ratio of 145 per cent.
This reflects a broader tendency among banks to book higher provisions, with Dubai’s largest bank increasing absolute provisions in the fourth quarter of 2022 by $142.4m, reaching $517.9m.
Overall provisions booked by UAE-listed banks showed the biggest quarter-on-quarter percentage increase in the GCC of 40.2 per cent in the last quarter of 2022 to reach $1.23bn, says Kamco.
Moody’s anticipates loan loss provisions to stabilise at the current, pre-pandemic level and banks’ NPL ratio to improve modestly, driving higher coverage over the next 12-18 months.
“When we look at overall loan loss provisioning, it has fallen for two of the largest four banks, but in terms of cost of risk, fell by a collective 0.8 per cent from 1 per cent in 2021 and is now in line with pre-pandemic levels,” says Bhojnagarwala.
Evidence of faster payment settlements will bolster confidence levels among banks that credit losses will not rise this year. That may, in turn, afford more scope for lenders to scale back on provisioning at some point in the future.
Near future risk
Despite the improving conditions, analysts caution about potential economic headwinds.
Ratings agency S&P Global issued a warning earlier this year that real GDP growth could ease in 2023 and that the slowing of the non-oil sector will lower demand for credit. It sees the UAE property sector, which experienced strong demand in 2022 on the residential side, witnessing a moderation in price and rental increases this year.
UAE banks may need to countenance the prospect of higher problem loans in sectors such as construction and trade, as well as for some small and midsize enterprises. The latter is starting to feel the impact of more expensive credit in light of the higher interest rates.
Taken in context, this is unlikely to ruffle the Central Bank’s feathers. The country’s mix of elevated provisioning and strong profit performances suggest UAE banks will be suitably positioned to overcome such hurdles. And with healthy provisioning levels factored into the equation, the feeling remains that this year will continue the recovery record started in 2022.
This month's special report on the UAE also includes: UAE power sector shapes up ahead of Cop28

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Oman announces $790m industrial investment deals
30 October 2026
-
 Sabic swings back to profit in Q3 with $224m net income
30 October 2026
-
 H&H continues to deliver Dubai projects
29 October 2026
-
 Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
-
 Iraq oilfield water scheme to hit milestone next year
29 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Oman announces $790m industrial investment deals
30 October 2026
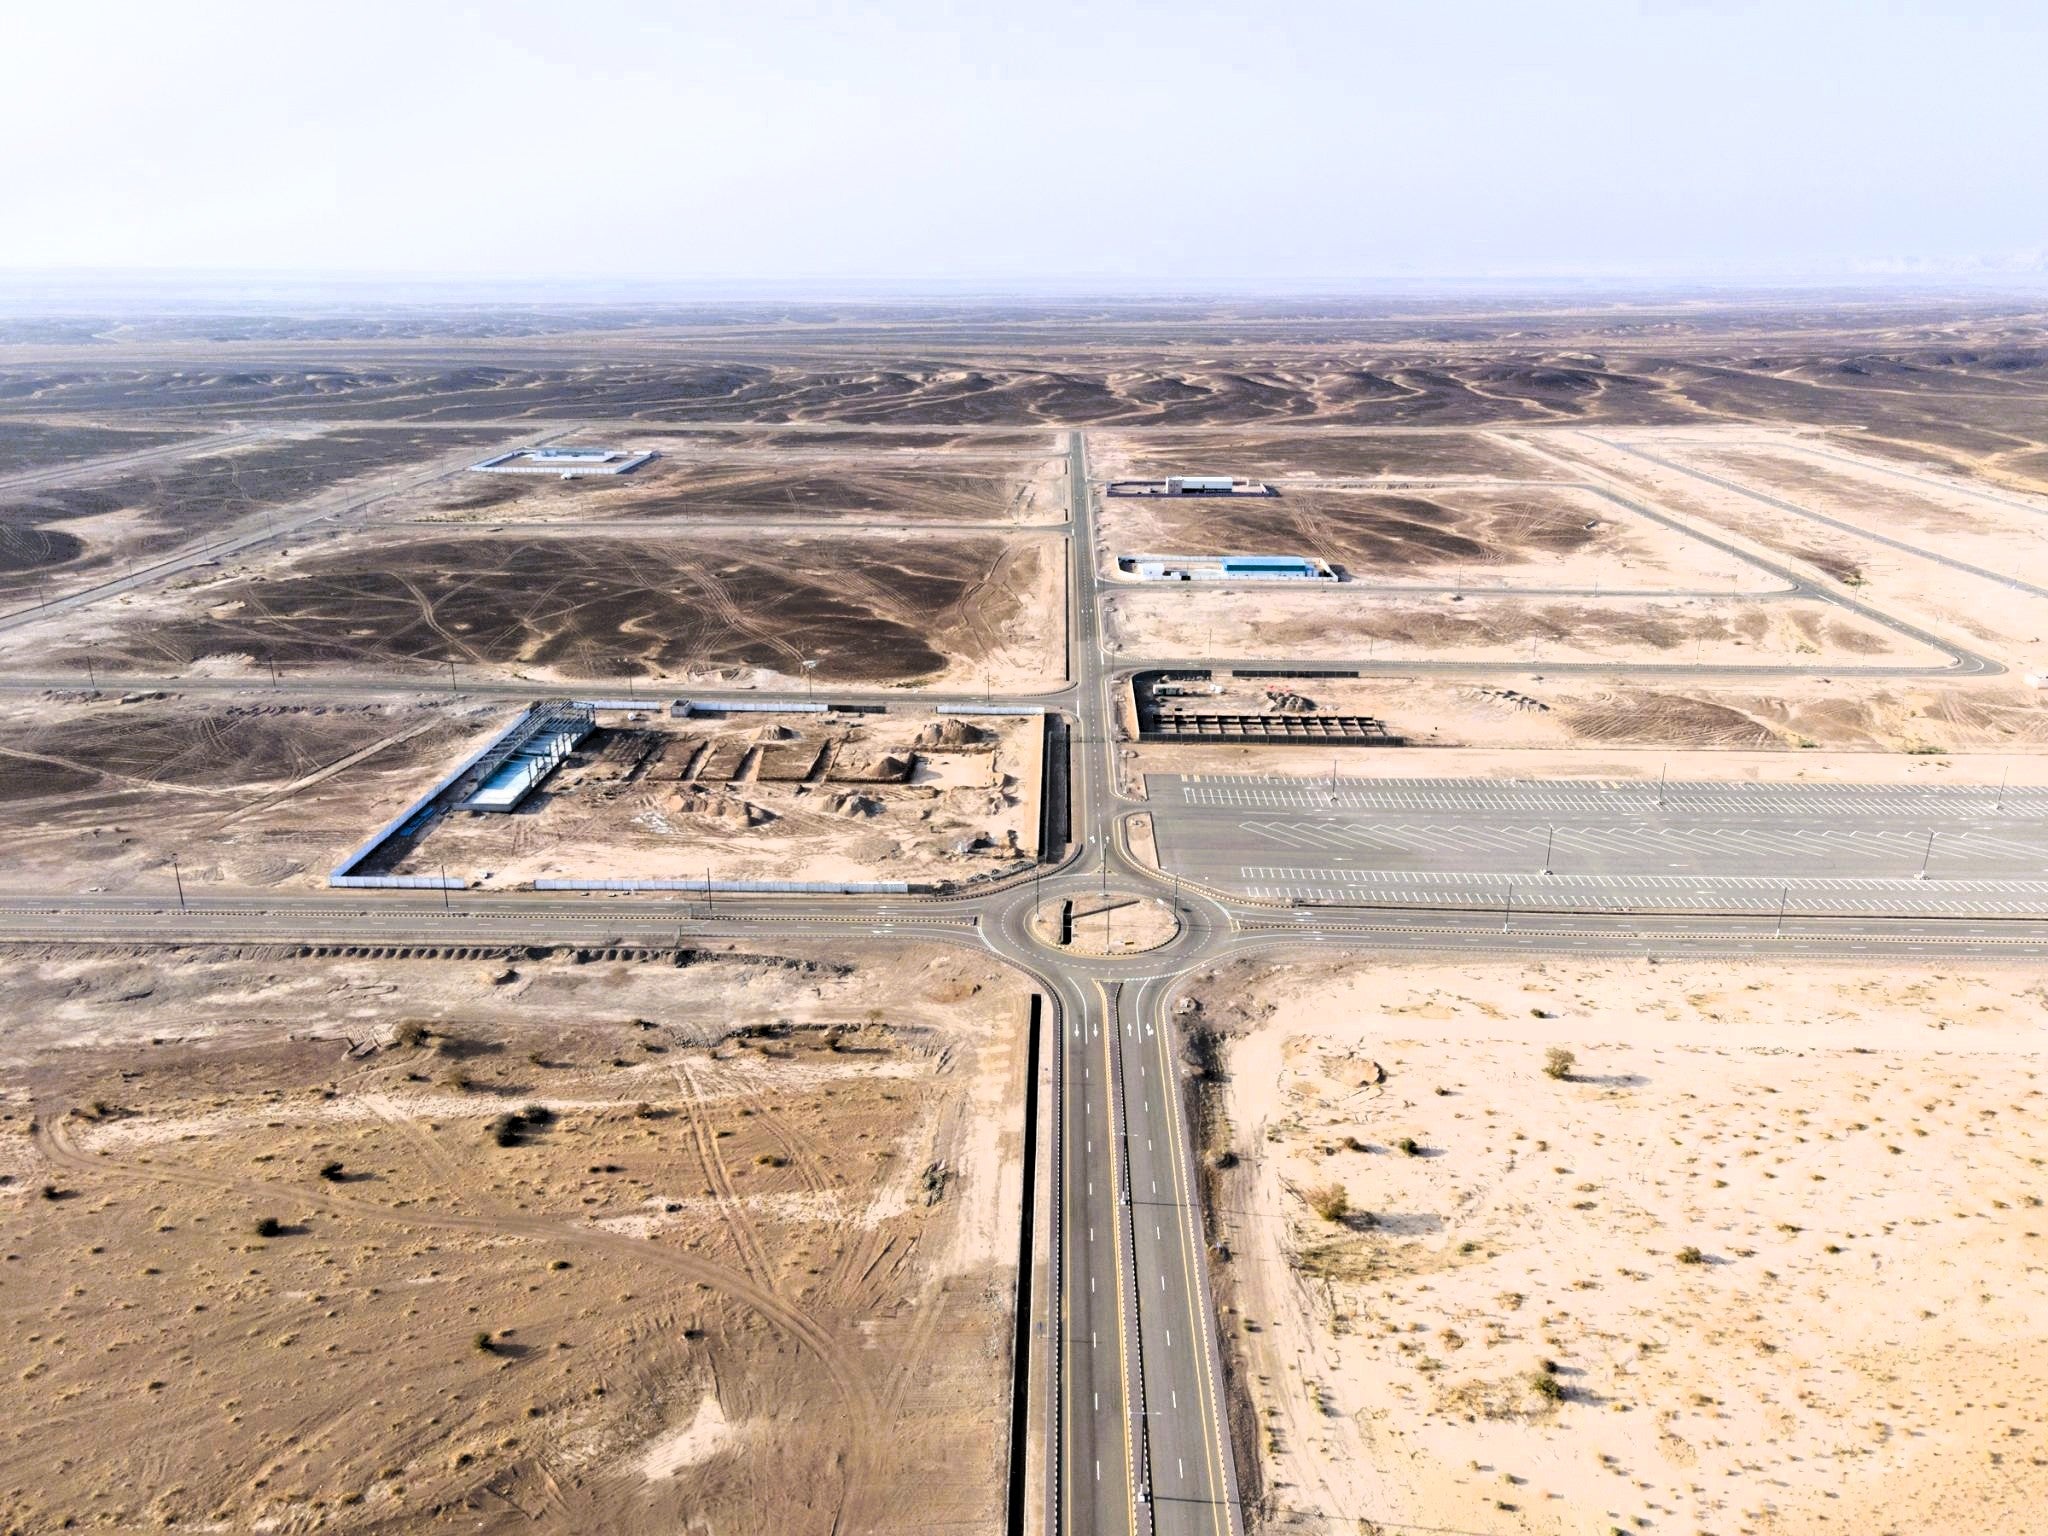
Oman’s Public Authority for Special Economic Zones and Free Zones has signed 28 investment agreements worth more than RO304m ($790m) for new projects and expansions across the country’s special economic zones, free zones and industrial cities.
The agreements cover more than 2 million square metres (sq m) of land and span industrial manufacturing, food production, logistics, recycling and commercial activities.
About $383.6m of the investment has been allocated to industrial cities operated by the Public Establishment for Industrial Estates (Madayn). Sohar Free Zone accounted for $152m, followed by the Special Economic Zone at Duqm (Sezad) with $143.1m, Salalah Free Zone with $85.6m and Khazaen Economic City with more than $27m.
The projects are expected to support Oman’s efforts to diversify its economy, expand industrial production and attract private investment in line with Oman Vision 2040.
Investment deals
In Sohar Industrial City, Atlas Steel will invest more than $291.1m in a plant producing iron and steel products on a site of about 440,000 sq m.
Fujian Mancheng Industries & Investment will invest $52m in a ceramics facility covering more than 241,000 sq m. Other investments in Madayn’s industrial cities include an $18.2m phosphate and nitrogen fertiliser plant planned by Gulf Company for Organic and Biological Fertilisers in Raysut, as well as projects involving structural metal products, paper and corrugated cardboard, and oil and gas equipment and services in Raysut, Ibri and Nizwa.
In Sohar Free Zone, Sohar Automotive & Advanced Industries Company will invest $98.8m in an automobile assembly complex covering 317,000 sq m. The complex aims to attract vehicle manufacturers, automotive supply-chain companies and advanced-manufacturing businesses.
Voltamp High Voltage Transformers has announced a $39m investment in a plant that will produce power and electrical-distribution transformers for regional and international markets.
Lalan Middle East will invest a further $3.9m to expand its medical-device manufacturing facility.
ALSO READ: Oman’s Madayn prepares $637m investment drive
In Sezad, Al-Jazir Feed Plant will invest $104m in a shrimp-feed facility to support an integrated shrimp-farming project.
In Salalah Free Zone, Al-Nawras Industries will invest $50m in a steel-structures manufacturing facility, while Integrated Gypsum Company will invest $20m in gypsum-products production. Marai Dhofar will invest $15.6m in the production of Italian cheeses and other dairy products.
Projects in Khazaen Economic City include a plant by Aleemit International Services to manufacture electric-vehicle chargers and components, with an investment of more than $8.8m, and a $6.5m facility by Joger Modular Building Technologies to produce precast-concrete building components.
Additional investments in Khazaen include construction materials, ready-mix concrete, industrial units, logistics facilities and warehouses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21016368/main.jpg -
Sabic swings back to profit in Q3 with $224m net income
30 October 2026
Register for MEED’s 14-day trial access
Saudi Basic Industries Corporation (Sabic) returned to profitability in the third quarter of the year, reporting adjusted net income of SR840m ($224m) as revenue and earnings improved from the previous quarter.
The Saudi chemicals giant had posted an adjusted net loss of $100m in the second quarter.
Revenue increased 14% on a quarter-on-quarter basis to $7.51bn, while adjusted earnings before interest, taxes, depreciation and amortisation (Ebitda) climbed 40% to $1.27bn. Adjusted Ebitda surged 434% to $578.67m.
Sabic’s net debt stood at $808m as of 30 September compared with $728m as of 30 June.
Adjusted earnings per share rose to SR0.28 ($0.07) from a loss of SR0.13 ($0.03).
The recovery occurred despite persistent margin pressure across the global petrochemicals sector and heightened geopolitical risk in the Middle East.
Additionally, Sabic said it achieved $949.33m of its broader portfolio optimisation programme target of $3bn by 2030 in positive recurring Ebitda impact from its transformation efforts.
During the third quarter, Sabic received its Local Content Certificate for 2025 from the Local Content and Government Procurement Authority, recording a score exceeding 61% – an increase of more than nine percentage points over the prior evaluation period. The company attributed the increase to domestic procurement agreements, including a memorandum of understanding with Lenovo.
Capital projects
After several years of subdued project spending, Sabic is beginning to step up investment in new production capacity, with major projects reaching key milestones this year.
In February, affiliate Petrokemya awarded China National Chemical Engineering Group Corporation the main engineering, procurement and construction (EPC) contract for a new ethylene oxide catalyst production facility. The 4,000-tonne-a-year (t/y) unit at Jubail Industrial City includes catalyst carrier washing, drying facilities and associated utilities.
Major ammonia-urea complex
In September, Sabic Agri-Nutrients awarded South Korea’s Samsung E&A a $3.465bn EPC contract for its seventh production complex in Jubail Industrial City (San VII).
The project will have an annual capacity of approximately 1.2 million metric tonnes of conventional ammonia and 2.6 million tonnes of urea, integrated with a post-combustion carbon-capture unit.
The Ministry of Energy approved feedstock allocation for the project in March. San VII will expand the company’s total urea capacity by 54%, from approximately 4.8 million t/y to 7.4 million t/y.
The development reflects a shift in project scope. Originally conceived as San VI – a low-carbon facility designed to yield 1.2 million t/y of blue ammonia alongside specialised nutrients – the scheme was re-engineered as a conventional ammonia and urea plant using carbon-capture systems to manage emissions intensity.
Construction is scheduled to begin in the fourth quarter of 2026. Commissioning is slated for the third quarter of 2030, with full commercial operation targeted before year-end 2030.
Sabic Agri-Nutrients positions the project as central to its 2040 strategy to expand export market share and support international supply chains.
Greenfield methanol plant
San VII is not the only major project moving forward.
Also in September, Sabic subsidiary Saudi Methanol Company (Ar-Razi) secured feedstock approval from the Ministry of Energy to build a 1.8 million t/y greenfield methanol plant in Jubail.
The project aligns with Sabic’s focus on scale in core petrochemical chains and provides intermediate feedstock for expanding domestic downstream manufacturing.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21015944/main2510.jpg -
H&H continues to deliver Dubai projects
29 October 2026
Dubai-based developer H&H has launched Water Gardens, a mixed-use development in Dubai International Financial Centre (DIFC), and expects to award most of the construction contracts for its wider pipeline before summer 2027.
Water Gardens comprises four buildings designed by UK architect David Chipperfield, arranged around a central garden and pedestrian-friendly public realm. The scheme combines offices, residences, hospitality and retail offerings, including the Four Seasons Private Residences Dubai at DIFC and residences under H&H’s Eden House brand.
 Construction is under way, and the developer says the project is scheduled for completion in 2028. DIFC Investments describes it as one of the final components of the original Gate District masterplan.
Speaking to MEED at the launch, H&H chairman Shahab Lutfi said the office building and Eden House are due for completion in about 18 months. The Four Seasons residences are scheduled for delivery at the end of 2028, with a five-star hotel following later.
Water Gardens is one of several projects H&H has under way. The company undertakes a selective portfolio of high-end real estate developments in prime locations in Dubai. These include the Carlyle Residences in DIFC; an Eden Hills villa community in Mohammed Bin Rashid City; and Dubai Peninsula, a waterfront scheme in the Jumeirah area that will include hotels operated by Aman and Rosewood.
“We are awarding day in, day out,” says Lutfi. “I think we are awarding most of our contracts from now until summer next year.”
Most of the company’s construction volume is in DIFC and Dubai Peninsula, with the Eden Hills villas accounting for a smaller share. Lutfi says H&H is talking to several of the emirate’s biggest contractors about upcoming packages.
We are awarding [contracts] day in, day out
Staged procurement
H&H is managing cost pressures by splitting up its procurement. It awards main contracts covering concrete works with a large number of provisional sums, then tenders further packages as designs are completed. “We are taking on some of the risk, but we know how to manage the risk instead of just offloading it on the contract,” says Lutfi.
He does not expect construction costs to fall in the next 12 months. Global inflation, driven by fuel prices and logistics costs, is already factored into the company’s plans.
“Waiting and trying to award at a cheaper price is not an option for us,” he says.
Lutfi says rising costs need not erode margins for developers that keep unsold stock to sell at higher prices later in a project. Developers that sell out early are more exposed. “If you have already sold out two years ago, you are hurting your profitability,” he says.
H&H is comfortable leaving 15%-20% of a project to sell on completion. The market usually expects developers to sell out before handover.
The company has not revised its masterplans or product mix in response to market conditions and continues to focus on large units.
Supply chains have been a challenge this year, but Lutfi says the company is over that hurdle. H&H has sourced more materials locally and planned logistics further in advance.
Materials are reaching Dubai through bonded routes from Oman, Fujairah and Khor Fakkan in the UAE, and Jeddah in Saudi Arabia.
“It takes a little bit longer, but at least things are coming in,” he says.
H&H relies on a relatively small group of contractors that work on most of its projects, and treats them as long-term partners.
Lutfi says contractors are attracted by the company’s financial stability and volume of work. “That can keep some people busy for the next five or six years,” he says.
Lutfi notes that sales in the Dubai market have dropped, although enquiries have picked up since the summer as buyers weigh whether it is the right time to purchase. The distressed sales that some had expected have not materialised.
“A 5% discount in some units is not really a distress sale,” he says. “It is just someone trying to get a discount because of the region’s situation, which actually builds confidence.”
For Water Gardens, H&H has sold 85% of Four Seasons Private Residences Dubai at DIFC since sales began in 2024. The company launched sales at the Carlyle Residences before the regional disruption and has since sold units one-to-one to selected clients. More Four Seasons units have been sold in the past two weeks.
“Branding makes a big difference,” says Lutfi.
The company markets its branded residences through a global network of brokers rather than via public campaigns or launch events. Eden Hills, which is aimed mainly at Dubai residents, is marketed more widely.
Lutfi expects buyers to be more cautious about buying off-plan. H&H is building new sales centres at Dubai Peninsula and in DIFC so that clients can see the product before they commit.
“People have to come in, know exactly what they are buying, and they will feel comfortable paying the price – instead of just having a pretty brochure,” he says.
He expects demand for villas to become more local and regional, while branded residences will continue to attract international buyers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21012636/main.gif -
Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
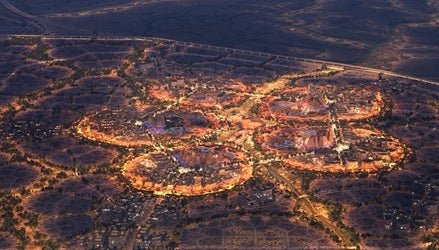
Expo 2030 Riyadh Company (ERC), responsible for delivering the Expo 2030 Riyadh venue, has allowed contractors until 11 November to submit bids for a contract to deliver the Souq areas within the Expo site.
The tender was floated on 30 July, with an initial submission deadline of 9 October.
The Souq areas are divided into five distinct precincts, with a total development area of about 300,000 square metres (sq m).
The scope includes the five precincts and their associated vertical elements, infrastructure and public realm works.
The precincts comprise:
- Precinct 1 – The Icon: 41,417 sq m
- Precinct 2 – Place & Planet: 62,306 sq m
- Precinct 3 – Culture of Wisdom: 67,112 sq m
- Precinct 4 – Kingdom of Saudi Arabia: 45,967 sq m
- Precinct 5 – Adaptation & Innovation: 82,358 sq m
The package will interface with three public parks. It will also tie into the Natural Corridor, including bridges.
The Souq areas will form a mixed-use destination at the centre of Expo 2030 Riyadh, connecting the site’s iconic and thematic assets.
The development will include rented and partnership pavilions, alongside a range of food and beverage, retail and visitor-experience offerings.
Site progress
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to build a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts to local firm Al-Yamama Company for the next phase of infrastructure works at the site.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, and electric vehicle charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20998514/main.jpg -
Iraq oilfield water scheme to hit milestone next year
29 October 2026
China Petroleum Pipeline Engineering (CPP) expects to start laying pipeline for Iraq’s Common Seawater Supply Project (CSSP) in Basra in mid- or late next year, according to industry sources.
The project is behind schedule, partly because importing sections of pipeline is proving challenging due to disruptions to shipping through the Strait of Hormuz.
The project is being managed by state-owned Basra Oil Company (BOC), with Australia’s ILF acting as a project management consultant after completing the front-end engineering design (feed).
Under current plans, the pipelines will be buried, which is expected to make them more secure than if they were installed on the surface.
Phased development
The client for the first phase of the CSSP is France’s TotalEnergies in partnership with QatarEnergy and BOC.
The first phase is split into two packages currently under execution and will ultimately have the capacity to transport 5 million barrels a day (b/d) of water.
The first package focuses on developing pipelines, and the second on developing a water treatment facility.
CPP is executing the pipeline package contract.
It signed a $2.5bn contract with BOC for the package in September last year.
Also in September 2025, South Korea’s Hyundai announced that it had signed a contract worth 4.39tn won ($3.16bn) for the processing plant package.
In September this year, MEED reported that early groundworks had started for both packages of the first phase of the CSSP.
Phase one of the project is scheduled to start up in late 2028 or early 2029.
Earlier this month, US-headquartered Exxon Mobil signed a memorandum of understanding related to the project’s second phase, which is expected to add 2.5 million b/d of water capacity.
The CSSP will inject processed water into several of Iraq’s biggest oil fields. These include Rumaila, Zubair, West Qurna 1, West Qurna 2 and Majnoon. Water from the project will also be used in the Maysan and Dhi Qar fields.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20981033/main.jpg