UAE economy regains regional lead
29 May 2024

The UAE has edged ahead of Saudi Arabia again to take the lead in the MEED Economic Activity Index, which assesses the near-term economic health of regional markets, as a gap has opened up between the economic and fiscal performances of the two countries in 2024 to date.
Saudi Arabia and the UAE entered 2024 with similarly buoyant 4% real GDP growth projections from the Washington-based IMF, but have since diverged. In April, the IMF revised its growth forecast for the UAE to 3.5%, and the forecast for Saudi Arabia 2.6%.
The World Bank has meanwhile maintained a more optimistic 3.9% real GDP growth projection for the UAE in 2024, but an even lower projection of 2.5% for Saudi Arabia.
The trade and fiscal balance performances of the two countries have also diverged. The UAE is forecast for a 7.8% of GDP current account surplus and 4.5% of GDP fiscal surplus, while Saudi Arabia’s current account surplus has narrowed to 0.5% of GDP, while its budget has slipped into a 2.8% deficit.
Oil price impact
Saudi Arabia’s reduction in its growth and slide into fiscal deficit have both partially been brought about by the impact of softer oil prices and Opec-led production cuts, which have naturally hit the more heavily oil-dependent Saudi economy to a greater extent than the more diversified UAE economy. The UAE Central Bank is forecasting a non-oil GDP growth rate of 4.7% for the country in both 2024 and 2025.
Together, the two countries remain comfortably in the lead at the top of the index, due in large part to the buoyancy of both of their projects markets. Contract award values in the past 12 months for both countries were double the long-term average, while new work outstripped completed work twofold in the UAE and fourfold in Saudi Arabia.
Wider market
Elsewhere in the GCC, Qatar and Oman have both seen their real GDP growth slip in 2024, to 2% and 1.2%, respectively – driven by slight weakness in both the hydrocarbons and non-hydrocarbons sectors. Both countries remain in fiscal surplus, however, and have stable projects markets, with work being tendered at or above the long-term average award values and above the rate of completion.
Kuwait is projected to see its GDP contract for the second year in a row as a weaker oil market and production cuts hit hard. Kuwait is the most heavily oil-dependent and least diversified country in the region, with 95% of exports and 90% of government revenue coming from the oil sector, making the country and its real GDP metric highly sensitive to fluctuations in the oil price – though it still has a fiscal surplus. At the same time, the country’s projects market also continues to underperform, with contract awards 40% below the long-term average and 25% below the rate of completion.
Algeria has meanwhile risen up the ranking and boasts a forecast of 3.8% real GDP growth in 2024 – the strongest in the region, according to the IMF. While it is still expected to remain deep in fiscal deficit, inflation is on a downward trend, and the projects market has above-average contract award activity.
Bahrain, despite a projected 3.6% growth rate in 2024, remains in concerning fiscal and debt positions. Its short-term risk rating was recently elevated to the second-highest level by insurance group Allianz. The Bahraini projects market is also in steep decline, with the value of contract awards in the last 12 months coming in at just over a third of the long-term average and at little more than half the level of project completions.
Morocco, Jordan and Egypt are all expected to experience moderate 2-3% real GDP growth rates this year, while continuing to struggle with persisting current account and fiscal deficits. All three countries also have elevated unemployment and government debt, as well as underperforming projects markets, with awards over the past 12 months at two-thirds or less of long-term historic averages.
Iraq is another country with high oil market dependence and oil price sensitivity and is forecast for just 1.4% real GDP growth this year. Short-term risk in the country is also in an elevated state amid political turbulence and weaknesses in the security situation that have seen repeated attacks by non-state actors on oil sector infrastructure. The projects market nevertheless remains nominally steady for now, with sustained award activity at the level of long-term averages and also at the rate of project completions.
Tunisia has sunk to the bottom of the index with a weakened 1.9% growth rate in 2024 and an even lower growth projection of 1.8% in 2025 as the country continues to be caught up in political chaos and an economic crisis. Short-term risk is high, as are the rates of unemployment and inflation. The projects sector is reasonably active, but contract awards remain below the long-term average.
ABOUT THE INDEX
MEED’s Economic Activity Index, first published in June 2020, combines macroeconomic, fiscal, social and risk factors alongside data from regional projects tracker MEED Projects on the project landscape, to provide an indication of the near-term economic potential of Middle East and North African markets.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
-
 Sultan Al-Jaber appeals for global energy security reset
2 November 2026
-
 Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
-
 Contractors prepare bids for Morocco power line
2 November 2026
-
 Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
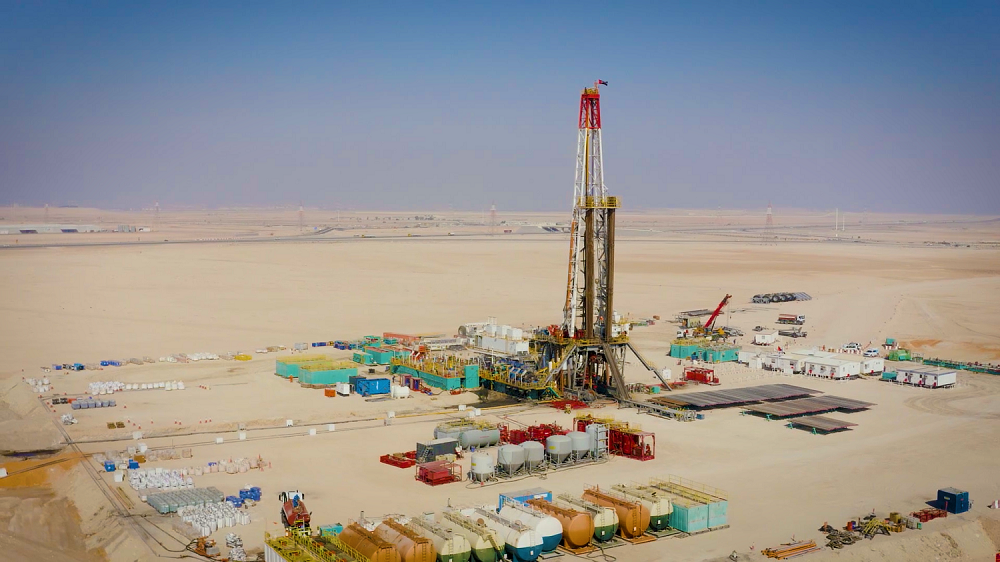
Adnoc awards contract for Ruwais Diyab unconventional gas
3 November 2026
Abu Dhabi National Oil Company (Adnoc) has taken the final investment decision (FID) for the Ruwais Diyab unconventional gas development in Abu Dhabi.
The project will deliver 345 million standard cubic feet a day (scf/d) of raw gas from 2029 over a 25-year period, with the potential to reach up to 1 billion scf/d in the future.
Gas will be processed on site and connected to the UAE’s gas network through new pipeline infrastructure, “strengthening domestic supply, supporting the nation’s economic and industrial growth as well as Adnoc’s liquefied natural gas export ambitions”, the Abu Dhabi energy giant said when announcing FID on the project at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026.
According to sources, Adnoc has awarded the design, build and operate (DBO) contract for the Ruwais Diyab unconventional gas development to China-based Jereh Group.
A formal kick-off meeting between Adnoc and Jereh is expected to take place later in November, sources told MEED.
The DBO contract awarded by Adnoc to Jereh is understood to cover the second phase of the Ruwais Diyab unconventional gas development. The tendering exercise for the project started last year.
“The development [of Ruwais Diyab] follows a disciplined programme of technical studies, field testing and subsurface analysis, delivered by Adnoc Onshore under a DBO model, to reduce development risk,” Adnoc said in its statement on 2 November.
“It brings together advanced subsurface expertise, artificial intelligence-enabled drilling and completion technologies and integrated project delivery capabilities to support the efficient and responsible development of domestic gas resources,” it added.
The UAE holds the seventh-largest gas reserves in the world, with 298 trillion standard cubic feet (scf) of conventional gas reserves and 160 trillion scf of unconventional gas resources.
Adnoc holds the majority 60% stake in the Ruwais Diyab concession, the majority of which is situated onshore, while France’s TotalEnergies holds the other 40% interest.
The agreement to explore, appraise and develop the area’s unconventional gas resources was signed by Adnoc and TotalEnergies in November 2018. The partners announced first gas output at the concession, presumably on a pilot basis, two years later.
Adnoc has set a target of producing 1 billion scf/d of gas from the Ruwais Diyab concession by 2030, in line with its target to achieve self-sufficiency in overall gas production by the end of this decade.
“Ruwais Diyab’s additional unconventional gas supply will strengthen Adnoc’s gas value chain, including Adnoc Gas’s ability to meet rising domestic and international customer demand,” Adnoc said in its 2 November statement.
“Ruwais Diyab advances Adnoc’s ambition to establish a scalable unconventional gas business and create a platform for future growth,” the company added.
Ruwais Diyab first phase
Adnoc awarded the contract for engineering, procurement and construction (EPC) on the first phase of the unconventional gas development programme to local contractor Astra Engineering & Construction in early 2025, according to regional project tracker MEED Projects.
The first phase aims to achieve a gas output level of 100 million scf/d. The main structures to be built in the first phase include a central processing facility, two well pads, interconnecting well fluid pipelines, gas export pipelines and tie-in stations.
The EPC contractor will be required to provide services such as surveying, design, engineering, procurement, expediting, transportation, fabrication, construction, testing, installation, pre-commissioning, commissioning, site performance testing, operation and maintenance of all units.
The duration of the EPC works is understood to be 20 months, with the contractor also responsible for operating and maintaining the phase one facilities for 15 years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21100974/main4351.png -
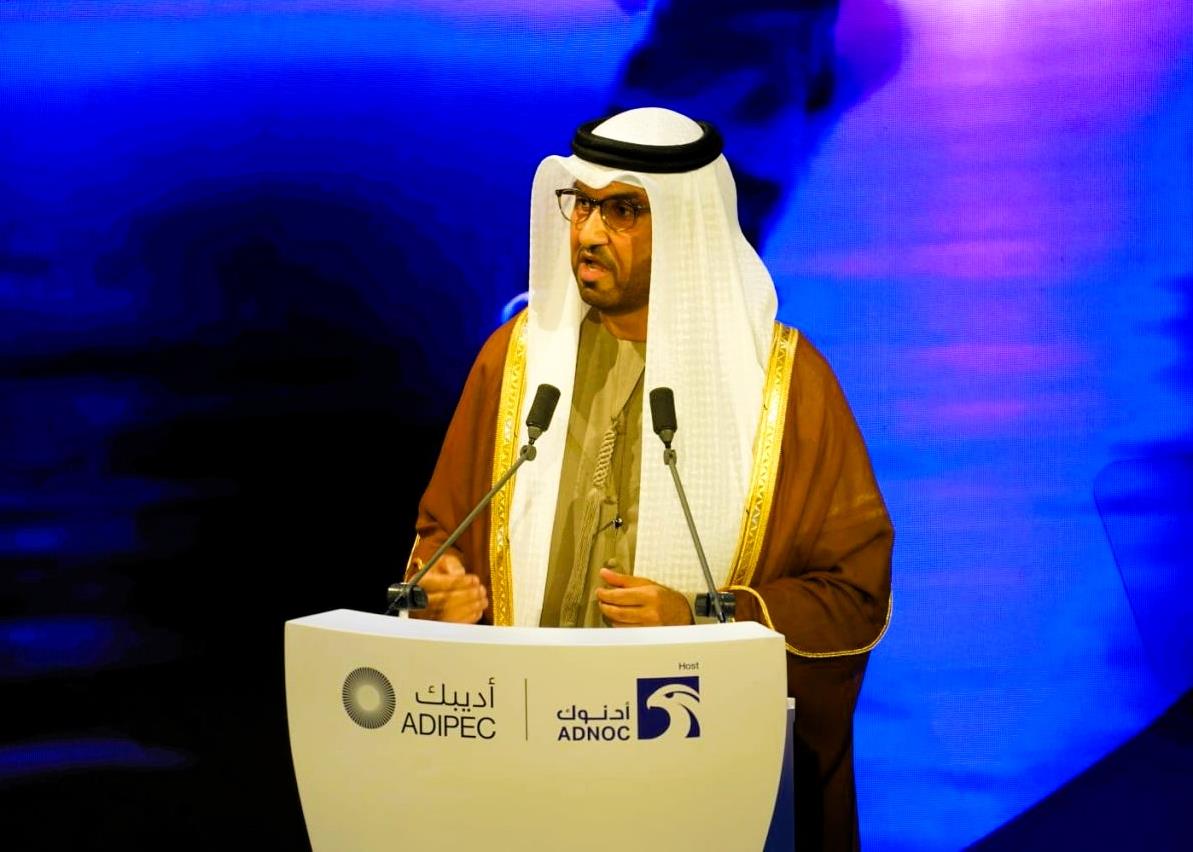
Sultan Al-Jaber appeals for global energy security reset
2 November 2026
The global energy industry must fundamentally rethink how it builds, protects and delivers secure energy, following a year of unprecedented disruption that has exposed critical vulnerabilities in international supply chains, Sultan Ahmed Al-Jaber, the UAE’s Industry & Advanced Technology Minister and managing director and group CEO of Abu Dhabi National Oil Company (Adnoc Group) has said.
Delivering the opening address at the Abu Dhabi International Petroleum Exhibition and Conference (Adipec) 2026 on 2 November, Al-Jaber said preparedness is essential to navigating an increasingly uncertain global landscape.
“For decades, energy security was a question for specialists. It was debated in rooms like this, by people like us, in a language that few needed to learn. This year, every family, every farmer, every industry and every business owner is asking about it, and our collective job is to find the answers.”
Noting that it is not possible to control every situation and remove every risk, Al-Jaber said: “The choices we make today will determine the energy landscape a decade from now. Let’s apply the lessons we have learnt. Let’s build capacity and everything that supports it. Let’s forge partnerships that hold when it matters. And if you want a partner you can count on, you are in the right room, in the right city, in the right country. Because when it counts the most, you can count on the UAE.”
Setting out the case for a more resilient energy system, Al-Jaber said that since the disruption in the Strait of Hormuz, nearly 1 billion barrels of crude have been drained from inventories. He noted that in some markets, stocks of diesel are at their lowest seasonal level in 35 years, while others are facing a supply gap for liquefied natural gas (LNG) of 600 billion cubic feet. “Simply put, the world has eroded its supply buffers,” Al-Jaber said.
“But supply is only half the story. The other half is delivery. Before the disruption, logistics were less than 5% of the cost of a barrel. Today, they are more than 30%. In short, energy security is not only measured at the point of production. It is now also measured at the point of delivery.”
Mitigation steps
Al-Jaber outlined five steps the energy industry can take to reduce the impact of future shocks. “First, accessible supply. We need expanded strategic storage, larger stockpiles of products and flexible refining capacity closer to consumer markets.
“Second, routes to market. Supply only counts when it arrives. Infrastructure must be built before it is needed and enabled by advanced logistics.
“Third, operational intelligence. Moving from automated operations to intelligent energy systems that anticipate risk, optimise performance and drive down the cost of every barrel.
“Fourth, capital follows confidence. Policy must create it, finance must accelerate it and insurance must keep trade moving.
“Fifth, which is in my view the most important, is people. Because behind every barrel that arrives is a person who made sure it did. Systems don’t carry responsibility, people do.”
Photo credit: Adipec via LinkedIn
https://image.digitalinsightresearch.in/uploads/NewsArticle/21091189/main2954.jpeg -
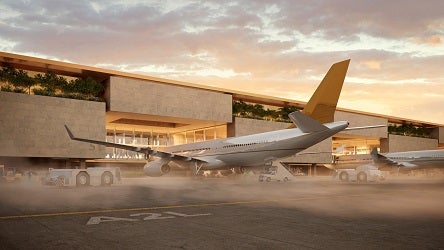
Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
Contractors are preparing bids for the main construction contract for Terminal 6 at King Salman International airport (KSIA) in Riyadh.
MEED understands that the consortiums have been given until 30 December to submit their proposals.
The participating consortiums are:
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
Last month, MEED exclusively reported that contractor teams have completed the early contractor involvement phase of the project.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
King Salman International Airport Development Company (KSIADC) is a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May 2025, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21087339/main.jpg -
Contractors prepare bids for Morocco power line
2 November 2026
Contractors are preparing bids for a 160-kilometre (km), 400kV transmission line linking Guercif and Fes East in Morocco, following a site visit on 1 October.
The project is being developed by the Office National de l'Electricite et de l'Eau Potable (Onee) to connect the Saka solar photovoltaic power plant to the national electricity grid.
According to sources, at least eight contractors attended the site visit last month, including:
- Butec (Lebanon)
- CEEC Northeast Electric No.2 (China)
- Cegelec (France)
- EPME Electric (Morocco)
- Hideleco (Egypt)
- Kec International (India)
- PowerChina (China)
- Transrail (India)
The project comprises two lots. The first involves a 90km transmission line between Guercif and Taza, while the second covers a 70km section between Taza and Fes East.
The scope of work includes the construction of tower foundations, installation of transmission supports and conductors, and associated high-voltage equipment. It also includes optical fibre cables for communications and monitoring, access roads and other supporting infrastructure.
The tender was issued in September with bids originally due by 21 October. The deadline has now been extended to 25 November.
The project is part of a wider programme by Onee to expand Morocco's electricity transmission network and accommodate additional renewable energy capacity.
In June, the utility commissioned a 274km, 400kV transmission line linking Chemaia and Mediouna, near Casablanca.
Onee plans to expand its high- and extra-high-voltage transmission network from more than 30,700km to 37,000km by 2030.
In August, it approved a $26.4bn investment programme for the 2026-30 period, covering electricity and drinking water infrastructure.
The programme has allocated about $21.9bn to electricity projects and $4.5bn to drinking water infrastructure, with about 72% of the investment to be financed by the private sector, according to Onee.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083507/main1257.jpg -
Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
The onshore business of Abu Dhabi National Oil Company (Adnoc Onshore) has allowed contractors more time to prepare proposals for a project to tie in gas-producing and injection wells at the gas cap reservoirs of Abu Dhabi’s onshore Bab field.
The well tie-in scope, estimated to be worth more than $800m, forms part of Adnoc Group’s wider integrated Bab gas cap development programme.
The overall programme is being led and overseen by Adnoc Gas, another Adnoc Group subsidiary. Its central element is the construction of gas-processing infrastructure to handle incremental gas output expected from developing the Bab gas caps.
Adnoc Onshore issued the main tender for engineering, procurement and construction (EPC) works on the project in late September, MEED previously reported.
Contractors have been given until 16 November to submit technical bids for the project, according to sources. The previous deadline was 29 October.
MEED previously reported that Adnoc Onshore issued an expressions of interest (EoI) notice for the Bab gas production and injector well tie-in project on 13 May, with contractors submitting responses by 20 May.
The scope of work on the project covers the following:
- Tie-in of 99 new wells from Bab gas cap reservoirs KH-2, SH-1 and LK-1 (60 gas producers and 39 gas injectors);
- Installation of well gathering structures: 10 gas pads, six well bays and three virtual pads;
- Installation of a gas gathering network and a gas injection network;
- Rerouting of the LK-3 production from the existing trunkline in Remote Manifold Station 3 (RMS-3) to the project’s production trunkline, Bab Gas TL-2;
- Demolition of the existing 10-inch trunkline from RMS-3 to onshore gas development phase one.
In the EoI document, Adnoc Onshore said it intends to award the EPC contract in the last quarter of the year, with a 45-month duration of works.
Bab gas cap project infrastructure
As part of its 2030 upstream production increase goals, Adnoc Group is working to extract gas from four underdeveloped gas cap reservoirs at the Bab onshore field development – Thammama A, Thammama B, Thammama F and Thammama H.
While the Thammama A, B and H reservoirs are estimated to collectively produce 1.45 billion cubic feet a day (cf/d) of gas, output from the Thammama F gas cap is expected to be at a rate of 396 million cf/d.
Existing trains at the Habshan processing complex in Abu Dhabi will be unable to handle the new gas volumes. Therefore, Adnoc Gas is required to build new facilities to process an additional volume of up to 1.85 billion cf/d of raw gas.
Adnoc Gas is planning to build a gas processing plant in the Bab area, about 170 kilometres from Abu Dhabi, along with associated pipeline networks and other ancillary units, as part of the broader Bab gas cap development project. It has divided the EPC scope of work on the project into four packages:
- EPC package 1 – Main Bab gas cap plant
- EPC package 2 – Early civil works
- EPC package 3 – Pipelines
- EPC package 4 – Non-process area works
Abu Dhabi Securities Exchange-listed Adnoc Gas issued the tender for the main Bab gas cap plant on 25 June and set an initial deadline of 17 July for contractors to submit technical bids. The company then extended the technical bid submission deadline by four months, until 16 November, MEED previously reported.
Following a reshuffle of the consortiums gearing up to bid for the main Bab gas plant EPC package, estimated to be worth more than $6bn, the following teams have formed to compete in the main contract tendering round:
- Larsen & Toubro Energy Hydrocarbon (India) + Petrofac Emirates (UAE)
- Technip Energies (France) + JGC Corporation (Japan) + Sinopec (China)
- Tecnimont (Italy) + China Petroleum Engineering and Construction Corporation (CPECC)
The other three packages of the Bab gas cap project are also in the main contract tendering stages.
Prior to issuing the EoIs for the project packages, Adnoc Gas completed an early engagement process with contractors in September and October last year, as MEED previously reported.
In December last year, Adnoc Gas awarded the front-end engineering and design (feed) works for the development project to Australia-based consultancy Worley. The feed contract has a duration of more than 1.2 million man-hours, making it the largest-ever engineering job awarded by Adnoc Gas.
Bab Gas Cap concession
In addition to Adnoc Gas overseeing the main EPC tendering exercise for the gas processing plant, Abu Dhabi’s Supreme Council for Financial and Economic Affairs (SCFEA) awarded concession agreements in June for the development and production of the Bab gas cap reserve.
Adnoc will hold the majority 60% participating interest in the concession. The remaining stakes will be held by France’s TotalEnergies (10%), the UK’s BP (10%), China National Petroleum Corporation International (8%), Japan Oil Development Company Onshore (5%), China ZhenHua Oil (4%) and Korea GS E&P (3%).
According to the SCFEA, the Bab gas cap development and production concession represents the largest gas cap development project of its kind globally, the Abu Dhabi Media Office said in a report.
A gas cap refers to the free natural gas that sits above an underlying oil reservoir – in this case, the Bab onshore oil field in Abu Dhabi.
The project, operated by Adnoc Onshore, is expected to have a production capacity of approximately 1.5 billion cf/d of natural gas, equivalent to about 15% of Adnoc Gas’ total operational gas processing capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083343/main.jpg