Trump factor weighs on the region’s economies
2 January 2025

If 2024 was a slow road back to stabilisation for economies in the Middle East and North Africa (Mena) region, with lower interest rates and generally improved fiscal positions providing some ballast against tumultuous geopolitical risk events, the coming year portends yet more instability with the return to the White House of Donald Trump. This will, for good or ill, have a decisive impact on the region’s economic trajectory.
 The region is looking at a more rapid economic growth rate in 2025 than the previous year. The World Bank, which estimated real GDP growth in the Mena region of 2.2% in 2024, sees region-wide growth at 3.8% in 2025, with Gulf economies driving this improvement.
This reflects the gradual phasing out of voluntary oil production cuts starting from December 2024.
Mena oil importers will see real GDP growth expand from just 1.3% in 2024 to 3.4% in 2025, says the World Bank.
Interest rates are a key ingredient in the mix, linking to the second Trump presidency, with its likely ramp-up of global trade-war pressures.
If the president-elect follows through on his tariff plans, which range from a proposed 60% on Chinese imports to 20% on the rest of the world, it will trigger higher inflation, thereby slowing the Federal Reserve’s moves to cut interest rates.
So while Mena exports to the US are unlikely to suffer direct fallout from planned tariffs – according to consultancy Capital Economics, the share of Mena goods exports going to the US stood at just 3.5% this decade – it is the secondary effects that could knock regional economies off their stride.
“If we do get the tariffs, and that leads to higher inflation in the US, that also means there will be tighter monetary policy in the Gulf countries with dollar pegs than would otherwise be the case,” says James Swanston, Mena economist at Capital Economics.
The possibility of a stronger dollar in 2025 means that for those economies with dollar pegs, their domestic industries could become less competitive. This jars with the thinking behind regional economic diversification schemes such as Saudi Arabia’s Vision 2030, which are predicated on developing manufacturing sectors that are mainly export-oriented.
 Regional fortitude
The largest Gulf economies should at least be well positioned to withstand such headwinds, even if a trade war hits the global economy. According to the World Bank, a lower interest rate environment, together with further investment and structural reform initiatives, will yield non-oil growth of more than 4% in the region’s two largest economies, Saudi Arabia and the UAE. This – plus higher oil production – should be enough to offset any loss of momentum from lower oil prices and weaker fiscal balances.
Saudi Arabia is expected to show steady growth in 2025, with its Q3 2024 average GDP growth of 2.8% underscoring the kingdom’s stronger performance. However, the robust spending of past years is giving way to a more conservative fiscal approach, and that will inevitably impact project activity.
Riyadh’s 2025 pre-budget statement revealed a tougher fiscal stance for 2025, with anticipation of a deficit of 2.9%. With revenues expected to be 3.5% weaker in year-on year terms in 2025, this will mean reduced spending – around 3% lower than that outlined in the 2024 budget.
“Saudi Arabia is being a bit more prudent about how they spend their money,” says Swanston.
While there will be continued support for current spending, and for the official gigaprojects, capital expenditure will shoulder the burden of cuts. This will likely feed through to weaker non-oil GDP growth.
The UAE should see comparatively stronger growth momentum in 2025, driven by a combination of healthier dynamics in its touchstone real estate and tourism sectors, and the impact of infrastructure investment programmes.
NBK Economic Research sees the UAE non-oil economy enjoying another year of 4%-plus growth in 2025, possibly as high as 5.1%. However, the bank’s economists offer a note of caution, as this is still below the 7.2% annual average growth rate the government requires to achieve the Vision 2031 target of a doubling in GDP by 2031.
On the fiscal front, the UAE is looking at a better situation in 2025. “The UAE has diversified its revenues to the point where non-oil revenues are larger than oil revenues. So, even if oil prices turn negative, they still wouldn’t run a deficit,” says Swanston.
Qatar is maintaining a tight fiscal policy, but from late 2025 it will begin to feel the effects of a significant predicted revenue boost when the first phase of its liquefied natural gas (LNG) expansion comes on stream. This will eventually add 40% to the country’s existing LNG export capacity of 77 million tonnes a year.
Kuwait, meanwhile, is set to run continued budget deficits, although the country’s non-oil economy has emerged from two years of negative growth and is forecast by NBK Research to expand by 2.6% in 2025. But Kuwait faces structural challenges, including a low investment rate and the need for fiscal consolidation, which will absorb policymakers in 2025.
Oman, in contrast, looks to be in a better position than in previous years. According to an Article IV assessment released by the Washington-headquartered IMF in November, reform implementation under Oman Vision 2040 is proceeding decisively, along with initiatives to improve the business environment, attract large-scale investments and empower small and medium-sized enterprises.
The sultanate’s economy continues to expand. Growth, says the IMF, is set to rebound starting in 2025, supported by higher hydrocarbons production and the continued acceleration of non-hydrocarbons growth.
Bahrain faces a challenge when it comes to containing the country’s rising debt-to-GDP ratio, which grew from 100% in 2020 to just under 130% in 2024. The country needs to press ahead with fiscal consolidation moves if it is to improve the debt position.

Wider region
Outside the GCC, the picture will vary in 2025. Egypt has realistic expectations of a better year ahead, with falls in inflation and interest rates providing relief after a tough 2024. But foreign investors may feel a note of alarm at recent indications from President Abdul Fattah El-Sisi that the challenges associated with the country’s reform programme – a hint at the tough impact of reform on Egyptian consumers – might lead it to review its existing IMF deal.
Tunisia presents a similar challenge. President Kais Saied’s proposed bill stripping the central bank of its ability to set interest rates and influence exchange rate policy without government consent is unlikely to encourage investors.
In Egypt at least, there are silver linings that should assure investor confidence, even if the government’s commitment to reform wavers. “When it comes to the debt issue, everything’s in a pretty good place in Egypt,” says Swanston.
“Yes, interest service payments on the debt have risen over the past 12 months, and the feed-through means that they will still be paying quite high debt servicing costs over the next six months. But yields are coming down in terms of its dollar-denominated debt. Worries about default are not as strong as before.”
President El-Sisi may also find support from other sources. Given his previous close ties with the Trump administration in 2016-20, there may be a greater willingness in Washington to disburse funds to such an integral partner of US foreign policy, particularly when it has been buffeted by the Gaza conflict and the impact of Houthi attacks in the Red Sea.
Iraq’s economic fortunes remain bound up with the price of oil, which accounts for 90% of state revenues. The IMF has forecast a 4.1% GDP growth rate for Iraq in 2025, reflecting in part its surprising resilience to regional conflicts. However, lower oil prices may yet erode the country’s economic momentum.
Progress on major projects such as the Development Road would at least suggest prime minister Mohammed Shia Al-Sudani’s government is focused on long-term delivery and tackling Iraq’s overreliance on hydrocarbons exports.
Meanwhile, Iraq’s larger neighbour Iran, which saw GDP growth increase to 5% in the 2023-24 Iranian year, faces still bigger challenges linked to Trump’s return. It can expect to face a much tighter sanctions regime on its oil sector in 2025, with efforts to curb its ability to sell its crude oil on international markets expected to gain traction. The effects of these moves are still in the balance.
The positive news for Tehran is that several of its crude buyers appear to be undaunted by a reimposition of deeper curbs on exports. For example, Chinese refiners have been importing Iranian oil to the tune of 1.5 million barrels a day. The country’s seeming imperviousness to international financial pressures could undercut the impact of a beefed-up US sanctions regime, although few would relish being in the shoes of Iranian economic policymakers right now.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
-
 Syntys breaks ground on 20MW Qatar data centre
13 November 2026
-
 Jereh wins $392m Bu Hasa oil field facilities project
13 November 2026
-
 PDO awards contract for Al-Ghubar oil field project
12 November 2026
-
 Laing O’Rourke joins the international exit list
12 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif
-
Syntys breaks ground on 20MW Qatar data centre
13 November 2026
Register for MEED’s 14-day trial access
Qatari data centre developer Syntys has broken ground on a 20MW facility to support hyperscale, cloud, artificial intelligence (AI) and advanced computing deployments.
The groundbreaking ceremony took place on 12 November. It was attended by Qatar’s Communications & Information Technology Minister, Mohammed bin Ali bin Mohammed Al-Mannai, along with representatives from Ooredoo Group, Microsoft, Google, Kahramaa, the National Cyber Security Agency, Qatar Free Zones Authority and local banks.
Syntys said the facility is being developed on an existing company campus, where power, fibre connectivity and an operational team are already in place. The company has yet to disclose the project value or planned completion date.
The facility is designed to meet Tier 3 requirements and accommodate a range of rack densities, including higher-density configurations for graphics processing unit (GPU)-based AI and high-performance computing workloads.
It will operate as a carrier-neutral facility, allowing customers to select connectivity providers and establish network resilience in line with their own technical and operational requirements.
The project forms part of Syntys’ strategy to expand its Qatar platform through acquisitions and new development. Earlier this year, the company acquired QData QFZ, adding two operational, Tier 3-compliant, carrier-neutral facilities to its portfolio.
Syntys now owns and operates four campuses in Qatar, allowing customers to establish primary and disaster-recovery environments at separate in-country locations.
The company also designs and operates the facilities supporting Ooredoo’s sovereign AI cloud, which uses Nvidia Hopper GPUs.
The development comes as Qatar implements its Digital Agenda 2030, which identifies digital infrastructure as one of six strategic pillars and targets about QR40bn ($11bn) in economic impact by 2030.
The data centre is expected to support the growth of in-country digital services and enable sensitive workloads to remain within Qatar’s national borders.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21378257/main1028.png -
Jereh wins $392m Bu Hasa oil field facilities project
13 November 2026
Register for MEED’s 14-day trial access
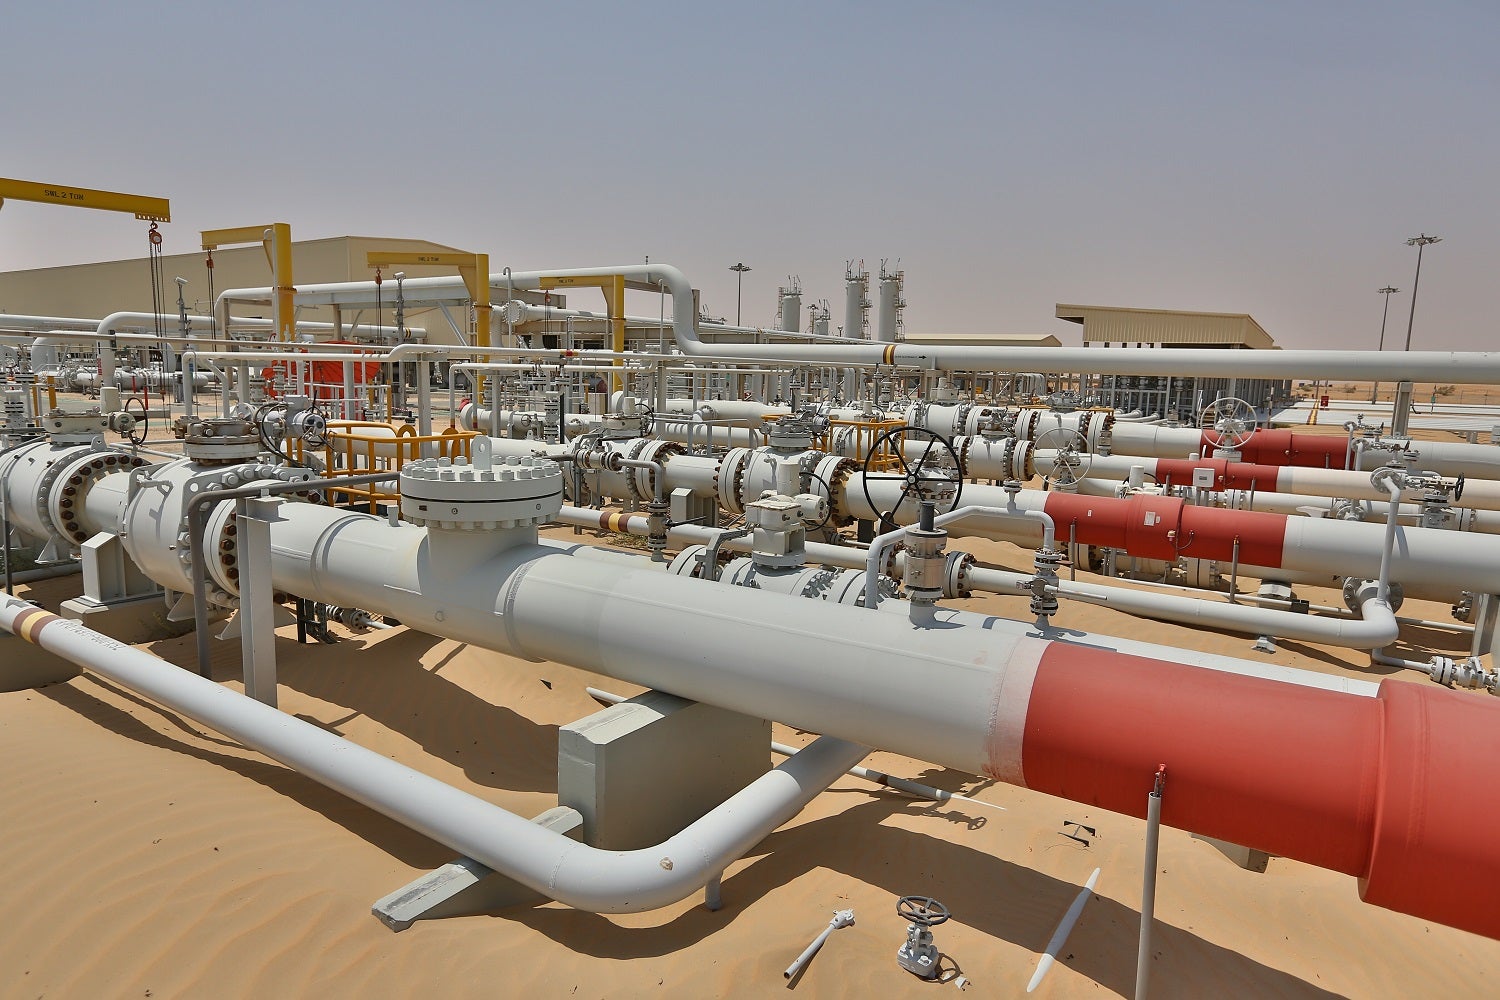
The onshore oil and gas business of Abu Dhabi National Oil Company (Adnoc Onshore) has awarded China’s Jereh Group a contract valued at AED1.44bn ($392.1m) for the engineering, procurement and construction (EPC) of wellhead surface facilities and flowlines at the Bu Hasa cluster of oil fields in Abu Dhabi.
The cluster includes the Bu Hasa, Bida Al-Qemzan and Huwaila fields. The objective of the project is to build wellhead surface facilities and lay gathering flowlines that will connect new wells to the existing production network.
The scope of work on the project also covers the design, fabrication and installation of:
- production well module skids
- gas lift skids, which inject gas into wells to help lift the oil
- skid-mounted wellhead control panels
- solar power units
The framework agreement awarded by Adnoc Onshore on a call-off basis has a duration of 36 months, with an extendable option of 24 months, Jereh said in a filing with China’s Shenzhen Stock Exchange, where it is listed.
Adnoc Onshore is Adnoc Group’s largest production subsidiary, accounting for about 2 million barrels a day (b/d) of crude and about 7 billion cubic feet a day of associated gas from four primary onshore asset clusters: Bab, Bu Hasa, North East Bab and South East.
Maintaining and enhancing oil output levels at the Bu Hasa asset is critical to Adnoc Onshore’s contribution to parent company Adnoc Group’s target of expanding crude oil production capacity to 5 million b/d by 2027, an initiative known as Accelerated Integrated Programme 5. The state energy company’s total production capacity currently stands at approximately 4.85 million b/d.
Prior to this contract, Adnoc Onshore selected Jereh Oil & Gas Engineering Company in 2024 for a project to digitally connect 2,443 wells at the Bab, Bu Hasa and South East cluster of onshore oil fields in Abu Dhabi for remote operations. The contract, formally awarded in 2025, was valued at $920m.
Abu Dhabi contracts
The contract for the Bu Hasa wellhead facilities and flowlines is among a trio of projects totalling approximately $2.7bn that has been awarded by Adnoc Group in recent weeks, Jereh announced in its stock market filing.
The largest of the three contracts, valued at $1.7bn, is for the Ruwais Diyab unconventional gas development in Abu Dhabi. Awarded to Jereh on a design, build and operate model, the contract has a duration of 29 months for construction works and 60 months of operations, with up to two five-year extensions available.
Adnoc achieved final investment decision on the Ruwais Diyab unconventional gas development project on 2 November, during the Abu Dhabi International Petroleum Exhibition and Conference 2026.
The project will deliver 345 million standard cubic feet a day (scf/d) of raw gas from 2029 over a 25-year period, with the potential to reach up to 1 billion scf/d in the future.
The scope of work on the Ruwais Diyab project covers:
- wellsite facilities
- a central processing facility
- gas gathering pipelines and product export pipelines
- utilities
The plant will treat the raw gas and recover the liquids produced with it. It will also treat produced water, which is the water that comes up from the wells with the gas, and recover sulphur. Finished products will be delivered to designated receiving facilities.
When the operation period ends, Jereh will either hand the facilities over to Adnoc or decommission them and restore the site, as the contract and the owner require.
The third contract covers Adnoc Onshore’s Bab and North East Bab 1 tie-in project, where the main scope of work involves tying in new oil producer wells and removing and modifying surface facilities at existing producer wells.
The project’s scope also covers supporting works for water supply wells, water injection wells, disposal wells and water-alternating-gas injection wells. Several existing wells will also be upgraded with digital systems.
Jereh said the value of its contract is $599m, with a duration of 60 months. Similar to the Bu Hasa project, this contract also uses a framework model wherein Adnoc Onshore will issue work orders in batches according to its execution plans.
MEED previously reported that Adnoc Onshore had divided the scope of work on the Bab and North East Bab 1 tie-in project into 18 EPC packages. Along with Jereh, Adnoc Onshore has picked Abu Dhabi-based Robt Stone Middle East for a portion of work on the project.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21355151/main3320.jpg -
PDO awards contract for Al-Ghubar oil field project
12 November 2026
Register for MEED’s 14-day trial access
Petroleum Development Oman (PDO) has awarded the main contract for a project to build a facility to handle additional oil production from the Al-Ghubar field in the sultanate.
The Al-Ghubar field is located in the Ghaba Salt Basin at Qarn Alam, within majority state-owned PDO’s Block 6 concession area.
The Al-Ghubar gas-oil gravity drainage (GOGD) facility will be designed as a sour (hydrogen sulphide) facility and is expected to handle a maximum oil production rate of 1,800 standard cubic metres a day (cm/d), a total water flow rate of up to 10,421 standard cm/d and gas lift of up to 256,934 standard cm/d. Production from the planned Al-Ghubar GOGD facility will be exported to PDO’s main oil line.
China-based Jereh Group has won the contract for the Al-Ghubar GOGD facility project, sources told MEED.
A project kick-off meeting between PDO and Jereh has also recently taken place, the sources said.
MEED previously reported that Jereh had emerged as the lowest bidder for the project.
The following contractors, among others, are understood to have been bidding for the Al-Ghubar GOGD facility project:
- Engineering for the Petroleum & Process Industries (Egypt) / Petrojet (Egypt)
- GS Engineering & Construction (South Korea)
- Jereh (China)
- Larsen & Toubro Energy Hydrocarbon (India)
PDO floated the tender for the Al-Ghubar GOGD facility project in March, setting an initial bid submission deadline of 4 May, MEED previously reported.
PDO later extended the deadlines for the submission of technical and commercial bids to 26 July and 7 August, respectively. Contractors submitted technical proposals by the revised deadline, according to sources.
After receiving the technical bids for the project in July, PDO granted contractors until 16 August to submit commercial bids. It eventually extended the deadline to 1 September, with contractors submitting commercial proposals by that date, as MEED reported.
The scope of work on the Al-Ghubar GOGD project covers the engineering, procurement and construction (EPC) of the following:
- On-plot scope, consisting of:
- Production separator
- Test separator
- Concentric wash tank
- Wet oil pump
- Water bath heater
- Surge tank
- Gas injection/gas lift compressor (centrifugal)
- Utilities (instrument air compressors, chemical injection skids, drain system, vent system)
- Suction scrubber
- Air coolers
- Discharge scrubbers
- Condensate flash drum
- Atmospheric pressure knock-out drum
- Flare system
- Gas heater
- Water disposal pump
- Oil shipping pump
- 132kV substation and plant substation (housing 6.6kV and 415-Volt switchboard)
- Control room
- Off-plot scope consisting of:
- Off-plot pipeline network (bulk header, test header, gathering infrastructure/ gathering line header, instrument air header, water disposal header)
- Two remote manifold stations
- Tie-in connection to main oil line
- Tie-in to gas network pipeline
PDO previously intended to tender the Al-Ghubar GOGD project under its framework structure with selected EPC contractors, but ultimately tendered it separately.
PDO is the operator of Oman’s Block 6 hydrocarbons concession, the sultanate’s largest and most prolific concession. Situated onshore and covering an area of 75,119 square kilometres, Block 6 contains 202 oil fields and 43 gas fields. PDO produces approximately 680,000 barrels a day of oil and condensates from the fields.
The Omani government holds a 60% stake in PDO through Energy Development Oman. The other shareholders are UK-based Shell (34%), France’s TotalEnergies (4%) and Thailand’s state-owned PTTEP (2%).
https://image.digitalinsightresearch.in/uploads/NewsArticle/21345337/main2647.jpg -
Laing O’Rourke joins the international exit list
12 November 2026
Commentary
Colin Foreman
EditorRegister for MEED’s 14-day trial access
Laing O’Rourke’s decision to seek a buyer for its Middle East business marks the end of an era for UAE construction.
In the early 2000s, the contractor was among the leading names in the market. Its work at Dubai International airport, the Atlantis hotel on the Palm Jumeirah and the ski slope at Mall of the Emirates made it arguably the UAE’s most prominent contractor during the pre-global financial crisis construction boom.
Its activities were not limited to Dubai. A partnering agreement with Aldar for Al-Raha Beach then made it the most active contractor in Abu Dhabi almost overnight.
The global financial crisis changed its fortunes. The Aldar Laing O’Rourke joint venture ended. Unsettled by payment problems and wider stress in the industry, the company took a more cautious approach to clients and projects in the region. One executive at the time told MEED: “You might see lots of tower cranes, but none of them are doing work that we would want to do.”
The contractor’s appetite partially returned in the late 2010s, when it won Al-Wasl Plaza at the Expo 2020 site in Dubai. It also became a leading player in the growing data centre market, delivering facilities for repeat clients, including Khazna and Equinix.
Data centres have since been its focus. These are significant projects, but they lack the public profile of the airport, Atlantis and Al-Wasl Plaza. As its profile faded, the company sold its UAE joinery arm to Dubai-based Arco Turnkey Solutions in 2025.
Laing O’Rourke now looks set to follow other international contractors that have, for various reasons, left the region, including Murray & Roberts, Balfour Beatty, Multiplex, Carillion and Bam. With a record £17.2bn order book anchored by UK and Australian infrastructure, the group’s priorities clearly lie elsewhere.
Whoever buys the business will inherit strong data centre credentials. For much of the market, however, Laing O’Rourke will be remembered for the landmark projects that defined the UAE’s boom years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21344577/main.jpg