Trump 2.0 targets technology
30 January 2025

As Donald Trump settles into his second term, dubbed ‘Trump 2.0’, the administration is set to bring about a seismic shift in global technology, artificial intelligence (AI) regulation, data sovereignty, cryptocurrency and the ever-escalating US-China tech war.
The central role that technology is expected to play was demonstrated at Trump’s inauguration on 20 January, where Tesla and SpaceX CEO Elon Musk, Meta CEO Mark Zuckerberg, Alphabet Inc CEO Sundar Pichai and Amazon founder Jeff Bezos had prime seats.
With Trump championing policies prioritising domestic interests and reshaping international dynamics, Middle Eastern investors and companies will play a key role in shaping this new era of tech-infused geopolitics.
The wheels are already turning. On 22 January, just two days after Trump’s inauguration, he announced that Abu Dhabi- based AI-focused fund MGX has teamed up with US-based tech firms Oracle and ChatGPT creator OpenAI, and Japan’s Softbank, to form the Stargate project, which aims to invest $500bn to build AI infrastructure in the US.
When announcing the project, Trump described it as “the largest AI infrastructure project by far in history”.
 America first
Two weeks earlier, on 7 January, Hussain Sajwani, founder and chairman of UAE-based Damac Properties and Damac Group, made headlines by pledging $20bn to develop data centres in the US.
Sajwani’s $20bn commitment to US data centres is not just a business transaction – it demonstrates the UAE’s strategic pivot to align with Trump’s America First policy. Unlike the real estate deals offered by Sajwani that Trump publicly declined in 2017, the latest investment offer places resources directly into the US, promising jobs, innovation and a fortified tech infrastructure in states including Texas, Ohio and Michigan.
For MGX, Sajwani and other Gulf investors, the deal offers not only financial returns but also political capital in an administration that values loyalty and mutual economic benefit.
The timing is also strategic: as Trump prepares to loosen regulatory constraints on AI and data, Gulf nations have the opportunity to tap into US expertise while positioning themselves as indispensable partners in the rapidly shifting tech landscape.
Tech wars
Geographically and politically, the Middle East – particularly the GCC states – sits in the middle of the simmering tech war between China and the US, which may boil over during the Trump presidency.
The decoupling of the two economies is expected to continue, with Trump reinforcing policies that discourage US companies from engaging with Chinese firms.
Policies could involve stricter foreign investment vetting and expanded technology transfer restrictions to China. The Trump administration has also threatened to impose high tariffs on Chinese goods, which could disrupt the established ties between US and Chinese tech industries.
The ongoing tensions could lead to a bifurcation of global supply chains, with significant implications for companies operating in both markets.
For Middle Eastern countries, this decoupling offers a rare window of opportunity. As the US and China distance from one another, GCC players can position themselves as neutral ground for technology partnerships. The region could bridge the two worlds by attracting global firms to invest in regional tech hubs that offer a haven for talent and innovation.
Trump’s America First policies are also expected to accelerate the development of the US semiconductor sector, a critical component of the tech war. While this could disrupt global supply chains, it may also create demand for GCC investments in US tech manufacturing and research facilities, further deepening economic ties.
Another transformative area of Trump’s second term will be his approach to AI.
On 13 January, just days before Trump took office, the White House issued a brief of a regulation by the Department of Commerce imposing controls on the exports of advanced computing integrated circuits that support AI.
The regulation’s final draft divides countries into three tiers. Chip exports to the top-tier countries, comprising 18 of the closest US allies, are “without limit”, while the third tier is reported to comprise countries of concern, including Macau (China) and Russia.
All other nations and states, including those in the GCC, are presumed to be mid-tier countries, where a cap of approximately 50,000 graphics processing units between 2025 and 2027, will apply.
Individual companies from these countries will be able to achieve higher computing capability if they comply with US regulations and obtain validated end-user status.
The White House brief is no longer available online, but a copy of the regulation can still be found in the Federal Register, the US government’s daily journal.
Middle Eastern investors and companies will [help shape] this new era of tech-infused geopolitics
Deregulation likely
The regulation-heavy approach of former president Joe Biden’s administration will likely give way to a deregulatory environment, emphasising commercial innovation over antitrust crackdowns.
For GCC countries such as Saudi Arabia and the UAE, this presents a double-edged sword. Both nations have ambitious AI investment plans – Abu Dhabi’s MGX partnership with BlackRock and Microsoft aims to mobilise $100bn for AI infrastructure, while Riyadh’s Project Transcendence seeks to redefine the region’s technological footprint. Trump’s deregulatory policies could catalyse innovation and partnerships with US firms, offering access to cutting-edge AI solutions.
The emphasis on deregulation may also create challenges. Without robust ethical and safety guidelines, the global AI ecosystem could face reputational risks, making cross-border collaborations more complex. For the GCC, balancing the benefits of US technological advancements with the need for ethical AI development will be a delicate dance.
As geopolitical tensions rise, the effects of Trump’s focus on data sovereignty will reach far beyond US borders. Nations increasingly prioritise data protection, creating stricter regulations to control where and how data is stored, and the GCC, with its ambitious AI and data centre projects, must adapt swiftly to these changes.
The outlook for developing energy-hungry data centres in the US could be further bolstered by plans to deregulate the energy industry.
“If energy deregulation is unleashed, the biggest beneficiaries of Trump’s energy policies could be in data centre buildout, with implications for US leadership in AI, both in next-generation technologies and economic dominance over the coming generation,” according to a report by GlobalData’s TS Lombard.
For Middle Eastern businesses, Trump’s policies could mean stricter requirements when working with US tech firms. Data from US companies and citizens may need to be stored domestically, complicating cross-border operations.
However, this also presents an opportunity for the GCC states to bolster their data sovereignty frameworks, attracting investments from companies seeking alternatives to US or Chinese infrastructure.
The unexpected should be expected, and the future belongs to those who adapt the fastest
Backing Bitcoin
Cryptocurrency is another major opportunity for the GCC.
Trump’s surprising endorsement of Bitcoin – the price of which recently surged past $75,000 – signals a potential shift in US crypto policy. A more favourable regulatory environment under Trump could drive mainstream adoption of cryptocurrencies, attracting investors and innovators alike.
As regional players such as the UAE have been pioneers in blockchain technology, this could catalyse further growth.
Dubai’s Blockchain Strategy 2025, aimed at positioning the emirate as a global blockchain hub, aligns well with Trump’s pro-Bitcoin stance. By collaborating with US firms and leveraging blockchain’s potential for financial and governmental applications, the GCC could cement its position as a leader in the cryptocurrency space.
As his backing of Bitcoin demonstrates, Trump’s position on tech issues is hard to predict. This was reinforced when he issued an executive order allowing social media application TikTok to resume services to its 170 million users in the US.
On 18 January, the Chinese-owned app stopped working in the US after a law banning it on national security grounds came into effect. Trump had previously supported plans to ban the app.
For business and government alike, the message is clear: the unexpected should be expected, and the future belongs to those who adapt the fastest.
As Trump reshapes the global tech landscape, GCC investors like Sajwani are well positioned to capitalise on the changes. The US-China decoupling, AI deregulation and a focus on data sovereignty create openings for Middle Eastern nations to assert themselves as key players in the global tech economy.
Challenges remain. Trump’s America First policies could lead to tighter restrictions on foreign investments, requiring Gulf investors to navigate a more complex regulatory environment. Additionally, the potential talent drain to the US, driven by Trump’s prioritisation of domestic commercial interests, could slow the region’s AI ambitions.
To stay competitive, GCC nations will need to double down on their investments in education, infrastructure and innovation. By fostering homegrown talent and creating favourable conditions for international partnerships, the region can mitigate the risks of Trump’s policies while reaping the rewards.
 READ MEED’s YEARBOOK 2025
MEED’s 16th highly prized flagship Yearbook publication is available to read, offering subscribers analysis on the outlook for the Mena region’s major markets.
Published on 31 December 2024 and distributed to senior decision-makers in the region and around the world, the MEED Yearbook 2025 includes:
|
> PROJECTS: Another bumper year for Mena projects
> GIGAPROJECTS INDEX: Gigaproject spending finds a level
> INFRASTRUCTURE: Dubai focuses on infrastructure
> US POLITICS: Donald Trump’s win presages shake-up of global politics
> REGIONAL ALLIANCES: Middle East’s evolving alliances continue to shift
> DOWNSTREAM: Regional downstream sector prepares for consolidation
> CONSTRUCTION: Bigger is better for construction
> TRANSPORT: Transport projects driven by key trends
> PROJECTS: Gulf projects index continues ascension
> CONTRACTS: Mena projects market set to break records in 2024
|

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 State-backed spending cushions UAE construction slowdown
13 October 2026
-
 Consortium signs EPC contract for Rabigh 2 IPP expansion
13 October 2026
-
 Contractors submit Riyadh road scheme bids
13 October 2026
-
 Contractor groups prequalify for Dubai Metro Gold Line
13 October 2026
-
 Egypt discusses technology cooperation with SLB
13 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
State-backed spending cushions UAE construction slowdown
13 October 2026
The UAE projects market is undergoing a structural realignment. Following a surge in private real estate investment after the Covid-19 pandemic, activity in the commercial and residential segments has softened amid regional geopolitical uncertainty.
Rather than allowing the market to contract, state and government-related entities (GREs) – particularly in Dubai – have stepped in to offset the shortfall, deploying balance-sheet capital countercyclically into strategic infrastructure, cultural and tourism projects.
Dubai recalibrates
Dubai’s construction sector has remained resilient at a headline level. On-site work continues, and major international contractors are securing new work.
A clear indicator of this stability came in September, when China State Construction Engineering Corporation secured an AED5bn ($1.3bn) contract from Dubai Holding for the developer’s new headquarters and the Jumeirah Residences Emirates Towers scheme.
Beneath this headline stability, however, procurement drivers have shifted dramatically. Private real estate activity, which supported the market’s post-pandemic resurgence, cooled following the onset of regional conflict at the end of February. Off-plan residential sales declined from a monthly peak of $9bn in February to $4bn in August.
Monthly contract awards for residential projects mirrored this contraction, dropping from $3bn to $306m over the same period as private developers deferred new project launches and conserved capital.
Government and government-related clients have absorbed much of the resulting shortfall. Dubai awarded $52.6bn of contracts in 2025, of which state-backed clients accounted for $26bn, or about 49%.
In 2026 to date, government and GRE procurement has reached $22.4bn of the $34.6bn in contracts awarded, representing almost two-thirds of total market activity.
The shift towards sovereign-backed spending appears intended to support construction activity and limit pressure on the supply chain during a period of private sector retrenchment.
This state intervention is underpinned by an unawarded projects pipeline of $530bn in Dubai, according to MEED Projects data.
The city’s future construction pipeline remains heavily weighted towards housing and integrated urban developments. Unawarded construction projects in the emirate total about $144.5bn, with residential and mixed-use developments accounting for almost 89% of the total value.
Planned residential schemes account for $66.5bn, or 46%, of the pipeline, followed by large-scale mixed-use developments at $62bn, or 42.7%. The remainder comprises hospitality projects ($5bn), commercial offices ($4.8bn), telecommunications ($2bn) and retail ($2bn), alongside smaller allocations for education and civic facilities.
Abu Dhabi accelerates
A similar dynamic is evident in Abu Dhabi, where sovereign-backed entities continue to shape construction procurement. Unlike Dubai, which has historically relied more heavily on private developers, Abu Dhabi’s market is largely led by state-affiliated master developers.
Entities such as Aldar Properties and Modon Holding remain the primary engines of the emirate’s residential and mixed-use pipeline, progressing vast masterplans across Saadiyat Island, Yas Island and Hudayriyat Island.
At the same time, Abu Dhabi is directing public capital expenditure towards entertainment, culture and hospitality as it pursues the objectives of its Tourism Strategy 2030.
Rather than moderating capital deployment amid regional geopolitical strains, state-backed entities are accelerating destination developments designed to expand visitor capacity and build long-term economic resilience.
Leisure developer Miral has already confirmed plans to invest more than AED12bn ($3.2bn) across Yas Island over the next five years. The investment will fund new attractions and expand hotel capacity, separate from the planned Disney development.
Work is already under way on a 63,000-square-metre phase-two expansion of Warner Bros World Yas Island, featuring a Harry Potter-themed zone.
Major civic entertainment venues are also moving to construction. In May, Alec Engineering & Contracting received the letter of award for the $1.7bn Sphere Abu Dhabi project on Yas Island. The venue is being developed by the Department of Culture and Tourism–Abu Dhabi (DCT Abu Dhabi) in partnership with US-based Sphere Entertainment, and is scheduled to be completed in the third quarter of fiscal year 2029.
On neighbouring Saadiyat Island, DCT Abu Dhabi has broken ground on Dar Al-Funoon, a performing arts venue designed by the late Frank Gehry. The project is planned to accommodate more than 6,000 people across a 2,000-seat multipurpose hall, an open-air amphitheatre, a studio theatre and a jazz venue. Main contract bids are currently under evaluation ahead of an imminent award and a 2030 opening.
Abu Dhabi’s unawarded projects pipeline is led by mixed-use and residential developments, which together account for about $51.3bn, or 54% of the roughly $95bn total shown.
Telecommunications and data infrastructure forms the single largest individual segment at $33.4bn (35%). Subsequent phases of the estimated $40bn Stargate project represent the bulk of the emirate’s planned data-centre capacity. The planned artificial intelligence infrastructure initiative is designed to strengthen Abu Dhabi’s position as a regional data and connectivity hub, with construction on phase one already under way.
Hospitality accounts for a further $7.6bn (8%) of the pipeline. The remaining balance of roughly $2.6bn is distributed across retail, culture, leisure, healthcare, public facilities, commercial offices, earthworks and education.
Along with Dubai’s $79.6bn in near-term tenders, the combined $116bn in active procurement confirms that sovereign liquidity will continue to insulate the UAE construction market from broader private sector volatility.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20536766/main.gif -
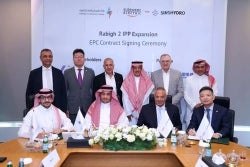
Consortium signs EPC contract for Rabigh 2 IPP expansion
13 October 2026
A consortium comprising PowerChina, Egypt’s Elsewedy Electric and Beijing-headquartered Sinohydro has signed an engineering, procurement and construction (EPC) contract for Saudi Arabia’s Rabigh 2 combined-cycle gas-turbine (CCGT) independent power project (IPP) expansion.
The signing ceremony took place in Riyadh on 12 October and the contract involves the plant’s design, procurement, installation, construction, commissioning, grid connection and performance testing.
MEED previously reported that construction works had commenced, with Elsewedy Electric and Sinohydro carrying out works on the project.
The signing follows the project’s financial close earlier this month, after it secured SR9.69bn ($2.58bn) in long-term financing.
The financing has a tenor of approximately 34 years and was provided by a consortium of local, regional and international lenders.
The project is being developed by Al-Morjan Two Electricity Company, in which Acwa and Saudi Energy, formerly Saudi Electricity Company, each hold a 40% stake.
In April, MEED reported that Acwa and Saudi Energy had signed a 31-year power purchase agreement (PPA) with Saudi Power Procurement Company (SPPC) for the project.
The agreement is valued at SR11.5bn ($3.07bn) and covers the development of a CCGT plant in the Mecca region under a build, own and operate arrangement. The project also includes the development and expansion of a 380kV electrical substation. The plant is designed to be ready for the future installation of carbon-capture technology.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20535598/main3026.jpg -
Contractors submit Riyadh road scheme bids
13 October 2026
Register for MEED’s 14-day trial access
Contractors submitted bids in the first week of October to upgrade a section of the Al-Urubah Road axis leading to Prince Bandar Bin Abdulaziz Road in Riyadh.
The project scope involves upgrading about 15.5 kilometres of the road to increase capacity to about 200,000 vehicles a day.
MEED understands that the bidders include:
- Al-Ayuni Investment & Contracting
- Al-Rashid Trading & Contracting
- China Civil Engineering Construction Corporation / Al-Omaeir Trading & Contracting
- Mofarreh Alharbi & Partners
- Nesma & Partners
The project aims to increase traffic capacity, streamline vehicular movements and eliminate conflict points along the corridor.
The US-based engineering firm Parsons is overseeing the project’s implementation after winning a $53m contract from the Royal Commission for Riyadh City (RCRC) in 2024.
The contract includes project management services for RCRC’s main and ring roads programme.
The programme includes 500km of new roads and upgrade works in and around Riyadh.
In 2021, Saudi Arabia’s Crown Prince Mohammed Bin Salman Bin Abdulaziz Al-Saud said Riyadh’s population would double to 15-20 million people by 2030.
He directed government entities to work closely with the RCRC to prepare the city’s development strategy.
The RCRC’s major projects include Riyadh Metro, Riyadh Art, Sports Boulevard, King Salman International Park, Green Riyadh and several road development projects in the capital.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20533695/main.jpg -
Contractor groups prequalify for Dubai Metro Gold Line
13 October 2026
Six contracting groups submitted prequalification statements on 9 October for the contract to build Dubai Metro’s new Gold Line.
The Roads & Transport Authority (RTA) issued the request for qualification notice for the project in June, as MEED exclusively reported.
The consortiums formed to bid for the main contract are:
- Alstom / China Railway Engineering Corporation / National Projects Construction / Dogus Construction (France/China/local/Turkiye)
- CRRC / Limak / Mapa Group (China/Turkiye/Turkiye)
- Hitachi / China Harbour Engineering Company / China State Construction Engineering Corporation (Japan/China/China)
- Siemens / Petrojet / Concord Engineering & Contracting / Rowad Modern Engineering (Germany/Egypt/Egypt/Egypt)
- Hassan Allam / IC Ictas / Siemens (Egypt/Turkiye/Germany)
- Larsen & Toubro / Powerchina / Wade Adams (India/China/local)
Dubai officially announced the Gold Line in April.
In a post on social media site X, Sheikh Mohammed Bin Rashid Al-Maktoum, UAE Vice President and Prime Minister and Ruler of Dubai, said the project would cost about AED34bn ($9.2bn).
The Gold Line will increase the Dubai Metro network’s total length by 35%. The project is scheduled to be completed in September 2032.
The fully underground line will extend for more than 42 kilometres and include 18 stations. It will pass through 15 areas of Dubai and serve 1.5 million residents.
The project is expected to connect more than 55 under-construction real estate developments.
The Gold Line will begin at Al-Ghubaiba in Bur Dubai and terminate at Jumeirah Golf Estates. It will connect with the existing Red and Green lines and integrate with the Etihad Rail passenger network.
The contractor will be responsible for the design and construction of all civil works, electromechanical equipment, rolling stock and rail systems. The selected contractor will also be required to support systems maintenance and operations during an initial three-year period.
In October last year, MEED exclusively reported that the RTA had selected US-based engineering firm Aecom to provide consultancy services for the Dubai Metro Gold Line project.
Stage one covers concept design; stage two, preliminary design; stage three, tender-document preparation; stage four, construction supervision; and stage five, the defects-liability period.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20531469/main.png -
Egypt discusses technology cooperation with SLB
13 October 2026
Egypt is in talks with US-based oilfield services company SLB to expand technical cooperation in the country’s oil and gas sector, according to a statement from the Ministry of Petroleum & Mineral Resources.
Egyptian Minister of Petroleum and Mineral Resources Karim Badawi met SLB chief executive Olivier Le Peuch in Riyadh, the ministry said.
During the meeting, they discussed ways to strengthen their strategic partnership and expand cooperation in technology and digital transformation.
They also discussed how SLB could support exploration and production activities, with the aim of increasing output and attracting further investment in Egypt’s oil and gas sector.
Badawi emphasised the importance of extending the existing partnership with SLB, including its role in technology transfer and the development of technical capabilities in Egypt’s oil sector, according to the statement.
He said Egypt should build on existing areas of cooperation and deploy advanced technological solutions to reduce exploration risk, increase recovery and production rates from existing fields, and improve operational efficiency.
Badawi and Le Peuch also discussed progress on a seismic survey project being undertaken by SLB in partnership with France-based Viridien.
The project includes an ocean-bottom node seismic survey covering about 95,000 square kilometres of Egypt’s eastern Mediterranean waters.
The discussion focused on the data processing and analysis schedule, the steps required to prepare and release preliminary results, and the drilling schedule.
Badawi and Le Peuch also discussed expanding the use of horizontal drilling technologies in Egypt. This would involve identifying suitable locations and developing a commercial and contractual model for their deployment.
The Ministry of Petroleum & Mineral Resources and SLB are also exploring opportunities to expand the use of artificial intelligence in reservoir management and production optimisation.
This work is being explored in partnership with the Egyptian General Petroleum Corporation and Egyptian Natural Gas Holding Company.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20517735/main.jpg