Transport links stitch GCC together
25 November 2024
This package also includes: Cooperation strengthens Gulf markets
 Analysis
Colin Foreman
Editor
Transport projects connecting the GCC have made stuttering progress over the years, with brief periods of intense project positioning typically followed by years of little progress.
These projects are crucial for intra-GCC trade, and, once built, should provide a catalyst for further economic activity.
Since the Al-Ula Accords were signed in January 2021, projects have started to move forwards again, with schemes including the GCC railway network, the GCC grid, and several other road and causeway links at various stages of planning and construction.
 GCC rail
For the GCC railway network, GCC leaders approved the establishment of the GCC Rail Authority in January 2022. The entity is entrusted with overall policymaking and coordination among member states to ensure the smooth delivery and operation of the scheme.
The railway will stretch over 2,177 kilometres (km), from Kuwait, through Dammam in Saudi Arabia, to Bahrain, with a causeway to be constructed between the two countries, and from Dammam to Qatar, Saudi Arabia, the UAE and finally to Muscat via Sohar in Oman.
There will be 684km of track in the UAE, 663km in Saudi Arabia, 306km in Oman, 283km in Qatar, 145km in Kuwait and 36km in Bahrain.
Passenger trains will run at 220 kilometres an hour (km/h), while freight trains will travel at 80-120km/h.
The project is expected to take a significant step forward this year with the award of the contract to prepare the operational plan study for the scheme. Speaking at the Global Rail event in Abu Dhabi on 8 October, sources told MEED that “the evaluation is in the final stages and the contract award is imminent”.
A source added that the General Secretariat of the Cooperation Council has set a deadline of 2030 for the project to be operational.
Several causeways are planned that will provide transport links between countries in the GCC. After stalling after 2010, Qatar and Bahrain have agreed to restart plans to develop the $4bn Qatar-Bahrain Causeway project. The two countries have also instructed the respective authorities to finalise plans for initiating the implementation of the project. The next step will be establishing a technical committee and appointing a consultancy to work on the designs.
The 40km-long causeway will connect the eastern coast of Bahrain to the northern region of Qatar. It will feature a dual two-lane highway and a rail link for the GCC rail network.
Once built, these transport projects should provide a catalyst for further economic activity
Construction on the project was originally scheduled to start in early 2009 after a consortium led by Vinci Construction Grands Projets signed a $3bn design-and-build contract in May 2008.
The consortium also included Qatari Diar Real Estate Investment Company, Germany’s Hochtief, Greece’s Consolidated Contractors Company and Belgium’s Deme Group.
The project was initially designed by France’s Lavigne & Cheron Architects. US-based consultant KBR was appointed as the project management consultant with support from Halcrow, which is now part of US-based Jacobs.
Further crossings
Another planned international crossing is the second causeway between Saudi Arabia and Bahrain. The $3.5bn project, which has been called the King Hamad Causeway project, was moving towards construction in 2021 when it was included in Bahrain’s $30bn Strategic Projects Plan. Since then progress has been slow, and it is understood that the authorities are re-evaluating how the project should move ahead.
The project involves building a 25km road and rail crossing linking Saudi Arabia and Bahrain. It will follow the same alignment as the existing King Fahd Causeway. It has been earmarked for delivery on a public-private partnership basis. The King Fahd Causeway Authority appointed a consortium to provide transaction advisory services in late 2019.
The $8.9m consultancy agreement was signed with a consortium of Netherlands-headquartered KPMG, US-based Aecom and UK-based CMS. The team was tasked with working on developing the financing model, the required engineering specifications and design, as well as helping with the assessment and selection of the developers.
Canada-based SNC Lavalin and UK-based consultancy firm PwC conducted the project due diligence study in 2017.
The existing King Fahd Causeway is operating at capacity. About 11.5 million cars cross the causeway every year, and the growth has been 6% per annum over the past 10 years.
Another causeway being considered is a link connecting Abu Dhabi and Qatar. The proposed link could provide road and rail access between Qatar and the UAE, bypassing Saudi Arabia, located between the countries.
The concept has been considered before. There were plans in 2005 that involved building a 40km causeway starting near Sila in Abu Dhabi emirate and extending to the south of Doha.
In the past, there have been difficulties with the route because it runs across Saudi Arabian territorial waters.
Road links
Overland road links have also been built. In 2021, a 725km-long road running through the Empty Quarter from Saudi Arabia to Oman opened. The Saudi section of the highway is 564km long, and the Oman section runs for 161km. The highway provides a link between the two countries bypassing the UAE.
When it opened, the authorities added that the road would improve trade between Oman and Saudi Arabia and give Oman access to Saudi Arabia’s Red Sea Ports. Likewise, it gives Saudi Arabia access to Oman’s ports on the Arabian Sea.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 SAR tenders railway track design framework
5 November 2026
-
 Aramco commissions Zuluf field oil increment project
5 November 2026
-
 BP and PetroChina cut budgets for Iraq oil projects
5 November 2026
-
 Read the November 2026 MEED Business Review
4 November 2026
-
 UAE economy shows resilience
4 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
SAR tenders railway track design framework
5 November 2026
Register for MEED’s 14-day trial access
Saudi Arabia Railways (SAR) has invited consultants to bid by 14 December for a framework agreement covering railway track design services.
The state-owned operator is seeking to accelerate the delivery of smaller projects across its network.
SAR has scheduled a pre-tender meeting for 12 November.
Under the framework, SAR will appoint a panel of specialist consultants to carry out design work through work orders or task orders issued as required. This will remove the need for SAR to launch a separate tender for each project.
SAR said a long-term contract with several specialist service providers would benefit all parties, particularly for smaller projects.
SAR will detail the required works and communicate them to the selected consultants through each work order or task order.
The scope covers engineering studies, as well as concept, preliminary and detailed design for railway infrastructure. Services will include surveys, alignment design, geotechnical assessments, cost estimation and construction support.
Consultants will be expected to produce drawings, reports, risk registers, bills of quantities and other design documentation. All deliverables must comply with SAR standards for UIC 60 track systems and associated infrastructure.
SAR said it is seeking partnerships with competent consultants to supply track and track infrastructure design services under the terms of the tender document.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21168500/main.jpg -
Aramco commissions Zuluf field oil increment project
5 November 2026
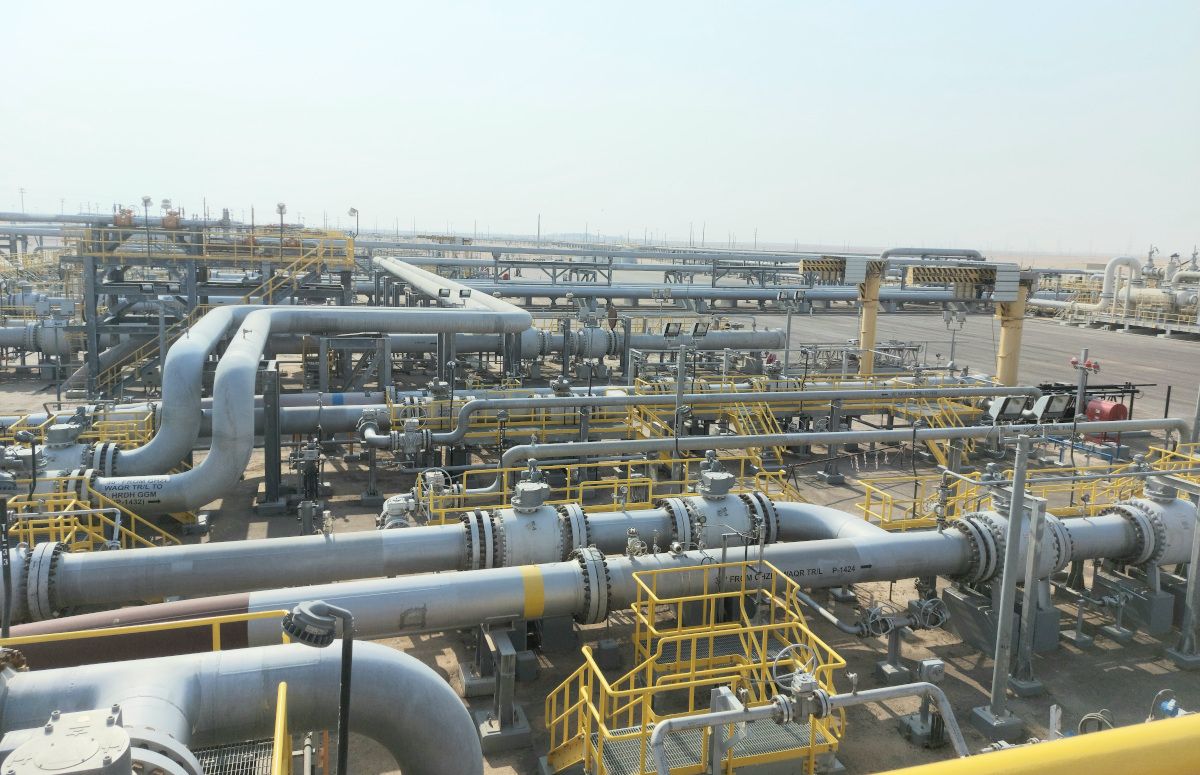
Saudi Aramco has announced the start of oil production at the Zuluf oil increment project in Saudi Arabia, on which it is estimated to have spent about $7bn in 2022.
The Saudi energy company made the announcement as part of its third-quarter 2026 financial results, in which it reported adjusted net income of $31.2bn, up 9% year on year.
The Zuluf oil increment project involved substantial onshore and offshore work at the field, located in the Gulf about 40 kilometres off Saudi Arabia’s northeastern coast.
The engineering, procurement and construction (EPC) scope was divided into two onshore packages and five offshore packages.
Aramco selected Japan’s JGC Holdings Corporation in May 2022 for the two main onshore packages of the Zuluf field development. Together, the packages were estimated to be worth up to $3.5bn.
Package 1 was estimated to be the larger of the two onshore packages, with a contract value of about $2bn-$2.5bn. It covered EPC work to build hydrocarbon-processing facilities for the Zuluf development, principally an onshore gas-oil separation plant.
Package 2 covered utilities and water-injection facilities and was estimated to be worth about $1bn.
Before awarding the onshore contracts, Aramco had awarded more than $4bn of contracts across five main offshore engineering, procurement, construction and installation packages. The awards went to US-headquartered McDermott International; a consortium of India’s Larsen & Toubro Hydrocarbon Engineering and UK-headquartered Subsea7; and Abu Dhabi’s NMDC Energy, then known as National Petroleum Construction Company.
Since the 2022 EPC awards, Aramco has invested further in maintaining and upgrading infrastructure at the Zuluf field. The work supports the company’s objective of maintaining its maximum sustained crude oil production capacity at 12 million barrels a day (b/d).
Other upstream projects
In its Q3 2026 results statement, Aramco also announced EPC progress on other key upstream oil and gas projects, including:
Jafurah phase two – Aramco awarded 16 contracts, worth a combined total of about $12.4bn, on 30 June 2024 for the second expansion phase of the Jafurah unconventional gas development programme in the Eastern Province.
The second phase aims to raise the field’s processing potential to up to 2 billion cubic feet a day (cf/d) of raw gas. The EPC scope of work includes constructing gas compression facilities and associated pipelines, and expanding the Jafurah gas plant, including the construction of gas processing trains, utilities, sulphur and export facilities, Aramco said in a statement.
Fadhili gas plant expansion – Through the estimated $7.7bn project, Aramco aims to increase the Fadhili gas plant’s processing capacity from 2.5 billion cf/d to up to 4 billion cf/d. The expansion includes three new processing trains, each with a capacity of 500 million cf/d.
Aramco awarded contracts for four main EPC packages of the Fadhili gas plant expansion project in April 2024 to South Korean contractors Samsung E&A and GS Engineering & Construction and Saudi contractor Nesma & Partners.
Dammam development project – The project represents the second development phase of the Dammam field. Its objective is to install infrastructure, including pipelines, trunklines and pumps, to increase the field’s crude oil production capacity by 25,000 b/d and 50,000 b/d in separate phases.
Al-Khobar-based Denys Arabia won the main EPC contract for the Dammam second field development phase in July 2024. The contract was estimated to be worth more than $500m.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21156386/main4222.jpeg -
BP and PetroChina cut budgets for Iraq oil projects
5 November 2026
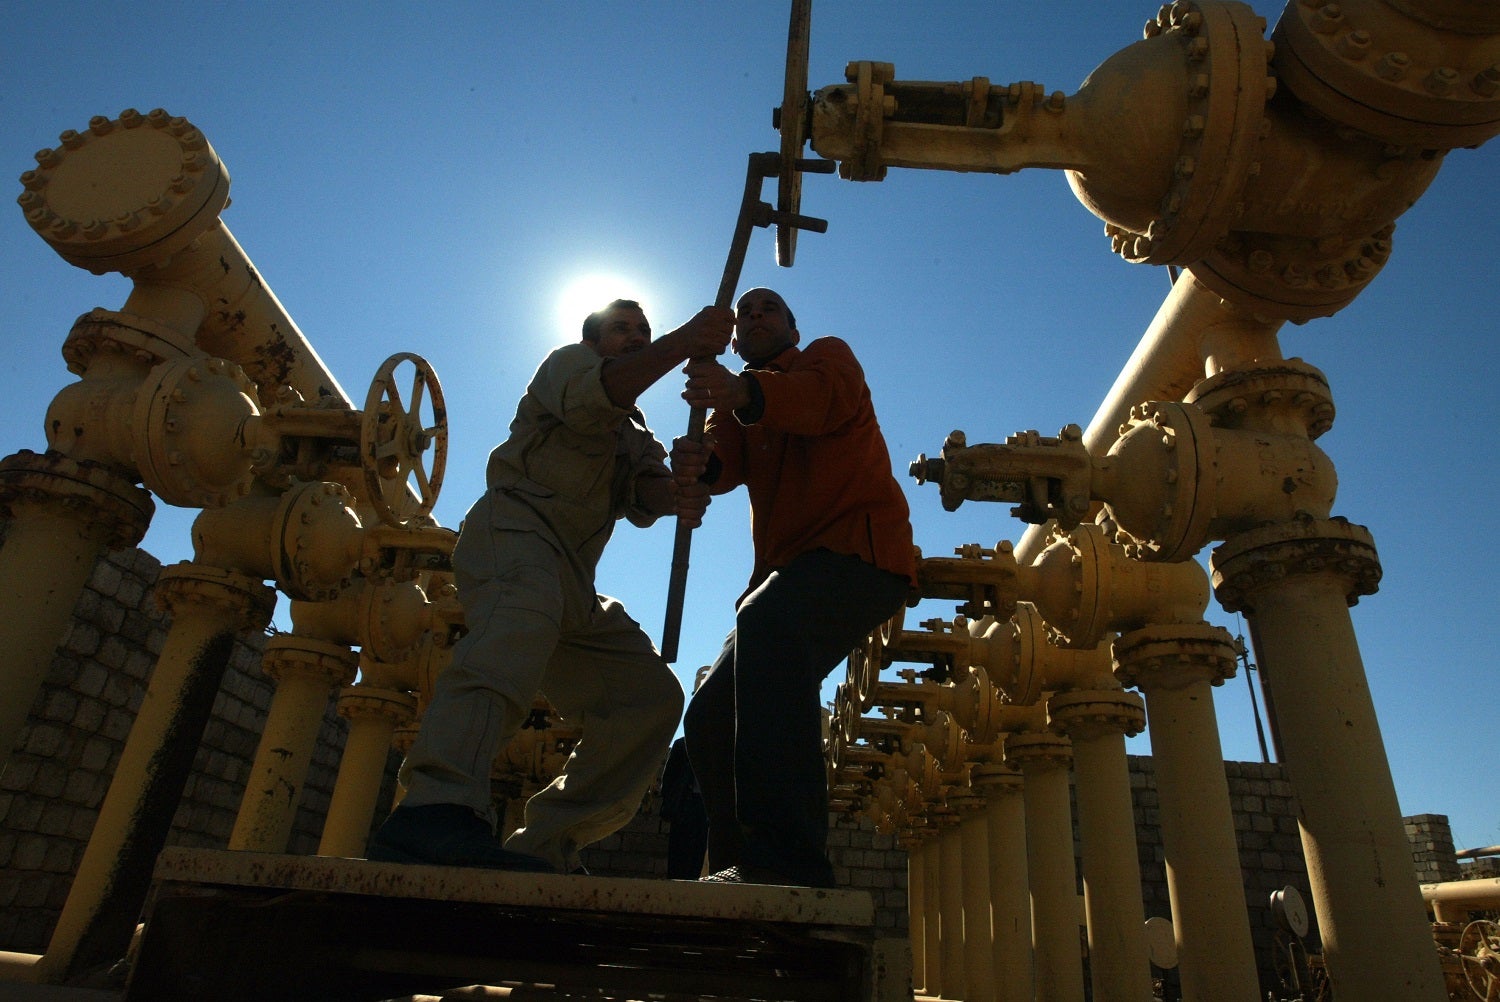
London-headquartered BP and PetroChina have agreed with Turkish contractor Tekfen to reduce the monthly allocated budgets for two upstream oil projects at the Rumaila field, according to industry sources.
Rumaila Operating Organisation (ROO) operates the Rumaila field.
ROO is a joint venture formed by state-owned Basra Oil Company; Iraq’s State Oil Marketing Organisation (Somo); and Basra Energy Company, a joint venture owned by UK-based oil company BP and PetroChina.
PetroChina is the listed arm of state-owned China National Petroleum Corporation.
As part of the agreement between ROO and Tekfen, progress on the projects will continue at a slower pace.
The two projects are both also suffering from delays due to problems importing equipment through the Strait of Hormuz, sources said.
One source said: “These projects are really barely alive. They are progressing very slowly after the monthly budgets were cut by the client. The project is still continuing, but at a slow pace. The budgets are very limited.”
Sources said that although the monthly budget payments were reduced, they were still being made on time.
Most of the problems that the projects at the oil field are facing are connected to the regional war, which started on 28 February when the US and Israel attacked Iran.
One source said: “The budget issues and financial problems are significant. There are also security concerns connected to reported US plans for a potential strategic nuclear strike on Iran and how that might impact operations at the Rumaila field, which is only around 60 kilometres from the Iranian border.”
The two projects have a combined value of less than $100m, and the project scopes include developing new facilities as well as upgrading and repairing existing upstream infrastructure.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21153848/main.jpg -
Read the November 2026 MEED Business Review
4 November 2026
Download / Subscribe / 14-day trial access The GCC projects market continues to show resilience against a deteriorating macroeconomic backdrop, with clients committing capital despite the regional fallout from the US-Iran conflict.
 According to the IMF, every GCC economy except Oman is projected to contract in 2026. Yet government-backed infrastructure spending has cushioned the blow, led by the UAE, where contract awards are up 6.1% year-on-year.
But beneath the headline figures, signs of a slowdown are emerging. Falling residential activity, a retreat in Saudi Arabia’s gigaproject spending and a sharp decline in tendering suggest that the market faces a tougher test as the conflict continues.
Read more in our November issue Agenda feature.
Our 22-page market focus on the UAE examines how state-backed capital, greater freedom to increase oil production following the UAE’s exit from Opec, and continued investment in energy, transport and water infrastructure are helping the country absorb the economic shock of the Iran conflict.
It also looks at how Abu Dhabi is adjusting its diplomatic approach, and the risks that remain for the wider economy.
This month’s industry report turns to project finance, examining how Gulf lenders are reassessing risk amid regional instability, higher costs and tighter credit limits. While infrastructure funding needs remain undiminished, the conflict is changing the way projects are financed, with lenders paying closer attention to physical security, insurance and risk allocation.
The report also examines the slowdown in public-private partnership activity across the Middle East and North Africa, where the value of awards has fallen sharply despite a pipeline of major deals still to come.
We also speak to WSP’s regional president Dean McGrail about the resilience of the Gulf construction market, the shift towards infrastructure investment and the opportunities emerging in aviation.
H&H chairman Shahab Lutfi discusses how the Dubai developer is pressing ahead with contract awards despite rising costs and softer sales, while the UAE Ministry of Energy & Infrastructure’s Mohammed Al-Mansoori explains how the country is strengthening supply-chain resilience and maintaining infrastructure delivery in the face of disruption.
Elsewhere, we examine the global stadium construction market, where annual spending is forecast to jump by 39% in 2027 as governments prepare for major sporting events, and look at the economic consequences of the Strait of Hormuz closure.
We hope our valued subscribers enjoy the November 2026 issue of MEED Business Review.
Must-read sections in the November 2026 issue of MEED Business Review include:
> AGENDA: GCC projects market holds its nerve
> INTERVIEW: Stability holds as project work continues
> INTERVIEW: H&H continues to deliver Dubai projects
INDUSTRY REPORT:
Project finance
> Project financiers hold the line
> PPP activity fades amid regional instability> INTERVIEW: Building resilience into infrastructure delivery
> STADIUMS: Stadium spending set to jump 39% in 2027
> REGIONAL CONFLICT: Hormuz closure wipes out growth in 2026
 > UAE MARKET FOCUS:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into production> MEED COMMENTS:
> Regional tensions strengthen the case for GCC rail
> Focus turns to the Northern Emirates
> Gulf data centre ambitions face delivery test
> Qatar buys LNG reliability beyond Hormuz> GULF PROJECTS INDEX: Saudi Arabia drives Gulf projects market higher
> SEPTEMBER 2026 CONTRACTS: Middle East contract awards
> ECONOMIC DATA: Data drives regional projects
> OPINION: When football meets politics
> BUSINESS OUTLOOK: Finance, oil and gas, construction, power and water contracts
To see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21089562/main.gif -
UAE economy shows resilience
4 November 2026
Commentary
Colin Foreman
EditorState-backed capital is carrying the UAE projects market through the economic shock of the Iran conflict. Government and government-related entities have accounted for $22.4bn of the $34.6bn of contracts awarded in Dubai so far this year, almost two-thirds of the total, according to regional project tracker MEED Projects. Private developers have deferred new launches, and off-plan residential sales in the emirate fell from $9bn in February to $4bn in August.
In Abu Dhabi, state-affiliated developers and cultural agencies are accelerating destination projects on Yas and Saadiyat islands, including the $1.7bn Sphere Abu Dhabi venue.
The energy sector is adding momentum. The UAE’s exit from Opec in May has freed Abu Dhabi National Oil Company (Adnoc) to make greater use of its spare crude capacity, and the company is on course to exceed its 2024 upstream project spending this year. Adnoc Gas has awarded $8.2bn of contracts for the second and third phases of its rich gas development programme.
The $3bn Taweelah C combined-cycle gas turbine plant accounted for most of the $4.17bn of power contracts awarded by early September, while Dubai’s AED30bn ($8.1bn) Tasreef stormwater programme is driving water sector activity.
MEED Projects tracks $103bn of transport schemes at pre-execution stages, including rail links that would give exporters routes that avoid the Strait of Hormuz.
Non-oil activity is also holding up. The UAE purchasing managers’ index compiled by financial information and analytics provider S&P Global reached a 20-month high of 55.3 in September. Net profits at the 10 biggest UAE banks rose 7% to AED47.8bn ($13bn) in the first half, supported by loan growth of 21%.
Meanwhile, Abu Dhabi is repairing relations with Riyadh after a year of friction over Yemen and Sudan. On 8 October, the two countries signed a memorandum of understanding covering power grid interconnection and freight rail.
Risks remain. The Washington-based IMF expects the GCC economy to contract by 3.8% this year, with recovery dependent on shipping through Hormuz returning to normal. US scrutiny of Iran-linked transactions is also tightening compliance demands on UAE banks. That said, there are reasons to be hopeful. The IMF expects the economy to rebound in 2027 with 7.7% GDP growth.
MEED’s November 2026 report on the UAE includes:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into productionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20947110/main.gif