The way forward for the region’s energy transition
12 December 2022
Published in partnership with

Whichever way one looks at it, the world faces a climate emergency. In its most recent multi-agency report published in September, the World Meteorological Organisation (WMO) warns that there is an almost one in two chance that the annual mean temperature in at least one of the next five years will be 1.5°C higher than the 1850-1900 pre-industrial average.
This figure is important because it would breach the maximum temperature rise set by countries under the terms of the 2015 Paris Agreement and underlines the lack of progress in reducing harmful emissions.
“Floods, droughts, heatwaves, extreme storms and wildfires are going from bad to worse, breaking records with alarming frequency,” said UN secretary-general Antonio Guterres in the report.
“Heatwaves in Europe. Colossal floods in Pakistan. Prolonged and severe droughts in China, the Horn of Africa and the United States. There is nothing natural about the new scale of these disasters. They are the price of humanity’s fossil fuel addiction.”
There are multiple ways to reduce global greenhouse gas emissions, with a common thread among them being using technology as a solution.
Whether by making gas turbines more efficient, producing new low-carbon or carbon-free fuels such as hydrogen, increasing renewable energy output, or ensuring homes, towns and cities are ‘smarter’ in their use of electricity, technological innovation presents a means for countries to lower their carbon outputs.
All [the reports] stressed we are not on track to keep climate change below 2 degrees, or even keep the 1.5 degree target within reach. More work needs to be done
Mohamed Nasr, Egypt's lead negotiator at Cop27
Scale of the problem
In the series of six articles MEED has published in association with Siemens Energy, we have explored the chief challenges the Middle East and Africa regions are facing in the fight against global warming and some of the opportunities and potential solutions to overcome them.
The first hurdle is recognising the scale of the climate challenge. The Siemens Energy Middle East & Africa Energy Week in June highlighted the disconnect between the perception of progress and reality, even among industry professionals.
When asked to quantify CO2 reductions in their country today and what they will be in 2030 compared to 2005, Energy Week participants estimated that total emissions had fallen by 23 per cent on average over the past 17 years. Only one-third correctly answered that emissions had not only failed to fall, but had actually risen by 50 per cent over the same period.
“All [of the reports] stressed that we are not on track to keep climate change below 2 degrees, or even keep the 1.5 degrees target within reach. More work needs to be done,” emphasised Mohamed Nasr, director of the Environment & Sustainable Development Department at Egypt’s Foreign Affairs Ministry and lead negotiator for Egypt at Cop27 during the event.
The harsh reality of the situation has underscored the pressing need for more rapid action among countries in the region. For the wealthier oil-exporting nations of the Middle East, much of the emphasis over the past 18 months has been placed on developing a green hydrogen industry to produce cleaner fuels. This is reflected by the more than 50 new green hydrogen projects announced in the GCC and North Africa over the past 18 months, which have an estimated investment value of more than $150bn.
On the other hand, the priority for many countries in sub-Saharan Africa is very different as they battle the energy trilemma of extending affordable and reliable electricity provision to their populations. Spending billions of dollars on greenfield hydrogen developments and their associated infrastructure is not an option for many. Instead, the focus has generally been on smaller, off-grid renewable energy capacity to resolve the trilemma.
 Working in tandem
Regardless of the approach adopted, the private sector recognises that companies need to work more collaboratively in the drive toward net zero. A case in point is the newly formed Alliance for Industry Decarbonization.
Announced in early September by the International Renewable Energy Agency (IRENA) and Siemens Energy, the alliance has already grown nearly threefold from the original 13 international energy and industrial members.
The new industry grouping aims to achieve country-specific net-zero goals faster by encouraging action to decarbonise industrial value chains and enhance the understanding of renewables-based solutions and their adoption by industry.
The alliance met for the first time at Cop27, where its members played a prominent role in discussions and thought leadership. Ultimately governments recognise that without corporates worldwide investing in clean energy projects and technology, there is little hope that targets will be achieved.
The intergovernmental summit ended on 20 November with a historic accord on setting up a fund to help compensate poorer nations for the economic and social destruction caused by climate change.
But while the agreement, a culmination of some 30 years of negotiations between developed economies and developing nations, was a major step in the right direction, there remains a lot more that needs to be done to avoid an environmental catastrophe, such as setting legally-binding emission reduction targets, for example.
The good news is that technologies and know-how are increasingly available to solve many of these challenges.
What is now needed is the political will and collaboration among nations and companies to work together to overcome our greatest threat.
In the words of Siemens Energy president and CEO Christian Bruch: “The energy transition is the biggest investment programme since the dawn of industrialisation. If governments, business and society work together, energy transition is a massive opportunity. There is no excuse for waiting any longer.”
Related reads:
- Working towards a common energy-transition goal
- New alliance forged to accelerate net-zero ambitions
- The journey towards net zero
- Solving Europe’s energy challenge
- Delivering the reality of the green dream
- Africa’s energy trilemma
- Region primed for global green hydrogen leadership

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Wison breaks ground on Abu Dhabi’s Habshan train 7
16 November 2026
-
 Meraas launches new Solaya phase in Jumeirah
16 November 2026
-
 Borouge puts butene-1 expansion project on hold
16 November 2026
-
 Contractor wins Saudi Energy substation deal
16 November 2026
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Wison breaks ground on Abu Dhabi’s Habshan train 7
16 November 2026
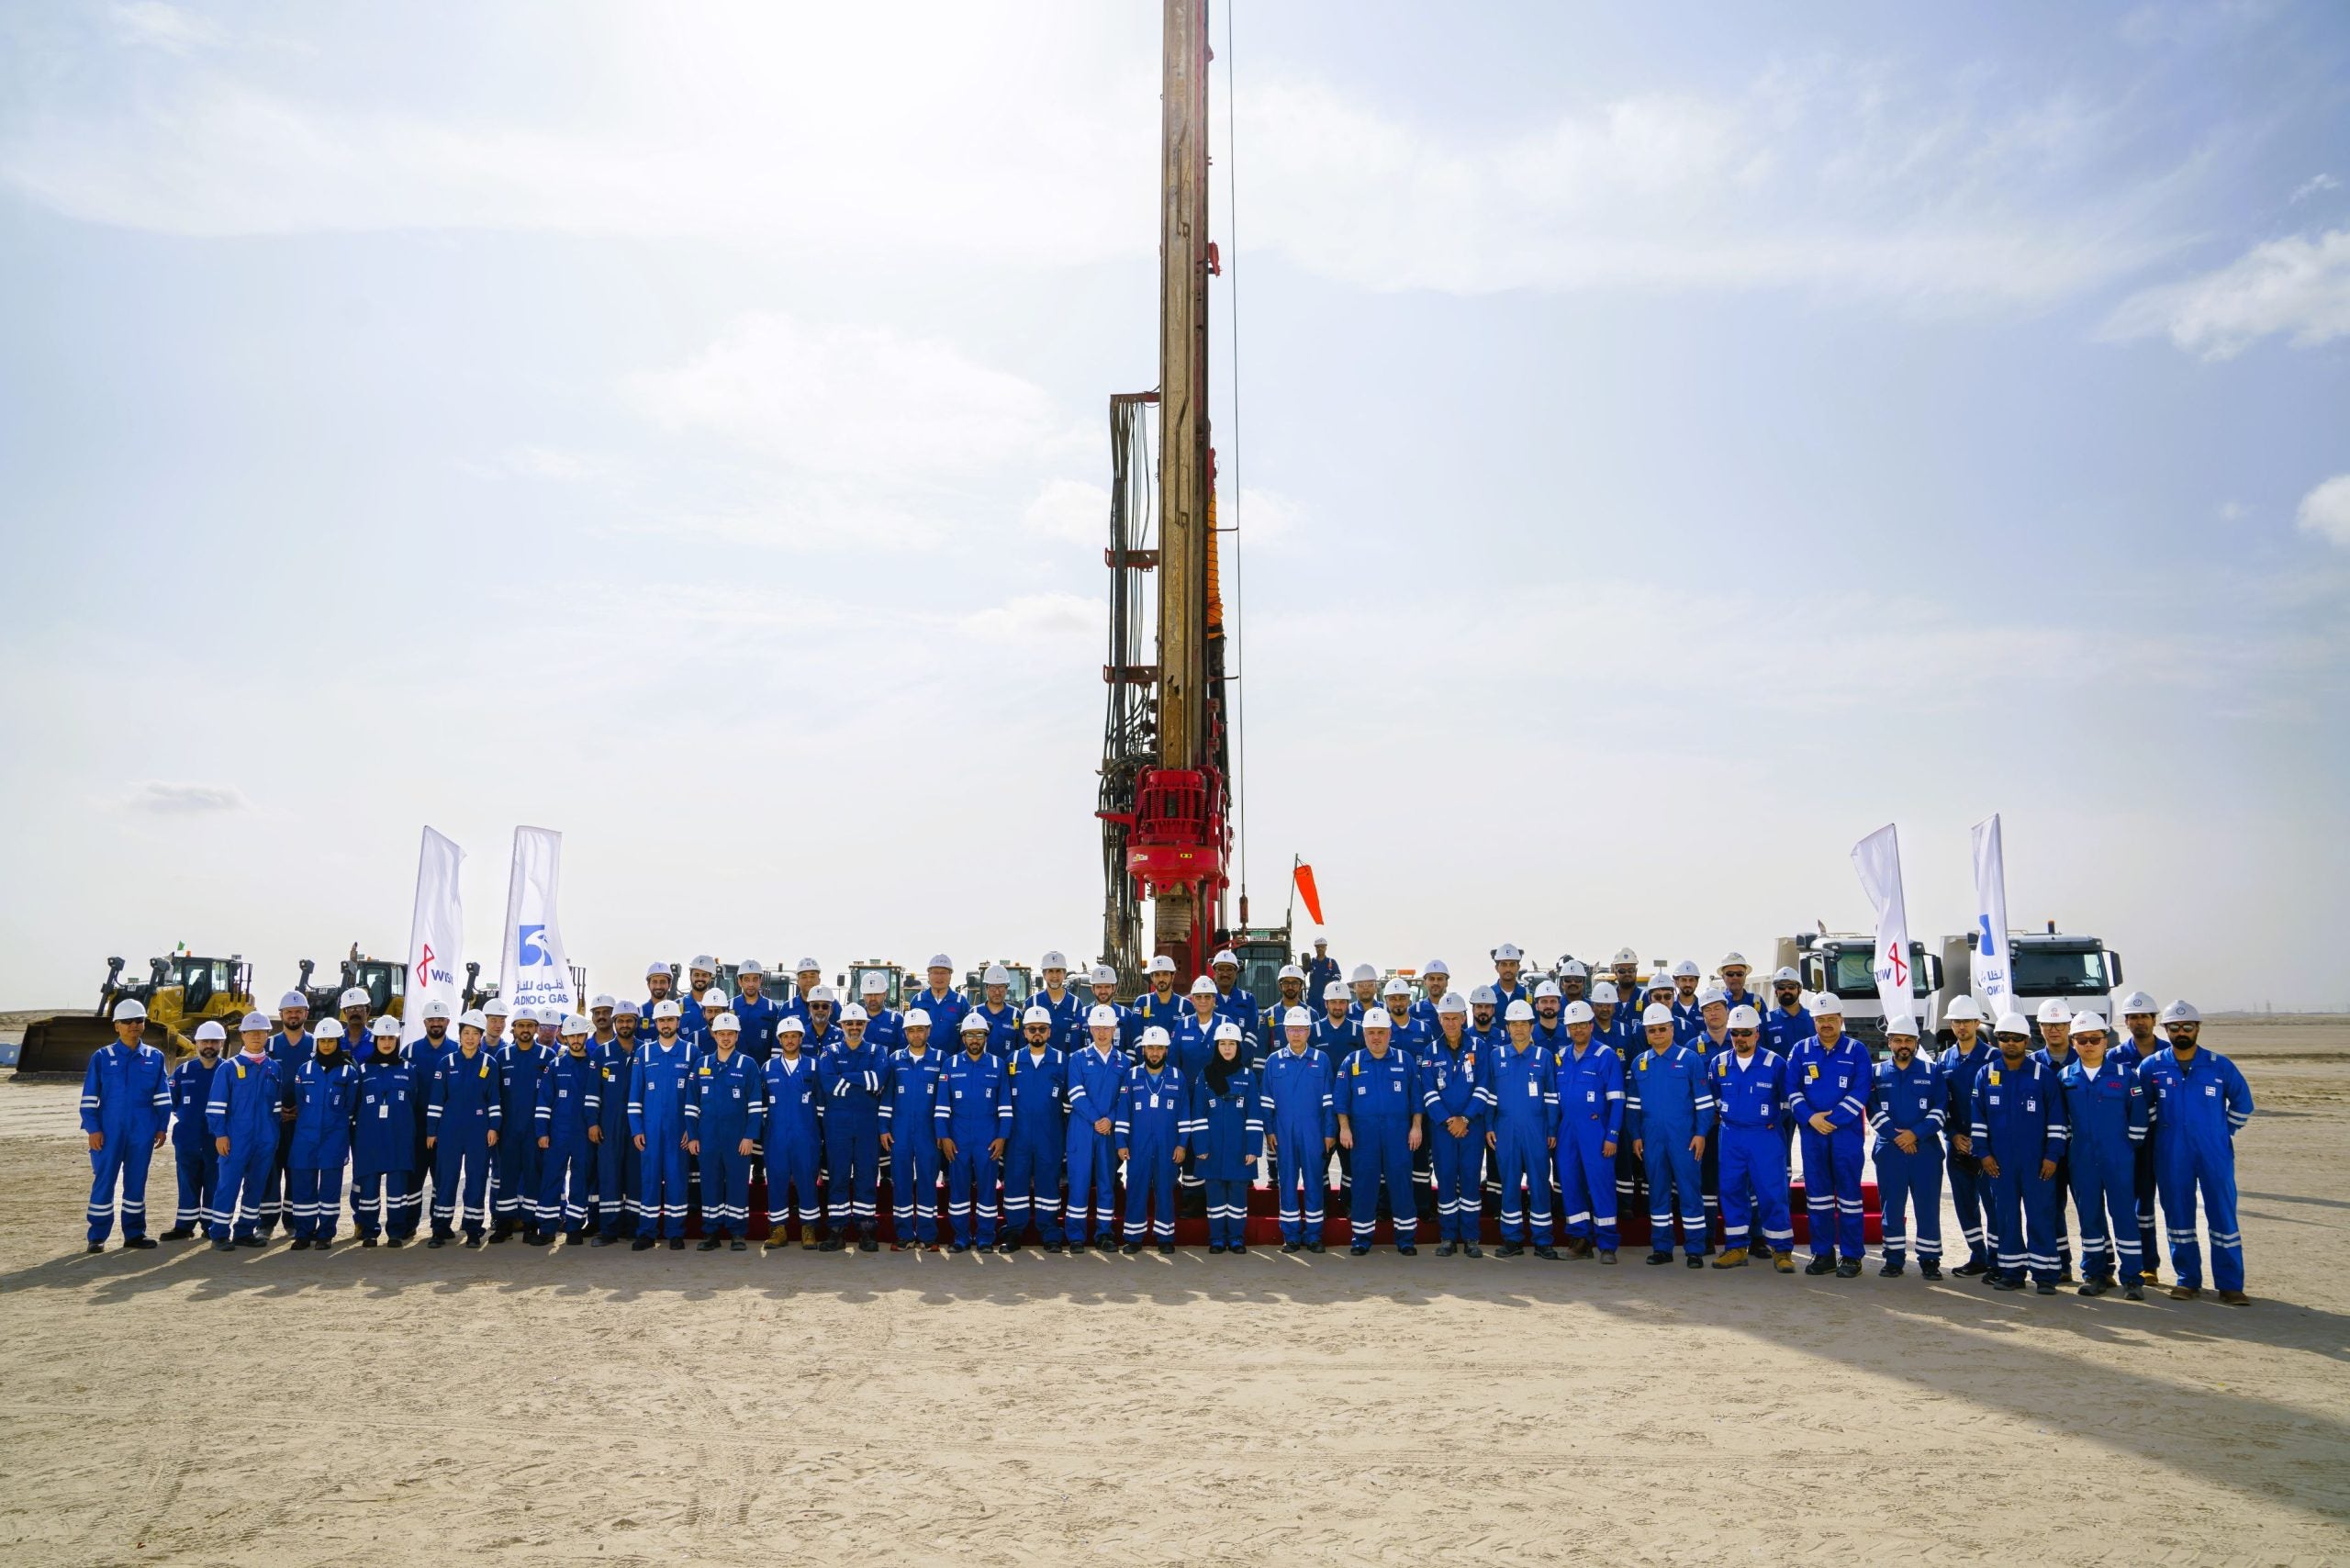
China-based Wison Engineering has held a groundbreaking ceremony for the second phase of Adnoc Gas’ Rich Gas Development (RGD) programme. The project covers the engineering, procurement and construction (EPC) of a seventh gas-processing train at the Habshan complex in Abu Dhabi.
Adnoc Gas, the natural gas processing subsidiary of Abu Dhabi National Oil Company (Adnoc Group), awarded Wison Engineering the $3.9bn EPC contract for the Habshan 7 project in August.
Wison said the RGD phase 2 contract is the largest in its history. Its scope includes gas pipelines, separation and condensate stabilisation units, acid-gas removal units and deep natural gas liquids (NGL) recovery units. The work also includes a 220kV switch station, bringing the total contract value to $4.04bn, according to the Hong Kong-listed contractor.
MEED previously reported that the groundbreaking ceremony for the Habshan 7 project would take place on 11 November.
Adnoc Gas plans to install the Habshan 7 train adjacent to the Habshan 5 train. This arrangement will allow the new train to use spare capacity in Habshan 5’s sulphur recovery and tail-gas treatment units, helping to optimise operations.
The full scope of work on the Habshan 7 gas train project covers the EPC of the following units:
- New high-pressure pipeline from the main Habshan complex to the new gas train
- Separation and condensate stabiliser unit
- Acid gas removal unit
- Mercury removal unit
- Deep NGL recovery unit
- Sales gas and residue gas compressor
- NGL product storage and transfer pump, as well as metering skid
- Utility units (IA, N2, PW, FW, steam generation, DM)
- Flare unit, to be located in Habshan 5 on common derrick
- Flare gas recovery package
- Water treatment package
- Non-process buildings, to be located outside the Habshan 5 train
- Power generation system – associated 220kV switch station
- NGL pipeline from Habshan 5 to Ruwais, based on an existing pipeline assessment
- Sales gas pipeline from Habshan 5 to sales gas network
UK-headquartered Wood Group completed the concept study and initial engineering design for Habshan 7.
Adnoc Gas also broke ground on the third phase of the RGD programme in September. This phase will add a fifth NGL fractionation train at the Ruwais complex. Italian contractor Tecnimont secured the $4.3bn EPC contract for the NGL-5 project in August. Once commissioned, the train is expected to produce more than 8 million tonnes a year of NGLs for export.
The RGD phases, together with the Ruwais liquefied natural gas export terminal, the Maximising Ethane Recovery and Monetisation scheme and the Estidama pipeline expansion, form part of Adnoc Gas’ previously announced $28bn capital expenditure program for 2026-30.
Financial performance
Adnoc Gas posted net income of $1.34bn for the third quarter, doubling its profit from the prior quarter. Revenue momentum and cost controls lifted quarterly ebitda by 70% sequentially to $2.03bn.
Domestic gas sales volumes grew 20% quarter-on-quarter, driving a 28% increase in domestic ebitda. International commercial activities expanded further, with export-traded liquids lifting international product ebitda by 106% sequentially, supplemented by a 249% surge in sulfur margins.
Operating cash flow reached $3.82bn for the first nine months, providing 1.35x coverage for the $2.82bn year-to-date dividend distribution. The board approved a third-quarter dividend of $940m (AED0.18 per share annualised), representing an indicated dividend yield of 5.34% and reinforcing the company’s position as the largest dividend payer on the Abu Dhabi Securities Exchange.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21447026/main00163733.jpg -
Meraas launches new Solaya phase in Jumeirah
16 November 2026
Dubai-based developer Meraas, part of Dubai Holding Real Estate, has launched a new phase of its Solaya beachfront residential scheme in Jumeirah 1. The project is being developed in partnership with BGRE, formerly Brookfield Properties.
The latest release comprises two- to five-bedroom residences, four-bedroom duplexes and a penthouse. In total, Solaya will feature 234 residences across nine buildings on a 40-acre site, offering direct beach access near J1 Beach, landscaped communal areas and private residential amenities.
UK-based Foster + Partners is the project architect, with 1508 London handling interior design. Dubai-based Brewer Smith Brewer Group (BSBG) serves as lead consultant, while US-based Aecom is the project management consultant.
Meraas and BGRE broke ground on the development in August, appointing Swissboring Overseas Piling Corporation to carry out shoring, excavation, piling and dewatering works.
The launch comes amid sustained momentum in the local market. According to GlobalData, the UAE construction industry will expand at an average annual rate of 3.9% between 2025 and 2027, driven by investments across infrastructure, energy, housing and tourism. The country’s residential construction sector is forecast to grow by an average of 2.7% annually between 2025 and 2028, supported by ongoing private development and government initiatives to meet population growth.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21446815/main.png -
Borouge puts butene-1 expansion project on hold
16 November 2026

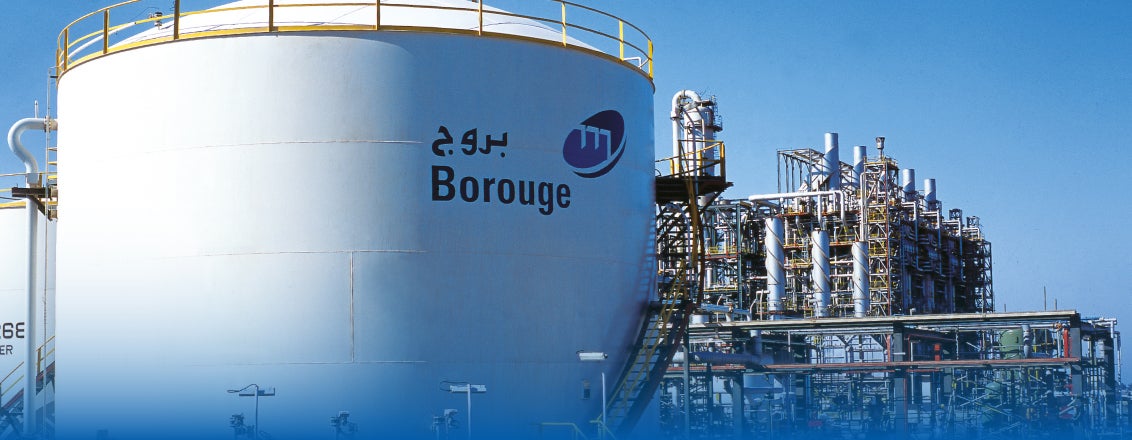
Abu Dhabi petrochemicals producer Borouge, now part of Austria-headquartered Borouge International, is said to have put on hold a project to increase butene-1 production from the olefins conversion unit (OCU) at its Borouge 2 facility in Ruwais Industrial City.
Under the proposed project, Borouge planned to produce 60,000 tonnes a year (t/y) of butene-1 from the existing fractionator column while limiting propylene production from the OCU to 500,000 t/y.
The company intended to achieve this by adding co-monomer production technology and selective hydrogenation units, while retaining the capability to run the unit at its original design capacity of 752,000 t/y of propylene and 39,000 t/y of butene-1. The scope also entailed expanding butene-1 storage capacity by converting existing N1 mixed-butane spheres into dedicated butene-1 units.
According to sources, Borouge informed contractors in the weeks after receiving bids that it had decided to shelve the tender.
Contractors submitted technical bids for the engineering, procurement and construction (EPC) package by 1 September 2025, following several extensions to the original 23 June deadline. Borouge had initially released an advanced tender notice in May last year, followed by the main EPC tender on 4 June, and hosted a site visit for bidders on 25 June.
Contractors understood to have submitted bids include:
- Galfar Emirates (UAE subsidiary of Oman’s Galfar Engineering & Construction)
- Target Engineering Construction (UAE)
US-based Lummus Technology was previously awarded the contract to provide the process design package for the new co-monomer production unit as the OCU licensor. Lummus sub-contracted the extended process design package and basic engineering works to South Korea’s Samsung E&A. Borouge had targeted an EPC contract award in the first quarter of 2026.
Butene-1 is a colourless gas primarily used as a co-monomer in the production of high-grade polyethylenes and poly(1-butene), serving end markets such as specialty films, bags and food packaging.
ALSO READ: Borouge prepares to tender construction works for ethane cracker expansion
Borouge International was formed through the combination of Adnoc Group and OMV’s shareholdings in Borouge and Austria-based Borealis, alongside the acquisition of Canada-based Nova Chemicals. In July, Adnoc announced it would transfer its holding in Borouge International to its global investment arm, XRG.
Borouge began operations in 2001 with 450,000 t/y of polyethylene capacity. The Borouge 2 and Borouge 3 expansions raised overall capacity to 2 million t/y in 2010 and 4.5 million t/y in 2014, respectively. Once the Borouge 4 expansion is commissioned, total production capacity will increase from 5 million t/y to 6.4 million t/y, creating the world’s largest single-site polyolefins facility.
Borouge 4 will add two polyethylene units with a combined capacity of 1.4 million t/y (700,000 t/y each) based on Borealis’s third-generation Borstar technology, supplied by a 1.5 million t/y ethane cracker and associated derivative units.
ALSO READ: Borouge restores Ruwais complex after Iranian attacks
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443754/main.jpg -
Contractor wins Saudi Energy substation deal
16 November 2026
Local firm Alfanar Projects has signed a contract with Saudi Energy, formerly Saudi Electricity Company, to build a 115/13.8kV substation in Al-Aqiq, Al-Bahah province, a source confirmed to MEED.
The station will receive electricity at 115kV and step it down to 13.8kV for local distribution. The scope of work includes site preparation, civil works, substation buildings and foundations, and the supply and installation of power transformers and associated electrical equipment.
Seventeen firms submitted bids for the project in May. The bidders included:
- Al-Babtain Contracting
- Al-Gihaz Holding
- Al-Haider Company
- Alfanar Projects
- Cepco
- Energy & Infrastructure Company (Eico)
- Expertise Contracting
- Haif Company
- JAL International
- Maetel Saudi Arabia Construction Company
- Mohammed Al-Ojaimi Group
- Nesma Infrastructure & Technology
- Nour Energy Company
- PA Cost International
- Sama Energy
- Saudi Projects & Supplies Company
- Tareg Al-Jaafari Contracting Establishment
According to regional project tracker MEED Projects, AlFanar Projects had won up to eight awards for substation projects this year, prior to the Al-Aqiq award.
The largest is a contract worth more than SR122m ($32.5m) to construct a 132/13.8kV substation for the Expo 2030 Riyadh site.
The firm was one of four contractors selected by Saudi Energy to deliver electricity infrastructure for the site, MEED reported in August.
Recent contracts include the 380kV Tumair PV substation (#9127), the Busita-C 132/33kV substation, the 132/13.8kV substation north of Al-Kharj (#8721) and the Al-Sahafa 132/13.8kV new substation (#8316).
Saudi Energy has tendered several other 380kV substations and associated transmission lines this year, including projects serving planned solar and wind developments in the kingdom’s central, western and southern regions.
Earlier, in November, MEED exclusively reported that China’s TBEA Shandong Luneng Taishan Cable Company (TBEA) and Egypt’s Elsewedy had submitted the lowest bids for two substation projects in Riyadh Province, estimated to cost a combined $100m.
The tenders for the Thadeq PV and Qiddiya 2 bulk supply points were issued earlier this year, with bids submitted in August and November, respectively.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443095/main.jpg -
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif