
Saudi lenders gear up for corporate growth
13 March 2024
 MEED's April 2024 special report on Saudi Arabia includes:
> GVT & ECONOMY: Saudi Arabia seeks diversification amid regional tensions
> UPSTREAM: Aramco spending drawdown to jolt oil projects
> DOWNSTREAM: Master Gas System spending stimulates Saudi downstream sector
> POWER: Riyadh to sustain power spending
> WATER: Growth inevitable for the Saudi water sector
> CONSTRUCTION: Saudi gigaprojects propel construction sector
> TRANSPORT: Saudi Arabia’s transport sector offers prospects

As Saudi Arabia’s once rapacious mortgage market slows down, lenders in the kingdom are building up their corporate loan books.
Banks’ exposure to the retail market is steadily reducing as the growth of the mortgage market – the big driver of credit growth in recent years – abates. Saudi lenders reported mortgage lending growth of 8% in the first nine months of 2023, compared to 19% in September 2022.
And where once the split between new business booked by Saudi banks was weighted 60:40 on retail and corporate, the split in 2023 was 50:50.
“We have noticed a decrease in Casa (current account and savings accounts). It used to be almost 70% a couple of years ago, but now it is close to 50%, and it means that the cost of funding is growing too,” says Anton Lopatin, senior director, financial institutions at Fitch Ratings.
Changing landscape
One component of this is the moderation of mortgage financing on the back of tightening subsidies and higher interest rates. “In general, the affordability of mortgage financing is less now and we see banks switching their focus to corporate lending. There’s a bit of reshuffling going on and we think that about 60% of the financing growth in 2024 will be from the corporate sector,” says Lopatin.
While Saudi Arabia's Vison 2030 projects have yet make little impact on local banks’ loan books, the expectation is that this will change, and that major economic diversification initiatives will yield good business for Saudi banks.
In the meantime, these lenders must deal with some near-term challenges in 2024, notably higher liquidity – a contrast to the situation in 2022, when financing growth of 14% outpaced deposit growth at 9%, and higher interest rates intensified competition for funding, according to Fitch Ratings. Data from the Saudi Arabian Monetary Agency (Sama) shows that the kingdom’s money supply surged 10% in January 2024 to reach SR2.72tn ($726bn).
That growth was primarily driven by a significant rise in banks’ term and savings accounts, which recorded a rise of 31% to reach SR864.32bn ($230.4bn). These deposits have attracted savings looking for higher yields.
Government reallocation
Another trend has been that government-related entities (GREs) have made moves to increase deposits in the banking system. According to Fitch, liquidity has been supported by increased deposit inflows from GREs, which grew by SAR147bn ($39.2) or 23% in the 12 months to the end of October 2023. Another ratings agency, S&P, noted that the contribution of government and GRE deposits increased to 30% of the total by 2023 from almost 20% in 2020.
According to Fitch, these inflows are mainly term deposits, which are an expensive source of funding for banks. This increase, plus higher competition for funding, has significantly raised the average cost of funding for Saudi banks; it rose to 2.7% in the first nine months of 2023, compared to just 0.4% in 2021.
“There’s been a change in how the Saudi authorities are managing GRE liquidity,” says Lopatin, who notes that GREs are now choosing to invest their surplus liquidity in higher income-generating deposits with commercial banks, rather than with Sama.
“Since July last year, we’ve seen a significant increase in government-related deposits in the banking sector. And we understand they have adjusted this approach, and now the government entities directly deposit with banks, instead of using the central bank as an additional chain into distribution of liquidity. That is also more efficient.”
Challenging conditions
Banking conditions in Saudi Arabia are looking more challenging in 2024 than in previous years. As Fitch notes, Saudi banks on average saw financing growth slightly above 10% for 2023, and the expectation is that growth will also be about 10% in 2024 – below the expansion of 14% seen in 2022.
Some banks that used to have stronger net margins have reported declines because of the focus on mortgage financing –which is under fixed rates in the kingdom – in conjunction with an increased cost of funding on the back of a declining proportion of Casa accounts. For example, Al Rajhi Banking & Investment Corporation reported that funding costs increased by 74% in year-on-year terms in 2023.
“Al Rajhi’s margins were under pressure last year but are now roughly in line with the sector average of 3.2%,” says Lopatin.
In general, UAE banks reported stronger margins than Saudi banks in 2023, says Lopatin. This is because, in combination with tightening liquidity, Saudi lenders have less ability to manage their margins.
Corporate lending in the kingdom will likely receive a boost from Vision 2030 projects.
“We expect more Vision 2030-related financing to appear on banks’ books this year. It’s still not very material, but most banks want to participate as they see these projects as having a decent balance between risk and reward,” says Lopatin.
Rating agency S&P has said that Saudi banks will need stronger access to international capital to sustain growth and continue financing projects related to Vision 2030. For now, the dependence of Saudi banks on external funding is limited.
Over the long-term, if Saudi banks do build more external debt, that could pose another challenge. International investors now have sustainability at the centre of their investment mandates, and local lenders will also need to look more seriously at their own sustainability metrics.
For example, last year, a panel of UN-appointed human rights specialists was reported to have sent letters to Saudi Aramco and financiers including Citi, Goldman Sachs and BNP Paribas, noting that their financing of the state energy company may be in violation of global human rights rules due to the company’s contribution to climate change. The letter urged the banks to take reasonable steps to prevent or mitigate the impact.
If Saudi banks do become major lenders to Vision 2030 schemes, and therefore need to source funds from outside the kingdom, they too will have to acclimatise to the new global reality – even if that is not a pressing requirement right now.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Riyadh tenders Expo 2030 Adaptation and Innovation Pavilion
21 October 2026
-
 Mubadala Bio lands Lilly logistics deal
21 October 2026
-
 Chinese/local joint venture wins Qiddiya stadium facade
21 October 2026
-
 Zamil Steel wins $82m Qiddiya tennis centre contract
21 October 2026
-
 Eni starts to bring gas processing facility online in Egypt
21 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Riyadh tenders Expo 2030 Adaptation and Innovation Pavilion
21 October 2026
Register for MEED’s 14-day trial access
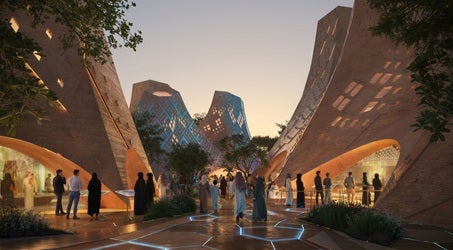
Expo 2030 Riyadh has tendered the design-and-build main contract for the Adaptation and Innovation Pavilion in the exhibition’s Technology District.
The pavilion will be built on a plot of at least 12,710 square metres and will feature a two-level basement, ground-level public areas, an elevated skywalk, visitor experience areas, food and beverage outlets, retail space, VIP facilities, offices, back-of-house areas, exhibition spaces, an amphitheatre and a resonance hall.
The facility is being designed to accommodate a minimum of 20,000 visitors a day at peak periods, with an anticipated average of about 15,000 visitors a day. The project targets LEED Gold certification.
The tender was issued on 1 October, with bids due on 6 January 2027.
The design-and-build contractor will be responsible for completing, reviewing, verifying, coordinating and technically integrating the design, including specialist contractor design portions and coordination with the novated lead design consultant.
The scope includes completing early works and substructure activities, including grading, bulk earthworks, excavation, cut and fill, soil improvement, raft foundations, reinforced-concrete basement walls, basement columns through to the ground-floor slab, waterproofing, mechanical, electrical and plumbing (MEP) provisions, and backfilling.
The contractor will also deliver the superstructure and building envelope, including structural works, facade engineering and installation, roofs, waterproofing, external finishes, and permanent facade access and maintenance systems. The internal works will cover front-of-house and back-of-house areas, public and core spaces, internal finishes, fixtures, fixed fittings, joinery, circulation areas, lobbies, stairs, toilets, storage, waste areas and associated builder’s works.
The building services package includes MEP systems, information and communications technology, extra-low-voltage systems, building management systems, security, fire and life safety systems, specialist lighting and vertical transportation.
The contract also covers the visitor experience package, including procurement, installation, integration, testing, commissioning and handover of visitor-facing environments, media, immersive and audiovisual technologies, interactive elements, experiential lighting, digital content, interpretive and wayfinding systems, controls and supporting infrastructure.
Within-plot infrastructure and utilities, landscaping, public realm works, paving, planting, irrigation, signage, street furniture, drainage, stormwater systems, external lighting, security, and fire and life safety systems are also included.
The contractor will be responsible for procurement, off-site fabrication, construction, testing and commissioning, performance verification, training, operations and maintenance documentation, operational readiness, handover, defects rectification and close-out.
The main works tender is based on a 60% RIBA Stage 3 design, with the Stage 3 design to be completed to 100% through an addendum.
Early works and substructure works, as well as the lead design consultant, will be novated to the contractor. Visitor experience works are included as a provisional sum.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20801465/main.jpeg -
Mubadala Bio lands Lilly logistics deal
21 October 2026
Mubadala Bio, the life sciences subsidiary of Abu Dhabi state investor Mubadala Investment Company, has signed an agreement with US drugmaker Eli Lilly to localise the packaging and logistics of Lilly’s glucagon-like peptide-1 (GLP-1) medicines in Abu Dhabi.
The work will take place at a 125,000-square-metre site in Khalifa Economic Zones Abu Dhabi (Kezad), which includes packaging and warehousing facilities. Mubadala Bio said the facilities would strengthen its pharmaceutical contract manufacturing, packaging and logistics capabilities and its ability to serve international clients from the UAE.
The packaging and logistics activities will be introduced in phases and will be subject to technical, quality and regulatory requirements. The companies did not disclose the value of the agreement or a timeline for the first phase.
The Emirates Drug Establishment approved Lilly’s oral GLP-1 drug Foundayo (orforglipron) for chronic weight management in April. The companies said this made the UAE the second country in the world to register the medicine.
In Abu Dhabi, the treatment is available to eligible patients under a weight management programme launched by the Abu Dhabi Department of Health and the Abu Dhabi Public Health Centre in June 2025. The UAE was also an early launch market for Lilly’s injectable treatment Mounjaro (tirzepatide) in August 2022.
Mubadala launched Mubadala Bio in 2025 to expand domestic drug manufacturing and distribution, with a focus on national drug security. It is one of Mubadala’s designated national champions, set up to support strategic sectors. At launch, its combined facilities covered 110,000 square metres, with an annual capacity of more than 2.5 billion tablets and capsules and 120 million intravenous and injectable units.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20801279/main.jpg -
Chinese/local joint venture wins Qiddiya stadium facade
21 October 2026
Register for MEED’s 14-day trial access
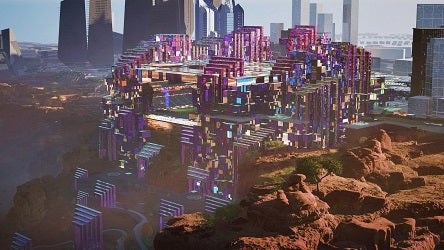
A joint venture of China’s Fangda Group and Saudi Arabia’s IKK Group has secured a SR1.15bn ($306m) contract to deliver curtain wall facade works for the Prince Mohammed Bin Salman Stadium in Qiddiya City, Riyadh.
The contract was awarded by the joint venture of Spain’s FCC Construccion and local contractor Nesma & Partners, which is building the stadium under an estimated SR15bn ($4bn) main contract awarded by Qiddiya Investment Company (QIC) in October 2024.
The IKK-Fangda joint venture will design, supply and install curtain wall façade systems for the main stadium (Lot 1), as well as for the museum and ancillary buildings (Lot 3).
The contract has an execution period of 863 days.
The stadium will seat about 47,000 spectators and will be the home ground for Saudi Pro League clubs Al-Nassr and Al-Hilal.
The facade award follows the appointment of Elegancia Arabia, a subsidiary of Qatar-based Elegancia MEP and Estithmar Holding, to deliver the stadium’s mechanical, electrical and plumbing works.
The SR829m ($221m) contract is Elegancia Arabia’s largest award in Saudi Arabia to date.
The project is being designed by US-based consultant Populous.
It is among the venues planned for the 2034 Fifa World Cup and will also host the Saudi King Cup, the AFC Asian Cup and the 2034 Asian Games.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20799367/main.jpg -
Zamil Steel wins $82m Qiddiya tennis centre contract
21 October 2026
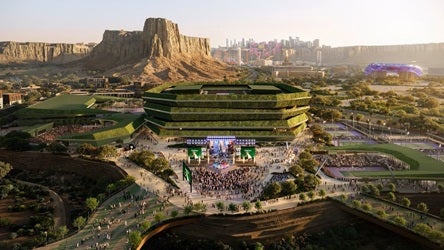
Advanced Building Industries Company (Senaat) has announced that its subsidiary, Zamil Structural Steel Company (Zamil Steel), has secured a SR308m ($82m) contract for the National Tennis Centre in Qiddiya City, Riyadh.
The 19-month contract was awarded by the joint venture of France’s Bouygues Batiment International and local contractor Almabani General Contractors Company.
Zamil Steel’s scope includes the fabrication, supply and installation of structural steel and external facades for the scheme.
MEED reported in June that the Bouygues Batiment International-Almabani joint venture had started construction of the National Tennis Centre.
The development will include 30 tennis courts, comprising 28 hard courts and two clay courts. The main Centre Court will seat 15,000 spectators and feature a retractable roof.
The facility is being designed to meet standards set by the Association of Tennis Professionals, the Women’s Tennis Association and the International Tennis Federation.
The development will also include an 8,000-seat multipurpose arena with a retractable roof, known as Court 3. Other facilities include a 5,000-seat Court 1, a 2,000-seat Court 2, six competition courts, six indoor courts and 14 practice courts. Each outdoor match court will provide 450 seats.
Total seating capacity across the complex will be 33,000. US-based architect Populous designed the project.
Qiddiya Investment Company officially announced the project on 15 June. The developer has said the centre will be the region’s largest tennis complex and will host international tennis events.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20799055/main.jpg -
Eni starts to bring gas processing facility online in Egypt
21 October 2026
Register for MEED’s 14-day trial access
Italy’s Eni has started to bring its Meleiha Phase 2 (MP2) project online in Egypt’s Western Desert, according to statements from the company and Egypt’s Ministry of Petroleum & Mineral Resources.
The project includes a new gas processing facility designed to process up to 100 million standard cubic feet of gas a day.
Eni is a part owner of the project through Agiba Petroleum Company, a joint venture of Eni and state-owned Egyptian General Petroleum Corporation (EGPC)
The main contract for the project was awarded to the Egyptian engineering, procurement and construction (EPC) company Petrojet.
The scope of the project included:
- Laying 200 kilometres of pipeline
- Drilling 28 wells
- Construction of a gas sweetening unit
- Construction of a gas recovery unit
- Installation of gas purification and liquids separation units
- Installation of utilities and supporting infrastructure
- Construction of natural gas processing plant
- Construction of associated facilities
In its statement, Eni said: “The project represents a key milestone in the development of a new gas hub within the Merged Meleiha concession and will significantly increase the gas processing capacity for production from the area’s fields, supporting the growth of domestic gas output and the valorisation of Egypt’s energy resources.”
The Meleiha and Meleiha Deep concessions were combined into a single concession known as the Merged Meleiha concession in 2021.
Eni said that the new facilities “will ensure the connection of new production to Egypt’s existing gas infrastructure, enabling the rapid monetisation of resources and enhanced operational efficiency”.
It added: “The launch of the project confirms Eni’s role as a strategic partner of Egypt and reaffirms the company’s long-standing commitment to contributing to the country’s energy security through the development and valorisation of the Western Desert’s diversified resource base, one of the most promising areas of Egypt’s energy sector.”
Eni has been present in Egypt since 1954 and produced approximately 242,000 barrels of oil equivalent a day in the country on an equity basis in 2025.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20788394/main.gif