Saudi demand-supply imbalance needs action
26 January 2024
Some $879bn-worth of giga projects are planned in Saudi Arabia, of which about $50bn has been awarded to date, according to regional projects tracker MEED Projects.
The data shows that 2023 was a record year for projects in Saudi Arabia.
However, the extensive scope of work associated with these projects has exposed the challenges of scaling up the local construction supply chain fast enough to meet the surge in demand.
With projects launching in quick succession, suppliers, contractors and subcontractors are struggling to keep up with the influx of new work into the market.
Riad Bsaibes, president and CEO of Amana Investments, says this shortage of resources is a critical issue, stating, “There is currently a bottleneck in the entire supply chain, from human capital and materials to subcontractors and general contractors.”
Moreover, the construction sector faces significant execution risks.
While some projects are subject to delays, efforts to accelerate others are exerting pressure on timelines and budgets.
Highlighting the disparity, Bsaibes notes, “This mismatch is leading to delays as schedules stretch out and costs rise above original tender amounts. This creates risks for contractors if they cannot deliver projects on schedule or within the costs estimated during the tendering process.”
Career investment
The launch of Saudi Arabia's Vision 2030 has spurred an era of growth and investment. The surge in construction projects aligns with the kingdom's goals, positively impacting employment opportunities.
Yet recruiting top local and expatriate talent across large-scale projects is becoming a challenge in Saudi Arabia, according to Bsaibes.
He acknowledges that attracting and retaining skilled workers is getting more difficult with time, stating: “This is particularly challenging due to the scale of expansion, coupled with the pressure of Saudi Arabia’s nationalisation policies that encourage contractors to recruit qualified Saudi nationals.”
As well as focusing on hiring practices, companies must also commit to nurturing and enhancing skills over time.
Continuous upskilling is crucial in the construction industry, where new technologies, techniques and regulations frequently emerge, requiring employees to adapt and stay relevant.
Bsaibes advocates a strategic approach to talent management that involves upskilling the existing workforce before hiring new talent.
He recommends a hands-on approach to learning and improving skills.
“A core part of skills development at Amana includes on-the-job training for all employees,” he adds.
“Skills development must extend to developing competency in cutting-edge technologies such as building information modelling (BIM), modular construction and other digital tools. This long-term effort should be a key priority for firms.
“Continuous learning and development are very important throughout an employee’s career, starting from their initial entry into the construction workforce.”
Bsaibes further highlights the significance of internships in providing candidates with practical experience before taking on permanent positions.
This approach aims to facilitate a smoother onboarding process for individuals entering the workforce, ensuring they are well-prepared for new roles.
“Companies should invest in the professional development of their employees,” he says. “This could include training programmes, workshops and educational initiatives aimed at enhancing the skills, knowledge and capabilities of the workforce.”
Credit challenge
Access to credit is another major issue in the construction sector. A strong financial profile enhances borrowing capacity and facilitates the smooth execution of projects by ensuring a steady flow of financial resources.
Addressing credit concerns is, therefore, essential for construction firms.
Bsaibes recommends adhering to a strategic financial approach, opting to retain significant cash reserves instead of incurring debt.
“This approach not only facilitates self-financing for projects when necessary, but also serves as collateral for the letters of guarantee frequently demanded in construction contracts.
“Moreover, it provides the company with the flexibility to navigate through any payment delays without succumbing to financial distress.
“Amana has a strong balance sheet and well-established banking relationships,” he adds. “Banks view Amana as low risk due to its solid cash reserves and strong track record of on-time payments across different regions/currencies.”
In contrast, Bsaibes points out that many other contractors struggle due to insufficient cash flow management and weaker balance sheets.
“Maintaining high cash levels on its balance sheet is a fundamental goal for Amana.”
Strong working capital allows the contractor to be selective in bidding for projects, avoiding low-margin work while still securing sizable contracts.
“Additionally, we have a positive history with lenders, which allows Amana to support its operations and capitalise on growth opportunities.”
Incentivising growth
Clearly, there is a need for industry-wide improvements.
Bsaibes says the most impactful change would be longer-term transparency across developers’ project pipelines.
“This approach contrasts with the unpredictable, stop-start demand cycles currently prevalent in the industry.
“It involves providing the supply chain with visibility into funding-backed plans over a three to five-year period. Such transparency is crucial for better resource planning and timely project delivery,” he adds.
Bsaibes also emphasises the importance of incentivising suppliers, subcontractors and contractors to scale up their capacity. “This will help them grow in a coordinated manner through financial/regulatory support from the government.”
Another area of improvement is the digitisation of government processes, although Bsaibes notes that progress is already being made.
Bsaibes also calls for changes in Saudi Arabia’s regulatory environment.
The continued maturation of Saudi Arabia’s evolving regulatory framework will reduce the complexities faced by international firms. Yet, greater alignment with global construction norms will stimulate competition and investment in the kingdom’s expanding market.
According to Bsaibes, transitioning contract law closer to international standards, such as those outlined by the standards organisation International Federation of Consulting Engineers (FIDIC), would significantly mitigate risks for new market entrants. Presently, the reliance on sharia law introduces an element of unpredictability into obligations, he says.
To achieve this, he recommends adopting contract laws aligned with common law systems, such as the UK’s, to provide foreign suppliers and partners with a clearer understanding of their obligations.
Bsaibes concludes that while the continued evolution of Saudi Arabia’s regulatory environment will take time, gradual alignment with international construction norms will ultimately ease risks and costs for both local and global industry players.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Oman announces $790m industrial investment deals
30 October 2026
-
 Sabic swings back to profit in Q3 with $224m net income
30 October 2026
-
 Saudi Arabia’s NWC awards package 12 of sewage scheme
30 October 2026
-
 H&H continues to deliver Dubai projects
29 October 2026
-
 Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Oman announces $790m industrial investment deals
30 October 2026
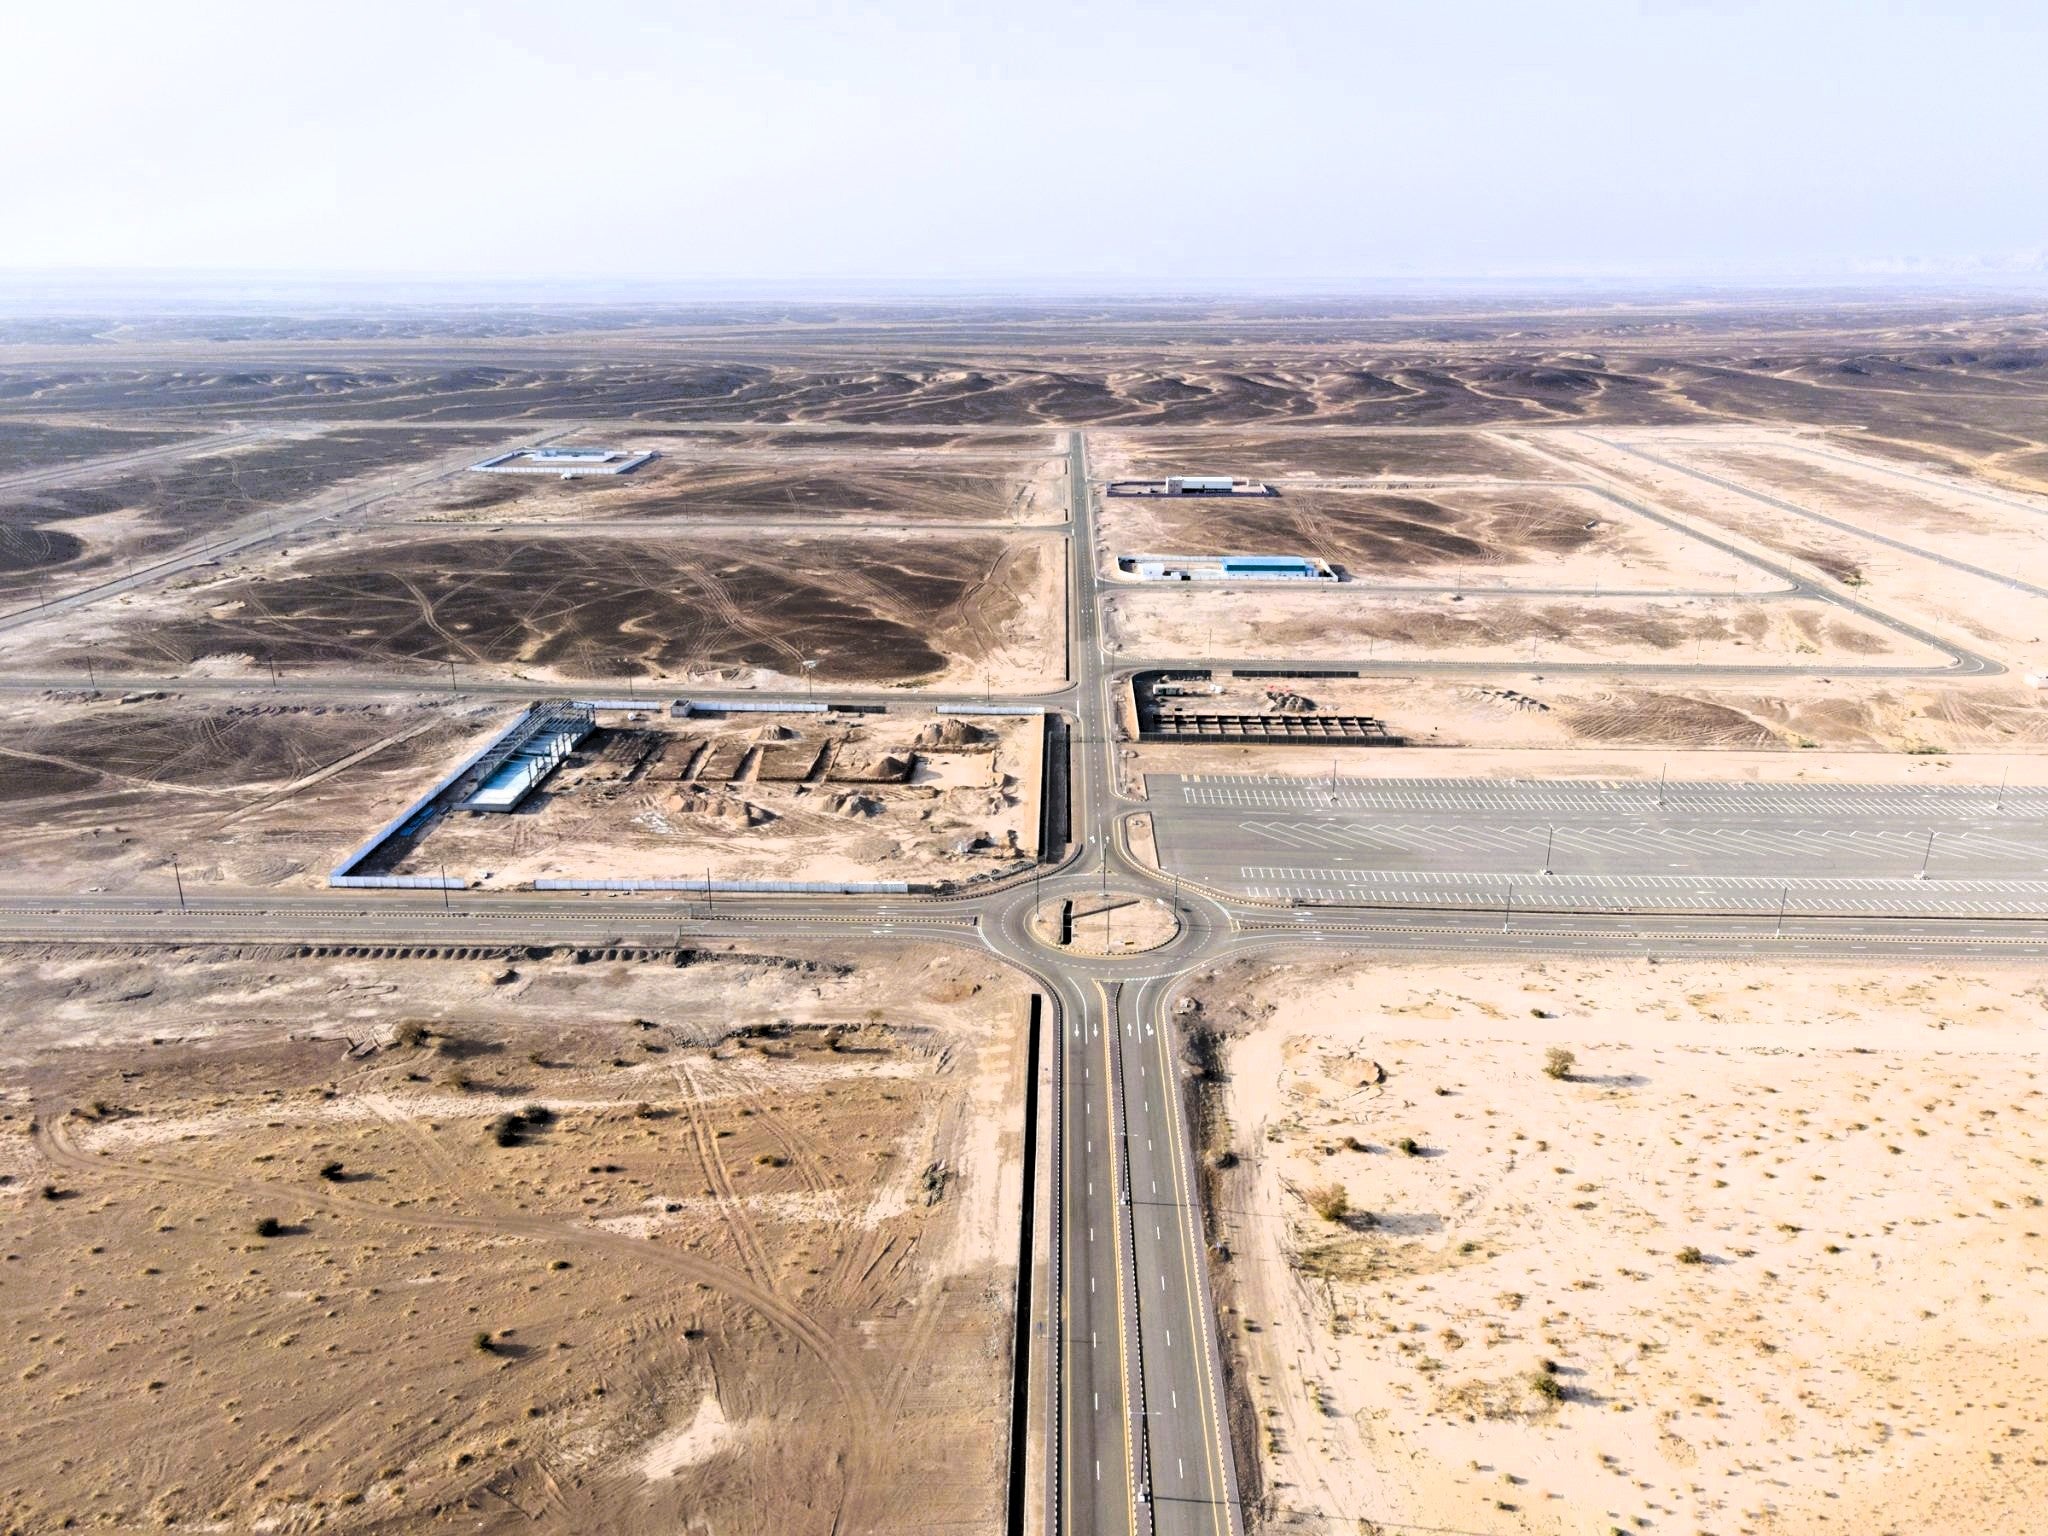
Oman’s Public Authority for Special Economic Zones and Free Zones has signed 28 investment agreements worth more than RO304m ($790m) for new projects and expansions across the country’s special economic zones, free zones and industrial cities.
The agreements cover more than 2 million square metres (sq m) of land and span industrial manufacturing, food production, logistics, recycling and commercial activities.
About $383.6m of the investment has been allocated to industrial cities operated by the Public Establishment for Industrial Estates (Madayn). Sohar Free Zone accounted for $152m, followed by the Special Economic Zone at Duqm (Sezad) with $143.1m, Salalah Free Zone with $85.6m and Khazaen Economic City with more than $27m.
The projects are expected to support Oman’s efforts to diversify its economy, expand industrial production and attract private investment in line with Oman Vision 2040.
Investment deals
In Sohar Industrial City, Atlas Steel will invest more than $291.1m in a plant producing iron and steel products on a site of about 440,000 sq m.
Fujian Mancheng Industries & Investment will invest $52m in a ceramics facility covering more than 241,000 sq m. Other investments in Madayn’s industrial cities include an $18.2m phosphate and nitrogen fertiliser plant planned by Gulf Company for Organic and Biological Fertilisers in Raysut, as well as projects involving structural metal products, paper and corrugated cardboard, and oil and gas equipment and services in Raysut, Ibri and Nizwa.
In Sohar Free Zone, Sohar Automotive & Advanced Industries Company will invest $98.8m in an automobile assembly complex covering 317,000 sq m. The complex aims to attract vehicle manufacturers, automotive supply-chain companies and advanced-manufacturing businesses.
Voltamp High Voltage Transformers has announced a $39m investment in a plant that will produce power and electrical-distribution transformers for regional and international markets.
Lalan Middle East will invest a further $3.9m to expand its medical-device manufacturing facility.
ALSO READ: Oman’s Madayn prepares $637m investment drive
In Sezad, Al-Jazir Feed Plant will invest $104m in a shrimp-feed facility to support an integrated shrimp-farming project.
In Salalah Free Zone, Al-Nawras Industries will invest $50m in a steel-structures manufacturing facility, while Integrated Gypsum Company will invest $20m in gypsum-products production. Marai Dhofar will invest $15.6m in the production of Italian cheeses and other dairy products.
Projects in Khazaen Economic City include a plant by Aleemit International Services to manufacture electric-vehicle chargers and components, with an investment of more than $8.8m, and a $6.5m facility by Joger Modular Building Technologies to produce precast-concrete building components.
Additional investments in Khazaen include construction materials, ready-mix concrete, industrial units, logistics facilities and warehouses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21016368/main.jpg -
Sabic swings back to profit in Q3 with $224m net income
30 October 2026
Register for MEED’s 14-day trial access
Saudi Basic Industries Corporation (Sabic) returned to profitability in the third quarter of the year, reporting adjusted net income of SR840m ($224m) as revenue and earnings improved from the previous quarter.
The Saudi chemicals giant had posted an adjusted net loss of $100m in the second quarter.
Revenue increased 14% on a quarter-on-quarter basis to $7.51bn, while adjusted earnings before interest, taxes, depreciation and amortisation (Ebitda) climbed 40% to $1.27bn. Adjusted Ebitda surged 434% to $578.67m.
Sabic’s net debt stood at $808m as of 30 September compared with $728m as of 30 June.
Adjusted earnings per share rose to SR0.28 ($0.07) from a loss of SR0.13 ($0.03).
The recovery occurred despite persistent margin pressure across the global petrochemicals sector and heightened geopolitical risk in the Middle East.
Additionally, Sabic said it achieved $949.33m of its broader portfolio optimisation programme target of $3bn by 2030 in positive recurring Ebitda impact from its transformation efforts.
During the third quarter, Sabic received its Local Content Certificate for 2025 from the Local Content and Government Procurement Authority, recording a score exceeding 61% – an increase of more than nine percentage points over the prior evaluation period. The company attributed the increase to domestic procurement agreements, including a memorandum of understanding with Lenovo.
Capital projects
After several years of subdued project spending, Sabic is beginning to step up investment in new production capacity, with major projects reaching key milestones this year.
In February, affiliate Petrokemya awarded China National Chemical Engineering Group Corporation the main engineering, procurement and construction (EPC) contract for a new ethylene oxide catalyst production facility. The 4,000-tonne-a-year (t/y) unit at Jubail Industrial City includes catalyst carrier washing, drying facilities and associated utilities.
Major ammonia-urea complex
In September, Sabic Agri-Nutrients awarded South Korea’s Samsung E&A a $3.465bn EPC contract for its seventh production complex in Jubail Industrial City (San VII).
The project will have an annual capacity of approximately 1.2 million metric tonnes of conventional ammonia and 2.6 million tonnes of urea, integrated with a post-combustion carbon-capture unit.
The Ministry of Energy approved feedstock allocation for the project in March. San VII will expand the company’s total urea capacity by 54%, from approximately 4.8 million t/y to 7.4 million t/y.
The development reflects a shift in project scope. Originally conceived as San VI – a low-carbon facility designed to yield 1.2 million t/y of blue ammonia alongside specialised nutrients – the scheme was re-engineered as a conventional ammonia and urea plant using carbon-capture systems to manage emissions intensity.
Construction is scheduled to begin in the fourth quarter of 2026. Commissioning is slated for the third quarter of 2030, with full commercial operation targeted before year-end 2030.
Sabic Agri-Nutrients positions the project as central to its 2040 strategy to expand export market share and support international supply chains.
Greenfield methanol plant
San VII is not the only major project moving forward.
Also in September, Sabic subsidiary Saudi Methanol Company (Ar-Razi) secured feedstock approval from the Ministry of Energy to build a 1.8 million t/y greenfield methanol plant in Jubail.
The project aligns with Sabic’s focus on scale in core petrochemical chains and provides intermediate feedstock for expanding domestic downstream manufacturing.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21015944/main2510.jpg -
Saudi Arabia’s NWC awards package 12 of sewage scheme
30 October 2026

Register for MEED’s 14-day trial access
Local contractor Al-Yamama has won the contract for package 12 of Saudi Arabia’s long-term operations and maintenance (LTOM) sewage treatment programme, sources close to the project have confirmed to MEED.
It is understood that the contractor offered a levelised tariff of SR0.98 a cubic metre for the project.
The state-owned National Water Company (NWC) is delivering the sewage treatment plant rehabilitation programme in two phases, including up to 19 packages.
Known as the North Western B Cluster, LTOM12 was tendered last year, and bids were submitted in November 2025.
Under the original scope, the contract covers the construction and upgrade of seven sewage treatment plants with a combined capacity of about 162,000 cubic metres a day (cm/d).
In February, MEED exclusively reported that five bidders were awaiting a decision on the award.
These included:
- Alkhorayef Water & Power Technologies (Saudi Arabia)
- Civil Works Company (Saudi Arabia)
- Miahona (Saudi Arabia)
- Beijing Enterprises Water Group – BEWG (Hong Kong)
- Al-Yamama (Saudi Arabia)
According to a source, NWC opened financial bids for the tender in April.
The contract represents Al-Yamama’s first award under the LTOM programme. However, the contractor has previously worked with NWC on several water infrastructure projects and is continuing construction works on a treatment plant expansion project in Al-Khobar in the Eastern Province.
Packages 10 and 11
On 2 September, NWC announced the formal signing of a $347m contract with a Saudi-Chinese consortium for Northern Cluster Sewage Treatment Plants Package 10 (LTOM10).
LTOM10 was the first contract awarded under the second phase of NWC’s sewage treatment plant rehabilitation programme.
The 15-year contract was signed with a tariff of SR0.69 ($0.18) a cubic metre.
MEED exclusively reported in January that the consortium had won the contract, which has a combined treatment design capacity of more than 337,000 cm/d and covers plants across the Hail, Qassim, Al-Jouf and Northern Borders provinces.
The same consortium led by United Water (China) is also expected to formally sign a contract for LTOM11 in the coming months.
NWC previously awarded $2.7bn-worth of contracts for the first phase of its LTOM programme. This comprises nine packages covering the treatment of 4.6 million cm/d of sewage water for the next 15 years.
Under tender
Two remaining packages in the LTOM programme are currently out for tender. As previously reported by MEED, bidders are preparing to submit offers for package 14, covering the upgrade of six existing sewage treatment plants (STPs), including a capacity expansion of 30,000 cm/d at the Al-Jarodia STP.
Known as the Eastern A Cluster (LTOM14), the project will increase total treatment capacity from about 263,000 cm/d to approximately 293,000 cm/d, with an estimated cost of $180m. NWC tendered the package in April, and the latest bid submission deadline is 30 November.
In the longer term, bids for package 16 of the LTOM programme are due by 3 May 2027. NWC tendered the contract earlier this month, as MEED reported exclusively.
Under the original scope, the project is expected to cover the rehabilitation and upgrade of 14 STPs with a total design capacity of 153,000 cm/d.
According to a source, bidders must first submit a letter of intent by 22 February 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21010688/main.jpg -
H&H continues to deliver Dubai projects
29 October 2026
Dubai-based developer H&H has launched Water Gardens, a mixed-use development in Dubai International Financial Centre (DIFC), and expects to award most of the construction contracts for its wider pipeline before summer 2027.
Water Gardens comprises four buildings designed by UK architect David Chipperfield, arranged around a central garden and pedestrian-friendly public realm. The scheme combines offices, residences, hospitality and retail offerings, including the Four Seasons Private Residences Dubai at DIFC and residences under H&H’s Eden House brand.
 Construction is under way, and the developer says the project is scheduled for completion in 2028. DIFC Investments describes it as one of the final components of the original Gate District masterplan.
Speaking to MEED at the launch, H&H chairman Shahab Lutfi said the office building and Eden House are due for completion in about 18 months. The Four Seasons residences are scheduled for delivery at the end of 2028, with a five-star hotel following later.
Water Gardens is one of several projects H&H has under way. The company undertakes a selective portfolio of high-end real estate developments in prime locations in Dubai. These include the Carlyle Residences in DIFC; an Eden Hills villa community in Mohammed Bin Rashid City; and Dubai Peninsula, a waterfront scheme in the Jumeirah area that will include hotels operated by Aman and Rosewood.
“We are awarding day in, day out,” says Lutfi. “I think we are awarding most of our contracts from now until summer next year.”
Most of the company’s construction volume is in DIFC and Dubai Peninsula, with the Eden Hills villas accounting for a smaller share. Lutfi says H&H is talking to several of the emirate’s biggest contractors about upcoming packages.
We are awarding [contracts] day in, day out
Staged procurement
H&H is managing cost pressures by splitting up its procurement. It awards main contracts covering concrete works with a large number of provisional sums, then tenders further packages as designs are completed. “We are taking on some of the risk, but we know how to manage the risk instead of just offloading it on the contract,” says Lutfi.
He does not expect construction costs to fall in the next 12 months. Global inflation, driven by fuel prices and logistics costs, is already factored into the company’s plans.
“Waiting and trying to award at a cheaper price is not an option for us,” he says.
Lutfi says rising costs need not erode margins for developers that keep unsold stock to sell at higher prices later in a project. Developers that sell out early are more exposed. “If you have already sold out two years ago, you are hurting your profitability,” he says.
H&H is comfortable leaving 15%-20% of a project to sell on completion. The market usually expects developers to sell out before handover.
The company has not revised its masterplans or product mix in response to market conditions and continues to focus on large units.
Supply chains have been a challenge this year, but Lutfi says the company is over that hurdle. H&H has sourced more materials locally and planned logistics further in advance.
Materials are reaching Dubai through bonded routes from Oman, Fujairah and Khor Fakkan in the UAE, and Jeddah in Saudi Arabia.
“It takes a little bit longer, but at least things are coming in,” he says.
H&H relies on a relatively small group of contractors that work on most of its projects, and treats them as long-term partners.
Lutfi says contractors are attracted by the company’s financial stability and volume of work. “That can keep some people busy for the next five or six years,” he says.
Lutfi notes that sales in the Dubai market have dropped, although enquiries have picked up since the summer as buyers weigh whether it is the right time to purchase. The distressed sales that some had expected have not materialised.
“A 5% discount in some units is not really a distress sale,” he says. “It is just someone trying to get a discount because of the region’s situation, which actually builds confidence.”
For Water Gardens, H&H has sold 85% of Four Seasons Private Residences Dubai at DIFC since sales began in 2024. The company launched sales at the Carlyle Residences before the regional disruption and has since sold units one-to-one to selected clients. More Four Seasons units have been sold in the past two weeks.
“Branding makes a big difference,” says Lutfi.
The company markets its branded residences through a global network of brokers rather than via public campaigns or launch events. Eden Hills, which is aimed mainly at Dubai residents, is marketed more widely.
Lutfi expects buyers to be more cautious about buying off-plan. H&H is building new sales centres at Dubai Peninsula and in DIFC so that clients can see the product before they commit.
“People have to come in, know exactly what they are buying, and they will feel comfortable paying the price – instead of just having a pretty brochure,” he says.
He expects demand for villas to become more local and regional, while branded residences will continue to attract international buyers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21012636/main.gif -
Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
Expo 2030 Riyadh Company (ERC), responsible for delivering the Expo 2030 Riyadh venue, has allowed contractors until 11 November to submit bids for a contract to deliver the Souq areas within the Expo site.
The tender was floated on 30 July, with an initial submission deadline of 9 October.
The Souq areas are divided into five distinct precincts, with a total development area of about 300,000 square metres (sq m).
The scope includes the five precincts and their associated vertical elements, infrastructure and public realm works.
The precincts comprise:
- Precinct 1 – The Icon: 41,417 sq m
- Precinct 2 – Place & Planet: 62,306 sq m
- Precinct 3 – Culture of Wisdom: 67,112 sq m
- Precinct 4 – Kingdom of Saudi Arabia: 45,967 sq m
- Precinct 5 – Adaptation & Innovation: 82,358 sq m
The package will interface with three public parks. It will also tie into the Natural Corridor, including bridges.
The Souq areas will form a mixed-use destination at the centre of Expo 2030 Riyadh, connecting the site’s iconic and thematic assets.
The development will include rented and partnership pavilions, alongside a range of food and beverage, retail and visitor-experience offerings.
Site progress
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to build a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts to local firm Al-Yamama Company for the next phase of infrastructure works at the site.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, and electric vehicle charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20998514/main.jpg