Saudi Arabia reinvigorates power sector
7 March 2023

Recent developments indicate that Saudi Arabia is more determined than ever to continue pursuing a multi-pronged energy diversification approach.
Between December 2022 and early March, the kingdom received bids for the contract to build its first nuclear power plant project; issued the tender for the development of 7,200MW of combined-cycle gas turbine (CCGT) independent power producer (IPP) schemes; and appointed a consultant to assess three solar parks with a potential capacity of 30GW.
The rush of new projects contrasts with the sector’s lacklustre performance in 2016-21, when the cumulative value of contracts awarded totalled a mere $5.5bn, reaching a record low of $55m in 2017.
The new-found momentum began last year, with $8.1bn-worth of contracts awarded, the highest over the 10-year period starting in 2013.
Last year’s contract awards include the estimated $4bn contract for the renewable energy and battery storage facility catering to the Neom green hydrogen project. Contracts for the 1.2GW third round of the kingdom’s National Renewable Energy Programme (NREP) and the Public Investment Fund's (PIF) 2.06GW Shuaibah 2 solar photovoltaic (PV) project were also awarded.
This has taken the overall capacity of solar projects under construction in Saudi Arabia to roughly 6,230MW, excluding the captive facility catering to the Neom green hydrogen project – a remarkable feat given that the kingdom has significantly lagged behind its renewable energy targets.
As of last year, the kingdom only has an estimated 842MW of renewable energy installed capacity, mainly from the 300MW Sakaka solar PV facility and 400MW Dumat al-Jandal wind farm.
This equates to just 3 per cent of its initial national goal to install 27.3GW of renewable energy capacity by 2024 and 1.4 per cent of its 2030 goal of 58.7GW.
The impact of the Covid-19 pandemic and war in Ukraine has affected the delivery of most of the projects, according to a Saudi-based expert, due to disrupted supply chains and global inflation.
“The Covid-19 pandemic affected projects not just in Saudi Arabia, but everywhere in the world,” he says.
Other experts insist that the kingdom needs to make an unprecedented adjustment to meet its ambitious 2030 target.
In response, state offtaker Saudi Power Procurement Company (SPPC) launched the procurement process last year for NREP’s fourth round.
Phase four comprises two solar PV IPP schemes with a total combined capacity of 1.5GW and three wind IPPs with a total combined capacity of 1.8GW. Bids for these contracts are due by April and May this year, respectively.
In early March, Germany-based ILF Consulting Engineers (ICE) also announced that it had been selected to undertake the pre-development studies for three solar PV parks in Saudi Arabia with a potential combined capacity of 30GW, the largest of its kind ever planned in the region, if not globally.
The locations and procurement timeline for the projects have not yet been announced, but the tendering process will most likely commence once the initial studies are complete, according to a source familiar with the projects.
Going nuclear
Saudi Arabia’s Finance Ministry’s disclosure that it received bids in late December last year for the contract to build the kingdom’s first nuclear power plant has also significantly raised the power generation sector’s momentum.
The entire project’s budget of roughly $33.5bn, as estimated by MEED Projects, accounts for over a third of the total value of planned and unawarded power generation projects across the kingdom.
The potential award of the nuclear power project – the initial phase of which is understood to be 2.8GW – is not expected to slow down the pace of contract awards for other power generation assets.
As previously stated, the kingdom’s energy diversification programme expects clean and renewable energy to account for half – up from roughly 1 per cent today – of its electricity production mix by 2030.
The long lead time to construct and develop a nuclear power plant could also mean the first reactor is not likely to be ready by the end of the decade.
While the kingdom has not disclosed the list of companies bidding for the project, there is mounting speculation that at least three companies, including Russia’s Rosatom, China National Nuclear Corporation and South Korea’s Kepco, may have submitted a proposal to develop the facility.
RELATED READ: Saudi nuclear move has geopolitical significance
Unlike the solar and wind energy projects, the results of the nuclear energy bids are expected to be announced only by the highest level of leadership within the kingdom due to the strategic and geopolitical importance of nuclear power.
Ramping up gas
In January, SPPC retendered contracts to develop its next gas-fired IPP projects. Initially comprising two projects, each with a capacity of 3.6GW, the Taiba and Al-Qassim IPPs were each split into two 1.8GW schemes, with bids for the four contracts due by mid-2023.
These are the first gas-fired power generation plants to be procured since 2016, when Saudi Arabia awarded the 1,500MW Fadhili IPP to a consortium led by France’s Engie.
Before the retender, SPPC received only a single bid for the 3.6GW Taiba IPP. Wary of net-zero carbon emission targets, many international utility developers declined to bid for the package citing insufficient decarbonisation provisions.
Despite this setback, SPPC sought consultants last year for the transaction advisory contract for its next round of CCGT projects, which will be developed using a build-own-operate model.
The two projects, to be located in Riyadh and Al-Khafji, will each have a design capacity of 3,600MW.
“It is a moving target,” a senior official with a utility developer said about the kingdom’s energy diversification goal.
Various official sources suggest that the country’s current installed power generation capacity stands at 80-90GW, with little to no publicly available figures in terms of the capacity forecast by 2030.
The original target to install 57.8GW of renewable energy capacity by the end of the decade vis-à-vis a goal for renewable energy to account for 50 per cent of the total implies that the 2030 figure could be around 110-120GW.
Keeping this in mind, and the need to retire ageing fossil fuel-fired fleets during the intervening period, appears to justify the need for the kingdom to build more gas-fired power plants while pursuing significant renewable and nuclear capacity.
In terms of attracting more bidders for its current and future CCGT schemes, much will depend on how SPPC and the Energy Ministry address developers’ concerns regarding measures to minimise carbon footprint at the same time as ensuring the assets’ long-term economic feasibility.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors submit best offers for Oxagon Highway 55
19 November 2026
-
 Construction starts on Damascus hotel and mall
19 November 2026
-
 Kuwait discusses retender of $7.7bn of oil projects
19 November 2026
-
 Saudi Arabia cancels more water tenders
19 November 2026
-
 Contractors submit bids for Neom wastewater plant
18 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Contractors submit best offers for Oxagon Highway 55
19 November 2026
Contractors have submitted their best and final offers for a design-and-build contract to upgrade Highway 55 in Saudi Arabia’s Oxagon region.
The first phase of the project includes the construction of 14 kilometres of road, with two lanes in each direction, as well as one bridge and three interchanges.
The project is expected to take 22 months to complete.
Contractors initially submitted bids on 28 September, as MEED exclusively reported.
Highway 55 connects the Red Sea coast with the mainland in northwestern Saudi Arabia. It is currently the only road providing north-south connectivity between Duba and the Neom region.
MEED reported exclusively in August last year that contractors had submitted responses to an expression of interest notice that Neom had issued earlier that month.
The project is expected to support cargo movement from Duba Port to other parts of the kingdom and the wider region.
Last year, Neom tested a pilot initiative by handling a shipment that travelled from Cairo via the Port of Safaga, across the Red Sea to the Port of Neom, and then inland to Erbil, Iraq.
In a statement, Neom said: “The shipment travelled through an intermodal corridor spanning over 900 kilometres, marking a significant milestone in the kingdom’s transformation into a regional and global logistics hub.”
 READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Gulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21556022/main.jpg -
Construction starts on Damascus hotel and mall
19 November 2026
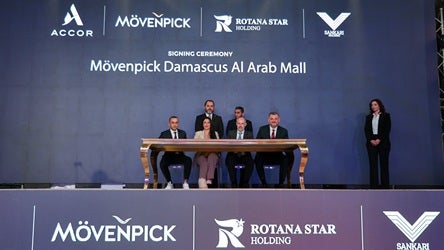
Construction has started on the Movenpick Hotel and Arab Mall development in the Kafr Sousa district of Damascus.
Rotana Star Holding and Sankari Holding are backing the project, which Syria’s Ministry of Tourism is developing under its patronage.
The project marks Accor’s entry into the Syrian market. The France-based hotel group signed an agreement earlier this year to manage the project’s Movenpick Hotel component.
The integrated development will cover more than 90,000 square metres (sq m) and combine hotel, retail, entertainment and supporting facilities.
The Movenpick Hotel will occupy more than 25,000 sq m and include 300 accommodation units. Facilities will include event and celebration halls, restaurants with panoramic views, and health and fitness amenities.
Arab Mall will cover more than 65,000 sq m across seven levels. It will include retail units, entertainment facilities and service areas.
The developers expect Arab Mall to open in the first quarter of 2028, followed by the hotel in the first quarter of 2029.
Accor acquired the Swiss-founded Movenpick brand in 2018. Under the management agreement, Accor will operate the hotel and provide access to its global reservation, distribution and marketing platforms.
The development is expected to create direct and indirect employment across construction, engineering, hospitality, retail and services.
The project is being advanced as Syria seeks to expand its tourism and hospitality capacity.
Syria’s Ministry of Tourism has reported that the country received 3.52 million visitors in the first half of 2026, 111% more than in the same period of 2025.
The ministry said foreign tourist arrivals increased by 448%, while Arab visitor numbers rose by 107%.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21555695/main.jpeg -
Kuwait discusses retender of $7.7bn of oil projects
19 November 2026
State-owned upstream operator Kuwait Oil Company (KOC) is discussing the retendering of upstream projects worth an estimated $7.7bn, according to industry sources.
The tender processes for all four contracts were cancelled earlier this year after the lowest bids exceeded the projects’ approved budgets.
The projects are:
- Separation Gathering Centre 1 (SGC-I) and Water Injection Plant (WIP-1)
Previous low bidder: Tecnicas Reunidas (Spain) – $2.47bn - Separation Gathering Centre 3 (SGC-3) and Water Injection Plant (WIP-3)
Previous low bidder: Larsen & Toubro (India) – $2.48bn - Installation of Water Injection Plant (WIP-4)
Previous low bidder: Petrofac (UK) – $1.48bn - Effluent Water Disposal Plants 1 & 2 expansion project (EWDP 1&2)
Previous low bidder: Larsen & Toubro (India) – $1.30bn
KOC is considering a strategy under which pipeline and network installation work would be removed from the main contract scopes and tendered separately, the sources said.
The company is also planning to relaunch the four main packages under a build-own-operate model rather than the engineering, procurement and construction (EPC) model used previously.
KOC is expected to tender the pipeline and network packages on an EPC basis, or under a similar delivery model.
In addition, KOC is discussing increases to the projects’ approved budgets to enable contractors to submit compliant bids, the sources said.
Since KOC cancelled the four tenders in January, Kuwait’s oil and gas sector and the wider economy have faced disruption linked to the regional conflict that began after the US and Israel attacked Iran on 28 February.
The conflict has reduced shipping through the Strait of Hormuz, limiting Kuwait’s ability to export crude oil.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21532374/main.jpg - Separation Gathering Centre 1 (SGC-I) and Water Injection Plant (WIP-1)
-
Saudi Arabia cancels more water tenders
19 November 2026
Two tenders for a major water pipeline project in Saudi Arabia have been cancelled, marking the second major water infrastructure project in the kingdom to have its tender process called off this month.
The tenders cover Package B and the combined Packages C1 and C3 of the New Water Pipeline to Feed Riyadh City 2 project, being developed by Water Transmission Company (WTCO).
A source close to the project told MEED that bidders were notified of the decision earlier in November.
The three packages have a combined value of about $556m and involve the construction of a long-distance potable-water transmission system to strengthen supplies to Riyadh.
The wider masterplan includes approximately 136 kilometres of pipeline, with diameters ranging from 64 inches to 100 inches. The scope also includes 10 steel storage tanks with capacities ranging from 100,000 cubic metres to 170,000 cubic metres.
According to regional tracker MEED Projects, Saudi Services for Electro-Mechanic Works was appointed as the main contractor for Package B in 2025, with a reported contract value of $279.6m. Another local firm, Al-Rawaf Trading & Contracting, was appointed for Packages C1 and C3, with a combined contract value of $276m. Multiple other contractors submitted bids for the three packages.
As MEED understands, construction was expected to start earlier this year.
The cancellations follow the withdrawal of a tender for a 300-million-litres-a-day seawater reverse osmosis desalination plant at Yanbu, valued at $272m.
As reported by MEED on 16 November, Saudi Water Authority cancelled the Yanbu tender despite India’s VA Tech Wabag receiving the contract award in July 2025.
The contractor disclosed the decision in a filing to Indian stock exchanges, saying the tender was cancelled due to “internal reasons” on the authority’s side.
It is the second time a tender has been cancelled for the project at the final award stage.
It is unclear whether the desalination or transmission-pipeline projects will be retendered and, if so, whether their scopes will remain unchanged. MEED has contacted WTCO for comment.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21527730/main.jpg -
Contractors submit bids for Neom wastewater plant
18 November 2026
Register for MEED’s 14-day trial access
At least five contractors or contractor consortiums have submitted bids for a contract to build a wastewater treatment plant for Oxagon, Neom’s industrial cluster.
According to a source, bids were submitted on 9 November.
The industrial wastewater treatment package will have an initial capacity of 35,000 cubic metres a day (cm/d) and is being procured by Enowa, Neom’s energy and water utility. The project is estimated to cost up to $165m.
Enowa issued the request for proposals earlier this year, with an initial October deadline, as exclusively reported by MEED.
The bidders and bidding consortiums include:
- Alfanar (Saudi Arabia) / Lanke (China)
- Alkhorayef (Saudi Arabia)
- Orascom (Egypt) / Wabag (India)
- Safari (Saudi Arabia) / Veolia (France)
- Wetico (Saudi Arabia) / Satco (Saudi Arabia)
UAE-based Tecton Engineering and India’s Ion Exchange had also previously expressed interest in bidding for the contract.
The wastewater treatment capacity will be supplied in modular trains of 5,000 cm/d each. A separate sanitary wastewater treatment package will have a capacity of 1,000 cm/d.
The contract is structured as a design-build-operate project and covers the supply, installation and commissioning of industrial and sanitary wastewater treatment packages, as well as three years of operation and maintenance.
The procurement appears to take a reworked approach to wastewater treatment at Oxagon Industrial Quarter, with the modular and demountable facility designed to provide “interim wastewater treatment” capacity.
This includes treatment systems that can be installed and later removed or relocated as Oxagon’s requirements evolve. The plant can be expanded to a maximum capacity of 45,000 cm/d.
Some of the same contractors are also expected to submit qualification documents to Neom Green Hydrogen Company (NGHC) for a smaller interim wastewater treatment plant and disposal system at Oxagon Industrial Quarter.
NGHC recently issued a request for qualification for an engineering, procurement and construction contract, with a bid submission deadline of 22 November.
The planned facility is designed to handle a combined wastewater flow of 14,530 cm/d from cooling water blowdown and industrial wastewater.
Other major developments in the industrial cluster include the $8.5bn Neom Green Hydrogen project, which completed construction in August and is targeting commercial operations in 2027, and a planned artificial intelligence data centre campus being developed by Humain and DataVolt.
READ THE NOVEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFGulf projects keep moving amid conflict; UAE's state spending and oil output flexibility cushion Iran war shock; Project finance lenders weigh risk against infrastructure needs.
Distributed to senior decision-makers in the region and around the world, the November 2026 edition of MEED Business Review includes:
> AGENDA: GCC projects market holds its nerve> MARKET FOCUS: UAE economy shows resilience> INDUSTRY REPORT: Project financiers hold the line> STADIUMS: Stadium spending set to jump 39% in 2027> CONFLICT: Hormuz closure wipes out growth in 2026> INTERVIEW: WSP regional president Dean McGrail> INTERVIEW: Ministry of Energy & InfrastructureTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21525188/main.jpg