Riyadh to sustain power spending
12 March 2024
 Latest news on Saudi Arabia’s power sector:
> Neom to start qualification for $2.7bn hydropower scheme
> Saudi power buyer holds Remah and Nairiyah meetings
> Enowa gives extra day for Gayal and Shiqri bidders
> Gayal and Shiqri bidders race to meet deadlines
> Neom extends Duba Energy Park bid deadline
> Data centre activity soars in Saudi Arabia
> US firm wins Al Kahfah solar tracker package
> Saudi-Omani team to set up transformers plant

The project pipeline in Saudi Arabia’s power generation sector continues to expand unabated.
The value of projects in execution or about to start construction has increased by 17% to $34bn compared to six months earlier, according to the latest available data from regional projects tracker MEED Projects.
The value of projects in the pre-execution phase similarly increased by 16% to reach $51bn during the same period. New schemes are expected to be announced in the coming 12-18 months, including power generation projects catering to the $500bn Neom development.
Two key factors underpin the ramp-up of both conventional and renewable energy generation capacity in the kingdom, notes a Dubai-based senior executive with an international developer.
“Saudi Arabia intends to become the renewable supplier of choice on the GCC grid,” the executive said, referring to the regional network linking the electricity grids of Bahrain, Kuwait, Oman, Qatar, the UAE and Saudi Arabia.
The second factor is the kingdom's push for industrialisation and urbanisation, including the adoption of electric vehicles and data centres.
“Saudi Arabia has very strong regulations to keep data within its domicile and the digitalisation needed to achieve the kingdom’s modernisation plans needs large data centres and corresponding electricity supply,” she notes.
Overall, Saudi Arabia awarded power generation contracts worth more than $16.1bn in 2023, which is higher than the total value of contracts awarded in the preceding eight years and nearly six times the value of contracts awarded in 2022.
The kingdom’s principal buyer, Saudi Power Procurement Company (SPPC) and its sovereign wealth vehicle, the Public Investment Fund (PIF), awarded the bulk of these contracts.
Shrinking renewables share
The share of renewable energy in the total value of awarded contracts shrunk to 28%, from about 82% in 2022, due to the award last year of the first gas-fired independent power producer (IPP) projects since 2016.
SPPC awarded a consortium comprising Saudi Electricity Company and Saudi utility developer Acwa Power the $3.9bn contract to develop and operate the Qassim 1 and Taiba 1 IPP projects in November 2023. Each combined-cycle gas turbine (CCGT) plant has a capacity of 1,800MW.
A team comprising the local Al Jomaih Energy & Water, France’s EDF and the local Buhur for Investment won the contract to develop the other pair of CCGT-based plants – the Taiba 2 IPP and Qassim 2 IPP schemes, each of which has a capacity of 1,800MW.
SPPC also awarded the contracts for the solar photovoltaic (PV) schemes under the fourth procurement round of the kingdom’s National Renewable Energy Programme (NREP).
A consortium that includes France's EDF Renewables, Abu Dhabi Future Energy Company (Masdar) and the local company Nesma won the contract to develop the 1,100MW Hinakiyah solar IPP project. A consortium led by China's Jinko Power won the contract to develop and maintain the 400MW Tubarjal solar IPP scheme.
The PIF, meanwhile, awarded contracts last year for the development of three solar PV schemes with a total combined capacity of 4.5GW to Acwa Power and its partner Water & Electricity Holding Company (Badeel). The 2GW Al Rass 2, 1.1GW Saad 2 and 1.4GW Al Kahfah solar PV IPPs require a total investment of about $3.4bn.
Unawarded projects
Following the award of these contracts, SPPC started the procurement process for four solar PV schemes with a total combined capacity of 3.7GW under the NREP fifth round, and four new CCGT schemes with a total combined capacity of 7.2GW.
Bids are due on 10 June for the 2GW Al Sadawi, 1GW Al Mas, 400MW Hinakiyah 2 and 300MW Rabigh 2 solar PV IPP schemes.
Bids are also due in late June for the Remah 1 and 2 and Al Nairiyah 1 and 2 gas-fired CCGTs.
As of early March, Neom’s utility subsidiary, Enowa, had received bids for two renewable energy engineering, procurement and construction (EPC) contracts, the 1.2GW Gayal wind farm and 800MW Shiqri solar farm.
Enowa is understood to be preparing a site for two CCGT plants to be built on a fast-track basis at Duba Energy Park. The first phase comprises a transportable gas turbine generator (GTG) with a capacity of 300MW, which is designed to deliver emergency power to Neom.
The second phase is a permanently installed 500MW facility comprising heavy-duty GTGs. Both are considered fast-track projects, with the first phase due for completion in early 2024 and the second phase in early 2025.
The first phase of a multi-gigawatt programme to build renewable energy capacity in Neom using a public-private partnership model is also expected to start soon.
Soaring costs
The raft of new projects coming to the pipeline is exerting pressure, particularly for the CCGT supply chain, experts tell MEED. “On average, the EPC prices have more than doubled since before the Covid-19 pandemic began,” says an executive working for an original equipment manufacturer (OEM).
The average EPC cost per kilowatt for CCGT plants with a capacity of over 1.5GW is understood to have reached approximately $750 a kilowatt in 2023, which is more than twice the average cost in 2019. EPC costs for smaller plants have similarly posted significant increases.
Industry sources say the turbine supply chain problem arises from the decision by some OEMs to reduce capacity over the past few years, driven by a combination of the Covid-19 pandemic and the threat of curtailed demand due to the push to decarbonise electricity systems.
The post-Covid-19 recovery, as well as the resurgence of demand for gas-fired power plants in the Middle East – and even in some countries in Europe – along with the expressed preference by most GCC clients for European-made gas turbines, has resulted in a seller’s market.
A Dubai-based OEM executive told MEED last year that its EU-made turbines are booked for several years, but order deliveries can still be shuffled between customers, so they do not expect major delays in delivering to clients. "It's definitely a seller's market right now for turbines. We have capacity in other regions like China, but customers prefer [turbines made in] EU factories”.
In comparison, the jury is still out on solar PV costs, although historical tariff data indicates a general upward trend between the record-low tariffs seen in 2021 and those submitted last year.
Transmission and distribution
Transmission and distribution (T&D) contracts exceeding a total of $12bn are under execution in Saudi Arabia, with an estimated $22.4bn in the pre-execution phase.
The value of contracts awarded in 2023, which sits at $4bn, exceeded the previous year’s total by 41%. The contract to build a high-voltage, direct current transmission system between Neom’s Oxagon industrial cluster and Yanbu is the largest T&D contract to have been awarded last year.
Volume-wise, 59 T&D contracts were awarded in Saudi Arabia last year compared to 64 in 2022.
Saudi Arabia has been gradually expanding the reach of its grid, both domestically – due to the development of new communities and industries and the growth of renewable energy capacity – as well as internationally.
Projects to link with Egypt and other countries in the GCC, as well as with Iraq and Jordan, are under way, while preliminary studies are ongoing to link the kingdom’s power grid further afield, including to the grids of India and Greece.
Energy storage and nuclear
A new project activity segment within Saudi Arabia’s power sector is emerging. SPPC intends to start the procurement process this year for the 2GW first phase of a project to procure 10GW of battery energy storage system (bess) capacity by 2030.
Bess comprises rechargeable batteries that can store and discharge energy from various sources when needed.
Saudi Arabia plans to locate its bess facilities near demand centres to boost the electricity grid's spinning reserves as more renewable energy is expected to enter its electricity production mix.
The 2GW first phase of the project entails building several plants at different locations, with individual capacities ranging from 50MW to 300MW each.
Finally, the procurement process is moving – albeit slowly – on the Duwaiheen nuclear power plant, Saudi Arabia’s first large-scale nuclear power project. Bids for the main contract are due in late April, following several deadline extensions since the kingdom invited selected companies to bid for the contract in 2022.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Morocco plans second high-speed rail phase to Agadir
26 October 2026
-
 Riyadh tenders King Salman Stadium works
26 October 2026
-
 Aramco selects contractors for five offshore tenders
23 October 2026
-
 Contractors complete Riyadh airport Terminal 6 work
23 October 2026
-
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Morocco plans second high-speed rail phase to Agadir
26 October 2026
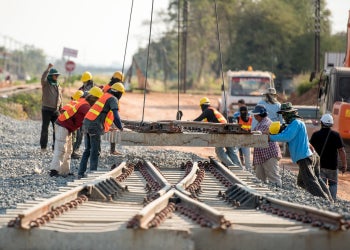
Morocco has outlined a second rail investment cycle for 2030-35, which includes beginning construction of a high-speed rail extension from Marrakech to Agadir and connecting Essaouira to the national rail network.
The pipeline forms part of the government’s 2026-31 programme, presented to parliament last week.
The Marrakech-Agadir link is estimated to cost close to MD55bn ($5.5bn) and will cover a 240-kilometre (km) route through the High Atlas Mountains via Chichaoua. Civil engineering structures, including tunnels and viaducts, are expected to account for nearly 70% of the alignment.
In September, the government issued a decree declaring the Marrakech-Agadir and Chichaoua-Essaouira rail corridors to be of public utility, paving the way for land acquisition and expropriation procedures.
Under the long-term masterplan Plan Rail Maroc 2040, Essaouira is expected to connect to the network via a separate line branching off at Chichaoua, designed for operating speeds of up to 200km an hour. The mainline to Agadir is designed for speeds of up to 320km/h.
The 2030-35 cycle also includes rehabilitating the Casablanca-Khouribga-Oued Zem line; constructing a new line between Oued Zem and Beni Mellal via Bejaad, with a branch to Fquih Ben Salah; doubling and upgrading the 140km Benguerir-Safi line; expanding capacity on the Fez-Oujda corridor; and building new-generation passenger stations.
The plans follow Morocco’s ongoing MD134bn ($13.4bn) 2024-30 rail investment programme, which focuses on completing the Kenitra-Marrakech high-speed line ahead of the 2030 Fifa World Cup.
The programme also includes developing regional express network services across five regions, electrifying the Fez-Oujda line and completing a freight rail link to the Nador West Med port.
Work on the Kenitra-Marrakech line had reached about 30% by May 2026, with commercial services targeted to begin in September 2029.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20920349/main.jpg -
Riyadh tenders King Salman Stadium works
26 October 2026
Register for MEED’s 14-day trial access
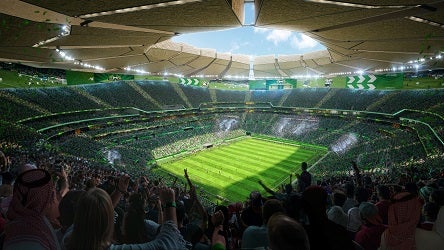
Saudi Arabia’s Sports Ministry has tendered a contract covering early works at King Salman International Stadium in Riyadh.
The scope includes enabling works, site preparation and initial construction activities.
The tender was issued on 11 October, with a submission deadline of 19 November.
The stadium will cover about 660,000 square metres (sq m) and seat 92,000. Facilities will include a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The wider development will include sports facilities covering more than 360,000 sq m, including two training fields and fan zones; a closed sports hall; an Olympic-sized swimming pool; an athletics track; and outdoor courts for volleyball, basketball and padel.
The stadium is set to host the final of the 2034 Fifa World Cup and will serve as the Saudi national football team’s main base.
US-based architectural firm Populous is the lead architect for the stadium.
Construction of the stadium is expected to be completed by 2029.
The stadium will be located next to King Abdulaziz Park.
Firms submitted prequalification statements for the main design-and-build contract in February.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia planned to build 11 new stadiums and refurbish four facilities for the 2034 Fifa World Cup.
Eight stadiums will be located in Riyadh, four in Jeddah and one each in Al-Khobar, Abha and Neom.
A further 10 cities will host training bases: Al-Baha, Jazan, Taif, Medina, Alula, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah.
There are expected to be 134 training sites in the kingdom, including 61 existing facilities and 73 new venues.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of Fifa member associations at the Fifa Congress on 11 December 2024.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20919233/main.jpg -
Aramco selects contractors for five offshore tenders
23 October 2026
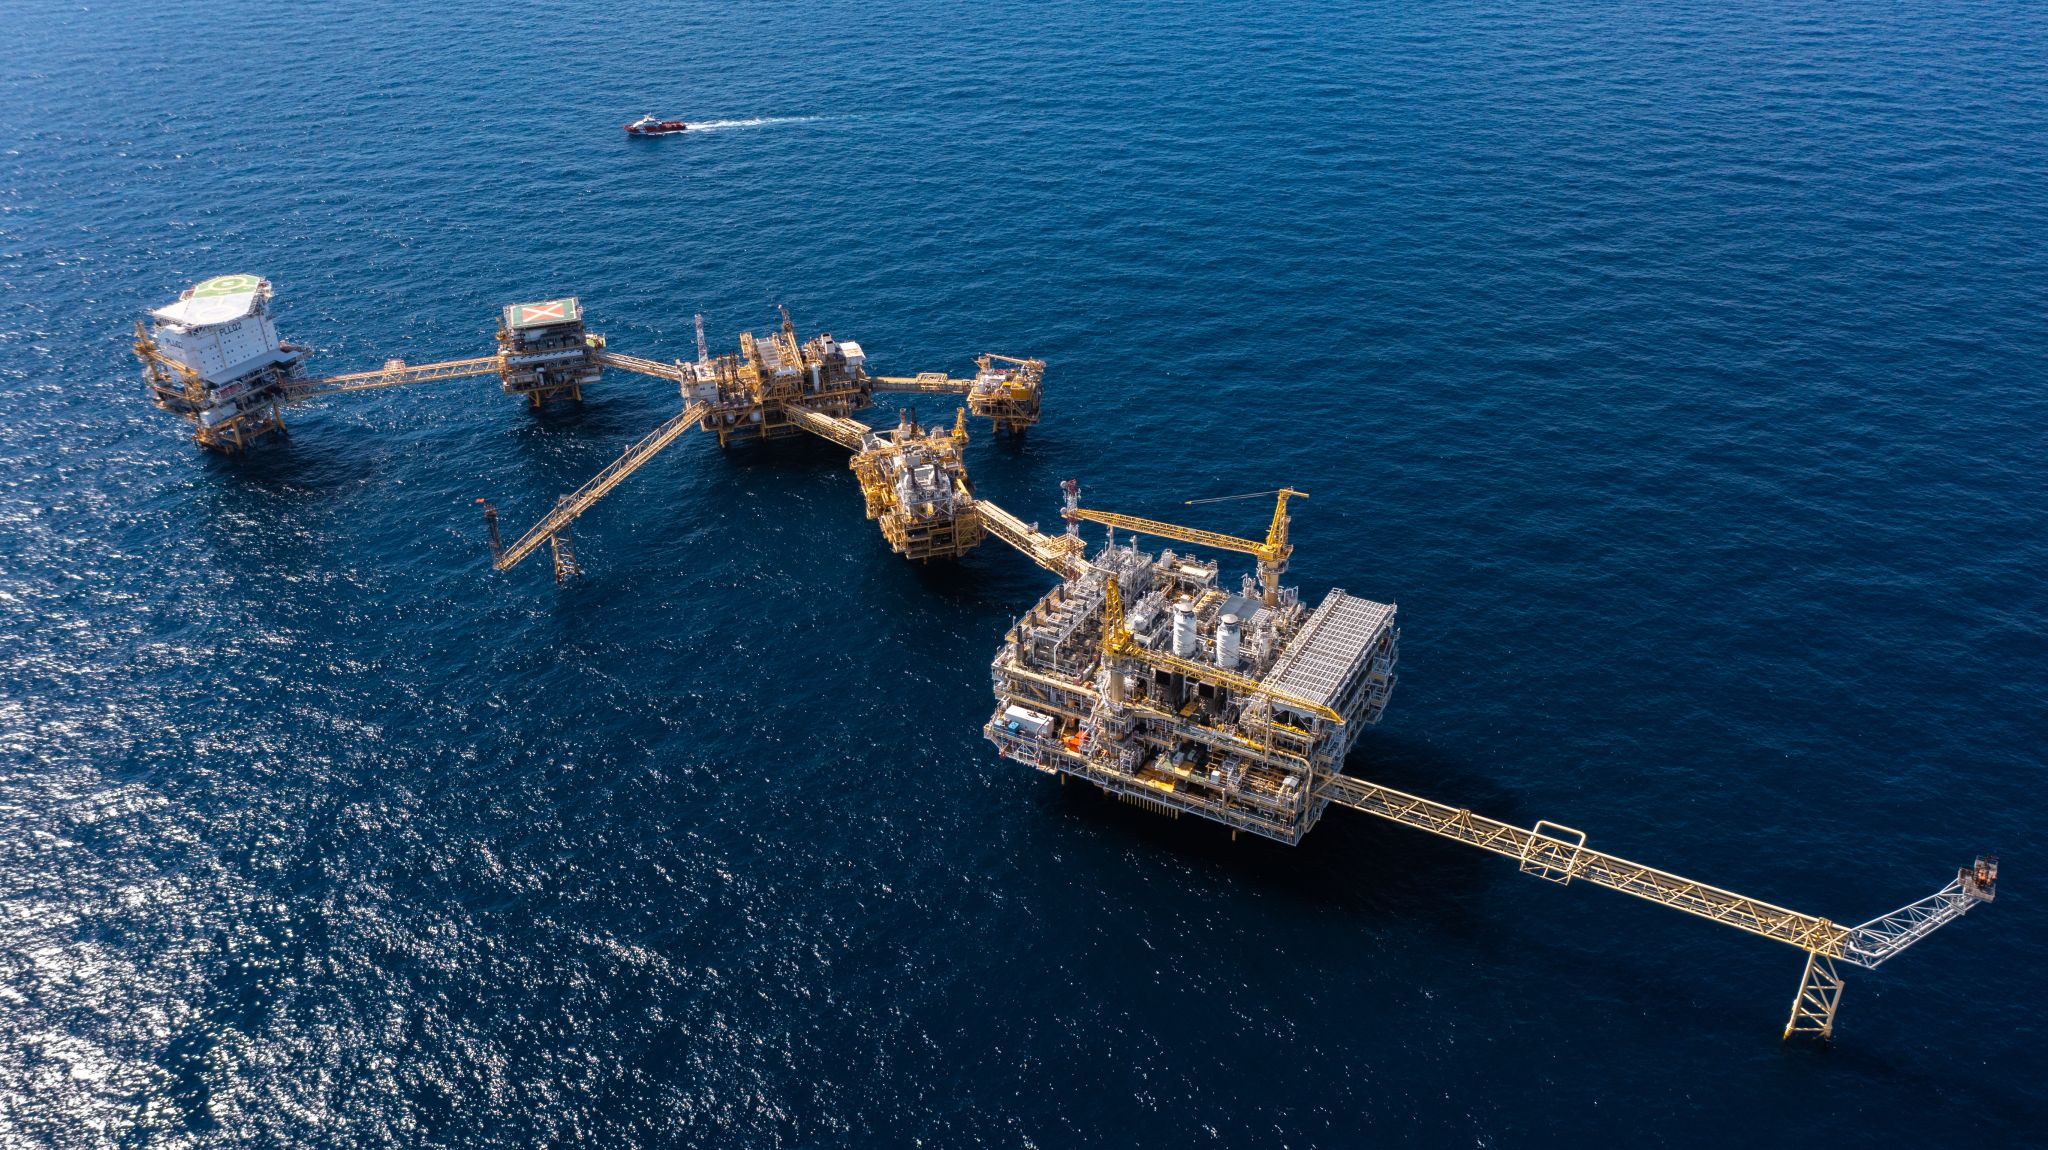
Saudi Aramco has selected contractors for five offshore tenders covering the engineering, procurement, construction and installation (EPCI) of structures at the Abu Safah, Berri, Manifa, Marjan, Safaniya and Zuluf offshore oil and gas fields in Saudi Arabia.
The tenders are numbers 167, 168, 169, 170 and 171 on Aramco’s Contract Release and Purchase Order (CRPO) system, and are estimated to be worth up to $2bn combined.
Abu Dhabi government-owned NMDC Energy has won CRPOs 167, 169 and 171, while Italian contractor Saipem has secured CRPOs 168 and 170, according to sources.
NMDC Energy confirmed its contract awards from Aramco in a disclosure to the Abu Dhabi Securities Exchange on 23 October, saying the three contracts are valued at AED2.8bn ($763.3m).
Work on the contracts is expected to be completed in 18-23 months, NMDC Energy said in its filing, without providing further details.
Saipem has yet to confirm its contract awards from Aramco.
The basic scope of EPCI work on the tenders is as follows:
- CRPO 167 – eight jackets at the Marjan field development
- CRPO 168 – four production deck modules (PDMs) at the Abu Safah, Berri, Manifa and Safaniya fields
- CRPO 169 – three PDMs at the Marjan field development
- CRPO 170 – three PDMs at the Marjan field development
- CRPO 171 – three PDMs at the Zuluf field development
Aramco issued the five CRPOs to contractors in its Long-Term Agreement (LTA) pool of offshore service providers in December last year, setting an initial bid submission deadline of 3 February.
The Saudi energy giant has since extended the bid submission deadline several times – to 31 March, 1 June, 1 July and then 30 July – to allow LTA contractors sufficient time to prepare proposals.
At the request of some bidders, Aramco granted a final two-day extension, with LTA contractors submitting their proposals for the five CRPOs on 1 August, MEED previously reported.
Aramco had previously indicated its intention to award contracts for CRPOs 167-171 by October, and the contract awards affirm it has adhered to this schedule.
Aramco’s LTA pool of offshore service providers comprises the following entities:
- Saipem (Italy)
- McDermott International (US)
- Larsen & Toubro Energy Hydrocarbon (LTEH, India) / Subsea7 (UK)
- NMDC Energy (UAE)
- Lamprell (UAE/Saudi Arabia)
- China Offshore Oil Engineering Company (China)
- Dynamic Industries (US)
- Sapura Energy (Malaysia)
- TechnipFMC (France) / MMHE (Malaysia)
- Hyundai Heavy Industries (South Korea)
In April 2025, Aramco renewed its LTAs with the following contractors, whose contracts had either lapsed or were close to expiry:
- Saipem
- McDermott International
- Larsen & Toubro Energy Hydrocarbon / Subsea7
- NMDC Energy
- Lamprell
- China Offshore Oil Engineering Company
ALSO READ: Aramco upstream spending gathers pace
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20869888/main3523.jpeg -
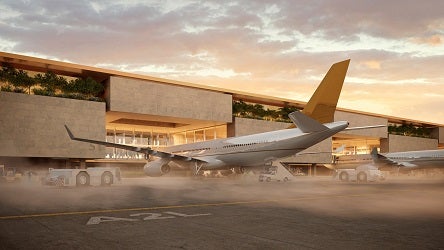
Contractors complete Riyadh airport Terminal 6 work
23 October 2026
Three contractor teams have completed the early contractor involvement (ECI) phase for Terminal 6 at King Salman International airport (KSIA) in Riyadh, moving the scheme towards a main construction tender and contract award.
The participating consortiums are:
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
King Salman International Airport Development Company (KSIADC), a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund, is delivering the terminal package on an ECI basis.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May last year, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
KSIADC's acting CEO Marco Mejia previously confirmed that the airport’s masterplan has been completed. UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20860938/main.jpg -
Aramco seeks to build sulphur-handling facilities at Ras Al-Khair
22 October 2026
Saudi Aramco is engaging developers for a planned project to build sulphur-handling facilities at Ras Al-Khair port on Saudi Arabia’s eastern coast.
Under the build-own-operate-transfer (BOOT) contract, the selected developer would be required to build facilities at Ras Al-Khair port capable of receiving, handling, forming and exporting up to 9,500 metric tonnes a day (t/d) of molten sulphur.
Additionally, the appointed contractor would be responsible for engineering, procurement and construction, as well as operations and maintenance.
According to sources, the Saudi energy giant floated the tender for the Ras Al-Khair sulphur-handling facilities project last year. Companies bidding for the BOOT contract have until 30 December to submit proposals, with the previous bid-submission deadline being on 19 September.
The following developers, among others, are understood to be bidding for the Ras Al-Khair sulphur-handling facilities project:
- Jereh Group (China)
- Lamar Holding (Saudi Arabia)
- Vision Invest (Bahrain/Saudi Arabia)
Separately, Aramco has appointed Germany-headquartered Fichtner as the consultant on the project.
The broad scope of work on the project includes development, design, financing, construction, commissioning, testing, ownership, insurance, operations and maintenance of:
- an onshore sulphur handling and processing station, comprising rail and truck sulphur unloading, molten sulphur storage and sulphur forming facilities;
- a sulphur exporting station / berth facilities located at berth number 19 at Ras Al-Khair port, comprising formed sulphur storage and a ship loader, with a rail spur system to connect to the Saudi Arabia Railway line to deliver the molten sulphur to the onshore facility, and a sulphur conveyor system to transfer the formed sulphur from the onshore facility to the berth facility;
- starting from the commercial operation date, the sale of the dependable capacity to Aramco and, to the extent dispatched by Aramco, the formed sulphur output of the plant; and
- the transfer of the shares in the project company, or alternatively the dismantling and removal of, or transfer of, the plant to Aramco.
The allocated area for the plant is 1.605 million square metres (sq m), which includes 1.5 million sq m allocated to the onshore facility and 105,000 sq m allocated to the berth facility. The project operator is required to accommodate adequate space for any potential capacity expansion.
The land for the onshore sulphur station facility is under the jurisdiction of the Royal Commission for Jubail & Yanbu, while the berth plot is under the administration and management control of the Saudi Port Authority (Mawani).
ALSO READ: Lamprell signs Ras al-Khair fabrication deal for Saudi offshore job
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20842631/main3523.jpg