Riyadh takes the diplomatic initiative
2 April 2025

Saudi Arabia has been at the centre of regional diplomatic activity through the early months of 2025, positioning itself as an intermediary in the Ukraine conflict and at the forefront of engagement with the new regime in Syria.
The role of regional mediator is one that has in recent years been more closely associated with Qatar – particularly in relation to the Gaza conflict – and, on occasion, Oman.
Riyadh’s decision to throw its weight behind diplomatic initiatives is part of what Abdulaziz Sager, chairman of the Saudi-based Gulf Research Centre, has described as a “bold multi-alignment strategy”, which seeks to balance Riyadh’s economic and security concerns and its regional leadership ambitions.
Multipronged initiatives
The kingdom has gained plaudits for its efforts to resolve the Ukraine war in particular. Following his talks with Crown Prince Mohammed Bin Salman (MBS) in Jeddah on 11 March, Ukraine’s President Volodymyr Zelenskyy said: “Saudi Arabia provides a crucial platform for diplomacy, and we appreciate this.”
Zelenskyy added that he had “a detailed discussion on the steps and conditions needed to end the war” with the crown prince.
The previous month, US secretary of state Marco Rubio had said Saudi Arabia had played an “indispensable role” in setting up bilateral negotiations between Moscow and Washington to discuss the conflict.
Russia’s President Vladamir Putin has also praised the Saudi leadership for providing a platform for high-level meetings with the US and “creating a very friendly atmosphere”.
 Whether all this leads to a lasting peace deal for Ukraine remains to be seen, but Saudi Arabia’s attitude to conflict may be coloured somewhat by its own experiences over the past decade in Yemen.
It is now 10 years since it launched a bombing campaign against Yemen’s Houthi rebels in March 2015, and the war has not gone as Riyadh had hoped, with the Houthis proving far more resilient than anticipated.
Saudi Arabia’s southern border has at least been relatively quiet since a truce took hold in 2022, but a comprehensive peace deal has proved elusive.
Riyadh has also been re-engaging in the Levant this year, in light of the new regime in Damascus.
The new Syrian president Ahmed Al-Sharaa travelled to Riyadh in early February, on his first trip abroad since taking power. Saudi Foreign Minister Prince Faisal Bin Farhan had been in Damascus a week earlier.
There are some key issues at stake for Riyadh. The regime of President Bashar Al-Assad had overseen the industrial-scale production of the amphetamine-type stimulant Captagon, much of which was smuggled into Saudi Arabia and other Gulf states. Saudi efforts to disrupt the trade – both at its borders and via lobbying of the Syrian authorities – had failed to stem the flow of drugs.
In addition, Hasan Alhasan, senior fellow for Middle East Policy at the International Institute for Strategic Studies, has pointed out that between 500,000 and 2.5 million de facto Syrian refugees are thought to be living in Saudi Arabia – a fact that gives Riyadh a clear interest in Syria’s stability, particularly if it wants to encourage them to return home.
“Saudi Arabia views the fall of the Assad regime as an opportunity to reassert its influence in the Levant,” he asserted in a recent commentary.
The ousting of Assad in late 2024 and the recent Israeli campaign against Hezbollah has also changed the situation on the ground in Lebanon, encouraging Saudi Arabia to reconsider its approach there too.
MBS hosted Lebanon’s recently elected President Joseph Aoun on 3 March. Following their meeting, Saudi Arabia said it would look again at allowing Lebanese exports to Saudi Arabia and letting its own citizens travel to Lebanon.
Manoeuvring around Trump
The Saudi diplomatic push may also be motivated by a desire to ensure that relations with Washington remain on a positive footing in the wake of Donald Trump’s re-election as US president.
At first, it appeared that the bilateral relations would follow a similar pattern to Trump’s first term.
In January, MBS said in a phone call with Trump that Saudi Arabia was planning to invest some $600bn in the US over the coming four years, which the US president suggested should probably be increased to $1tn. This echoed the signing of $460bn-worth of defence deals when Trump made Saudi Arabia his first foreign trip as president in May 2017.
Riyadh appears to have conceded to Trump’s higher figure, with the US president saying in early March: “I said I'll go if you pay $1tn to American companies, meaning the purchase over a four-year period of $1tn, and they've agreed to do that. So, I'm going to be going there.”
However, other aspects of the bilateral relationship are more difficult and less predictable. Trump had been pushing Saudi Arabia to join Bahrain, the UAE and Morocco in normalising relations with Israel, but in light of the war in Gaza and Trump’s own plans for the ethnic cleansing of Palestinians from the strip, that looks like a stretch too far.
Trump will nevertheless have been pleased by the decision by Saudi Arabia and the other members of the Opec+ bloc in early March to unwind some of the production restrictions they had voluntarily agreed.
From April onwards, the eight-strong group will start to bring 2.2 million barrels a day back onto the market over the course of 18 months. That fits in with Trump’s call in January, soon after taking office, for Riyadh and Opec to do more to help bring oil prices down.
However, that decision may also create fiscal challenges for the Saudi government, as any rise in production could be more than offset by lower prices.
Saudi Aramco has announced plans to trim its dividend payouts this year to $85.4bn – down from $124bn in 2024. These payments are a vital source of revenues both for the central government and for its Public Investment Fund (which holds a 16% stake in Aramco)
All that could force some public sector spending constraint in the kingdom, in a sign that balancing diplomacy and financial interests is not always straightforward.
MEED’s April 2025 report on Saudi Arabia includes:
> UPSTREAM: Saudi oil and gas spending to surpass 2024 level
> DOWNSTREAM: Aramco’s recalibrated chemical goals reflect realism
> POWER: Saudi power sector enters busiest year
> WATER: Saudi water contracts set another annual record
> CONSTRUCTION: Reprioritisation underpins Saudi construction
> TRANSPORT: Riyadh pushes ahead with infrastructure development
> BANKING: Saudi banks work to keep pace with credit expansion

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors prepare bids for Morocco power line
2 November 2026
-
 Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
-
 Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
-
 Egypt’s Petrojet wins gas pipeline project worth $170m
2 November 2026
-
 GCC projects market holds its nerve
1 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Contractors prepare bids for Morocco power line
2 November 2026
Contractors are preparing bids for a 160-kilometre (km), 400kV transmission line linking Guercif and Fes East in Morocco, following a site visit on 1 October.
The project is being developed by the Office National de l'Electricite et de l'Eau Potable (Onee) to connect the Saka solar photovoltaic power plant to the national electricity grid.
According to sources, at least eight contractors attended the site visit last month, including:
- Butec (Lebanon)
- CEEC Northeast Electric No.2 (China)
- Cegelec (France)
- EPME Electric (Morocco)
- Hideleco (Egypt)
- Kec International (India)
- PowerChina (China)
- Transrail (India)
The project comprises two lots. The first involves a 90km transmission line between Guercif and Taza, while the second covers a 70km section between Taza and Fes East.
The scope of work includes the construction of tower foundations, installation of transmission supports and conductors, and associated high-voltage equipment. It also includes optical fibre cables for communications and monitoring, access roads and other supporting infrastructure.
The tender was issued in September with bids originally due by 21 October. The deadline has now been extended to 25 November.
The project is part of a wider programme by Onee to expand Morocco's electricity transmission network and accommodate additional renewable energy capacity.
In June, the utility commissioned a 274km, 400kV transmission line linking Chemaia and Mediouna, near Casablanca.
Onee plans to expand its high- and extra-high-voltage transmission network from more than 30,700km to 37,000km by 2030.
In August, it approved a $26.4bn investment programme for the 2026-30 period, covering electricity and drinking water infrastructure.
The programme has allocated about $21.9bn to electricity projects and $4.5bn to drinking water infrastructure, with about 72% of the investment to be financed by the private sector, according to Onee.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083507/main1257.jpg -
Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
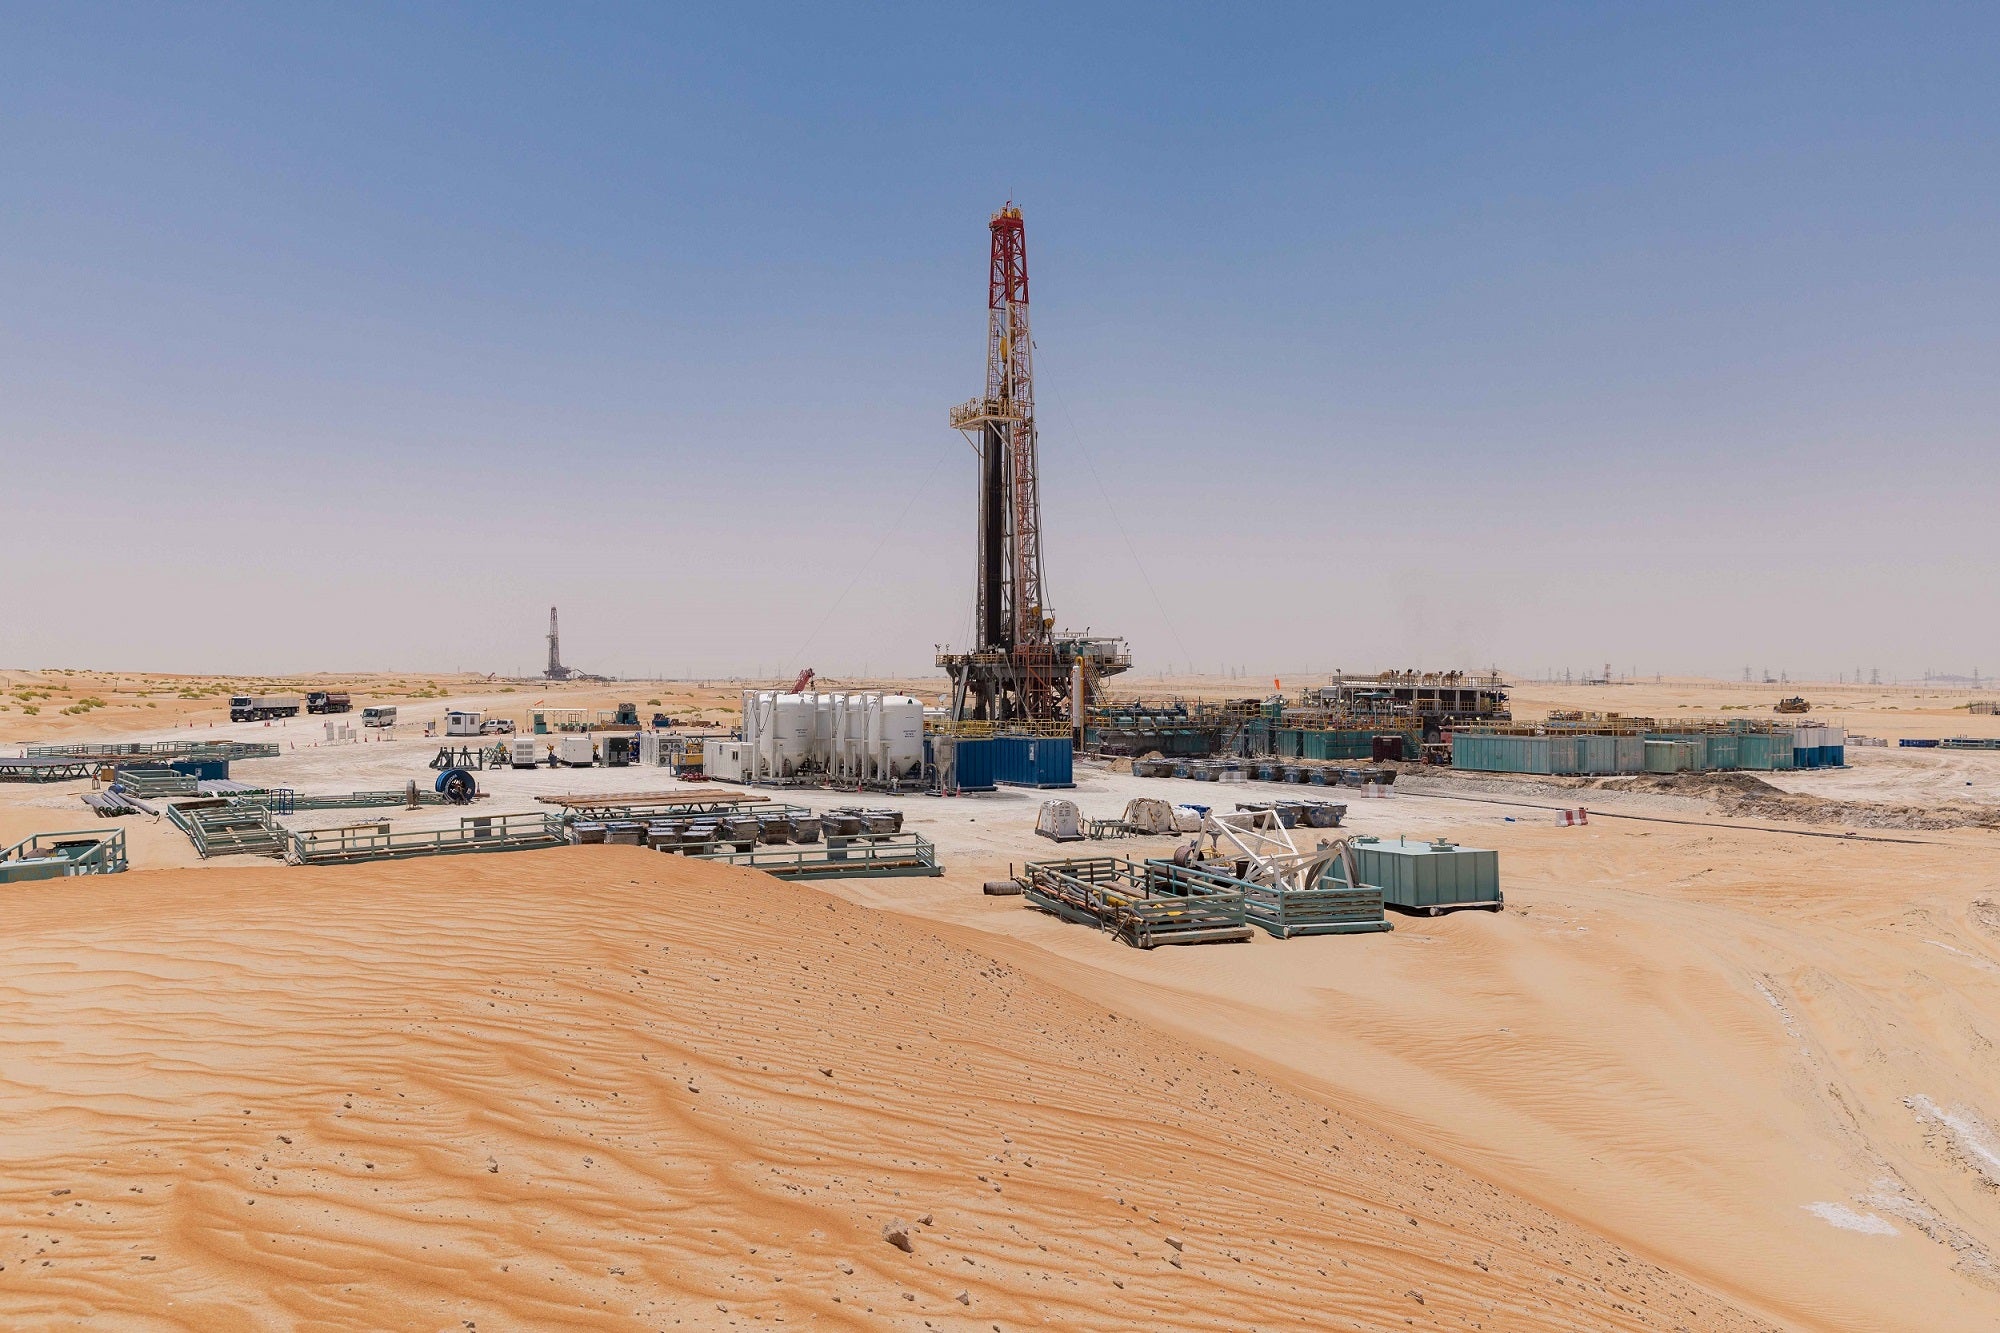
The onshore business of Abu Dhabi National Oil Company (Adnoc Onshore) has allowed contractors more time to prepare proposals for a project to tie in gas-producing and injection wells at the gas cap reservoirs of Abu Dhabi’s onshore Bab field.
The well tie-in scope, estimated to be worth more than $800m, forms part of Adnoc Group’s wider integrated Bab gas cap development programme.
The overall programme is being led and overseen by Adnoc Gas, another Adnoc Group subsidiary. Its central element is the construction of gas-processing infrastructure to handle incremental gas output expected from developing the Bab gas caps.
Adnoc Onshore issued the main tender for engineering, procurement and construction (EPC) works on the project in late September, MEED previously reported.
Contractors have been given until 16 November to submit technical bids for the project, according to sources. The previous deadline was 29 October.
MEED previously reported that Adnoc Onshore issued an expressions of interest (EoI) notice for the Bab gas production and injector well tie-in project on 13 May, with contractors submitting responses by 20 May.
The scope of work on the project covers the following:
- Tie-in of 99 new wells from Bab gas cap reservoirs KH-2, SH-1 and LK-1 (60 gas producers and 39 gas injectors);
- Installation of well gathering structures: 10 gas pads, six well bays and three virtual pads;
- Installation of a gas gathering network and a gas injection network;
- Rerouting of the LK-3 production from the existing trunkline in Remote Manifold Station 3 (RMS-3) to the project’s production trunkline, Bab Gas TL-2;
- Demolition of the existing 10-inch trunkline from RMS-3 to onshore gas development phase one.
In the EoI document, Adnoc Onshore said it intends to award the EPC contract in the last quarter of the year, with a 45-month duration of works.
Bab gas cap project infrastructure
As part of its 2030 upstream production increase goals, Adnoc Group is working to extract gas from four underdeveloped gas cap reservoirs at the Bab onshore field development – Thammama A, Thammama B, Thammama F and Thammama H.
While the Thammama A, B and H reservoirs are estimated to collectively produce 1.45 billion cubic feet a day (cf/d) of gas, output from the Thammama F gas cap is expected to be at a rate of 396 million cf/d.
Existing trains at the Habshan processing complex in Abu Dhabi will be unable to handle the new gas volumes. Therefore, Adnoc Gas is required to build new facilities to process an additional volume of up to 1.85 billion cf/d of raw gas.
Adnoc Gas is planning to build a gas processing plant in the Bab area, about 170 kilometres from Abu Dhabi, along with associated pipeline networks and other ancillary units, as part of the broader Bab gas cap development project. It has divided the EPC scope of work on the project into four packages:
- EPC package 1 – Main Bab gas cap plant
- EPC package 2 – Early civil works
- EPC package 3 – Pipelines
- EPC package 4 – Non-process area works
Abu Dhabi Securities Exchange-listed Adnoc Gas issued the tender for the main Bab gas cap plant on 25 June and set an initial deadline of 17 July for contractors to submit technical bids. The company then extended the technical bid submission deadline by four months, until 16 November, MEED previously reported.
Following a reshuffle of the consortiums gearing up to bid for the main Bab gas plant EPC package, estimated to be worth more than $6bn, the following teams have formed to compete in the main contract tendering round:
- Larsen & Toubro Energy Hydrocarbon (India) + Petrofac Emirates (UAE)
- Technip Energies (France) + JGC Corporation (Japan) + Sinopec (China)
- Tecnimont (Italy) + China Petroleum Engineering and Construction Corporation (CPECC)
The other three packages of the Bab gas cap project are also in the main contract tendering stages.
Prior to issuing the EoIs for the project packages, Adnoc Gas completed an early engagement process with contractors in September and October last year, as MEED previously reported.
In December last year, Adnoc Gas awarded the front-end engineering and design (feed) works for the development project to Australia-based consultancy Worley. The feed contract has a duration of more than 1.2 million man-hours, making it the largest-ever engineering job awarded by Adnoc Gas.
Bab Gas Cap concession
In addition to Adnoc Gas overseeing the main EPC tendering exercise for the gas processing plant, Abu Dhabi’s Supreme Council for Financial and Economic Affairs (SCFEA) awarded concession agreements in June for the development and production of the Bab gas cap reserve.
Adnoc will hold the majority 60% participating interest in the concession. The remaining stakes will be held by France’s TotalEnergies (10%), the UK’s BP (10%), China National Petroleum Corporation International (8%), Japan Oil Development Company Onshore (5%), China ZhenHua Oil (4%) and Korea GS E&P (3%).
According to the SCFEA, the Bab gas cap development and production concession represents the largest gas cap development project of its kind globally, the Abu Dhabi Media Office said in a report.
A gas cap refers to the free natural gas that sits above an underlying oil reservoir – in this case, the Bab onshore oil field in Abu Dhabi.
The project, operated by Adnoc Onshore, is expected to have a production capacity of approximately 1.5 billion cf/d of natural gas, equivalent to about 15% of Adnoc Gas’ total operational gas processing capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083343/main.jpg -
Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
More than 110 announcements worth over $20bn will be made at the Gateway Gulf Investment Forum in Bahrain, according to the country's finance minister.
"Over the next two days at Gateway Gulf, more than 110 announcements worth over $20bn will be made," Sheikh Salman Bin Khalifa Al-Khalifa, Finance & National Economy Minister, said at the opening of the forum's fourth edition on 1 November in Bahrain.
He said the announcements will cover new partnerships, investments, projects and jobs. Sheikh Salman addressed an audience that included Bahrain's Crown Prince and Prime Minister, Prince Salman Bin Hamad Al-Khalifa.
The minister said the region's economies have been "tested as never before" since the previous edition of the forum a year earlier.
"In the face of unprecedented attacks, we did not waver," he said. He added that Bahrain has chosen to work more closely with its allies and partners to defend what it has built.
Sheikh Salman said the Gulf economy has grown to $2.4tn in GDP. Non-oil sectors account for more than 86% of Bahrain's GDP and more than 77% across the Gulf, he said.
He said Gulf banks hold more than $4tn in assets, while the region's sovereign wealth funds manage more than $5tn of investments. "These numbers describe a region that has chosen to build a more stable, a more prosperous future for its people," he said. "Bahrain is the gateway to that region."
The minister said Bahrain is focusing on regulation, infrastructure and people to attract investment.
He said the country has developed a regulatory framework over several decades that is "clear, modern and fast", allowing investors to commit with confidence.
On infrastructure, he highlighted logistics, connectivity, digital networks and industrial land as areas where Bahrain is building the foundations for businesses to expand. He also named finance, logistics, tourism, manufacturing, technology and telecommunications, and oil and gas as the sectors into which he expects domestic, regional and international capital to flow.
He said the investments will create jobs for young graduates and support the growth of family businesses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21080593/main2015.jpg -
Egypt’s Petrojet wins gas pipeline project worth $170m
2 November 2026
An onshore gas pipeline contract awarded to Egypt’s Petrojet has a value of $170m, according industry sources.
The pipeline will connect to Egypt’s Damietta liquefied natural gas (LNG) export terminal and is part of a broader project to develop gas reserves in Cyprus and export the gas using infrastructure in Egypt.
Recently, several contracts have been signed in relation to the project, which is being developed by Italian oil and gas company Eni.
These include US-based Baker Hughes signing a contract for the design, procurement and construction of subsea production systems, including associated equipment and control systems.
Italy's Dalmine will supply subsea gas export and monoethylene glycol pipelines, while US-listed TechnipFMC will design, procure and manufacture flexible gas production pipelines.
In September, it was announced that US-headquartered McDermott will carry out offshore work for the project, including the transportation, installation and connection of subsea pipelines and equipment.
In a statement released on 26 October, Eni said: “The development will leverage a fast-track approach based on regional integration and the use of existing infrastructure.
“Gas produced from Cronos will be transported to Egypt, where it will be processed through existing facilities, including the Zohr infrastructure, before being liquefied at the Damietta LNG plant for export to international markets, primarily Europe.”
Gas production is expected to come online in the first half of 2028.
Since the US and Israel attacked Iran on 28 February, sparking a regional conflict, there has been increased interest in oil and gas assets in North African countries such as Egypt.
The ongoing conflict has made exporting oil and gas through the Strait of Hormuz and the Bab El-Mandeb Strait more difficult due to attacks on shipping.
Unlike many Middle East nations, Egypt, Algeria and Libya do not need to use these export routes and can continue to ship oil and gas without disruption.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21041454/main.jpg -
GCC projects market holds its nerve
1 November 2026
The war in the Gulf is now inflicting deep damage on the region’s economies. In its October World Economic Outlook, the IMF forecasts contraction in every GCC state except Oman in 2026. Saudi Arabia’s real GDP is projected to shrink by 3.3%, after 4.6% growth in 2025, and the UAE’s by 3.9%, after 6.2% growth.
 The IMF expects Kuwait’s economy to contract by 16.7%, Qatar’s by 15.6% and Bahrain’s by 11.3%, as energy and transport disruption cuts exports. Oman, with routes outside the Strait of Hormuz, is forecast to grow by 4.1%.
The fund has cut its 2026 forecast for the Middle East and Central Asia by 2.2 percentage points since April, to a contraction of 0.3%, citing a longer closure of the strait than it had previously assumed. The revision for Saudi Arabia is 6.4 percentage points. The IMF now assumes the strait will reopen in March 2027, with a return to prewar conditions broadly by October 2027.
There is little sign of an early end to hostilities. On 10 October, a Houthi-attributed strike on a passenger terminal at Riyadh’s King Khalid International Airport killed 12 people and injured 309, according to Saudi Arabia’s General Authority of Civil Aviation. Airport operations were suspended and several international airlines cancelled flights.
Yet the region’s projects market is holding up far better than its economies. Data from MEED Projects shows that contract awards in 2026 have proved resilient, with clients across the GCC continuing to commit capital to new schemes.
The GCC projects market has absorbed almost eight months of conflict better than its economies
Resilient awards
The UAE leads the regional market for a second consecutive year, with the value of contract awards 6.1% higher than in the same period of 2025. Oman and Kuwait are also running ahead of last year’s pace, despite the IMF’s forecast that Kuwait’s economy will contract by about a sixth.
Saudi Arabia has awarded $68.8bn of contracts so far this year, 13% less than in the same period of 2025. Given that the kingdom has been the main target of the Houthi campaign, and was already revising its spending priorities before the conflict, the decline is modest.
The comparison is against a high base. The past three years have seen unprecedented GCC capital expenditure, supported by higher oil prices, residential demand and national vision programmes. More than three quarters has been concentrated in Saudi Arabia and the UAE.
The gap between economic output and project spending reflects the nature of the projects market. Governments and state-linked entities can sustain capital budgets through a downturn using reserves and borrowing. GDP contraction, by contrast, reflects lost oil and gas exports, tourism and trade.
The UAE’s performance this year has been driven by the gas and transport sectors, which have recorded the strongest growth. Construction, the country’s largest sector, has declined as the real estate market has cooled.
Abu Dhabi has been the standout performer. Contract awards in the capital are up 35% on the same period of last year, with growth across the construction, gas, oil and transport sectors.
Public spending is a central reason for that resilience. Fitch Ratings expects Abu Dhabi’s spending to rise by 19% this year, equivalent to 3.7% of GDP, to support the non-oil economy. Data from the Central Bank of the UAE shows consolidated government capital expenditure rose to AED18.6bn ($5.1bn) in Q1 2026 from
AED2bn in Q1 2025.Fitch expects UAE infrastructure and government-related entity capital spending to rise significantly in 2026 and 2027, both to strengthen resilience against future conflicts and stimulate the economy. Emirates have already accelerated tendering on several projects.
Transport remains a priority. Plans include further sections of the national passenger rail network, a high-speed rail link between Dubai and Abu Dhabi, a light rail system in Abu Dhabi and the Dubai Metro Gold Line. The $35bn expansion of Al-Maktoum International airport in Dubai is moving towards delivery with the award of the first major construction packages.
Economic headwinds
Both the IMF and Fitch expect a strong rebound once the strait reopens. The IMF forecasts 2027 growth of 7.7% in the UAE, 7.9% in Saudi Arabia, 18.8% in Qatar and 17.1% in Kuwait. Fitch forecasts UAE non-oil growth of 6.1% next year. Paul Gamble, senior director at Fitch, cautioned that prolonged insecurity “will call into question logistical advantages” that underpin the UAE’s growth model.
Beneath the headline award totals, there are warning signs. Regional contract awards performed well between March and June, but the value of work awarded in recent months has dropped sharply compared with the same months of 2025. According to MEED Projects, the main cause is a fall in the number of tenders being issued, particularly in real estate.
The timing is significant. The strong period included the April ceasefire, when clients appear to have pressed ahead expecting a short conflict. Tendering slowed as hostilities resumed. In July, Iranian attacks reached Bahrain, Kuwait, Qatar, Jordan and Oman, while Houthi escalation against Saudi Arabia began.
The pattern suggests conflict fatigue may be setting in, with clients deferring projects amid a war with no clear end date. As tendering is a leading indicator, the impact on awards is likely to become more visible in coming months.
In Saudi Arabia, monthly performance has been mixed as the market adjusts to revised spending priorities and the regional conflict. Most sectors are up on last year, with the exception of power and water, which has struggled in 2026, possibly as a result of overbuilding in the past three years. The kingdom’s gigaprojects have continued their retreat. Awards peaked at $31.7bn in 2023 and fell to $14.4bn in 2025. The total so far in 2026 is $9.4bn, most of it for work at Qiddiya, Diriyah and Rua Al-Madinah.
The GCC has more than $3.4tn of known, planned and unawarded projects over the next 10 to 15 years
Dubai slowdown
The clearest signal of the conflict’s impact on the projects market comes from Dubai. The emirate’s market performed strongly until May. Since then, activity has been subdued, and contract awards for the year to date are 0.6% lower than in the same period of 2025.
The main cause is a decline in residential contract awards. Data from Bayut and the Dubai Land Department shows a marked fall in the value of off-plan sales since late February, when the war began. Residential construction awards have fallen in step, with no sign of the time lag that would normally be expected.
Third-quarter figures from Savills confirm the trend. Residential transactions fell 38% year on year to 34,500, and transaction value dropped 46% to AED70.8bn ($19.3bn) from AED132.2bn. The decline was concentrated in the off-plan segment, where value fell to AED45.7bn in Q3 from AED61.3bn in Q2, while ready-market value rose to AED25.1bn from AED21.3bn.
Developers have sharply reduced new launches. Savills recorded about 5,000 units launched in Q3, taking the total for the year to date to about 50,000, roughly 64% below the same period of 2025. Fewer launches mean fewer construction contracts, which explains why residential awards have fallen so quickly. More than 525,000 units are scheduled for delivery between 2027 and 2030, which Fitch says could add pressure to a sector accounting for 8% of non-oil GDP if population growth weakens.
Escaping Hormuz
The conflict is also generating new project demand. Saudi Arabia is prioritising ports and transport infrastructure on the Red Sea coast, along with new pipelines to the Red Sea and to Oman. The UAE is developing ports and transport links to the east coast and Oman, and additional pipelines to Fujairah. Fitch anticipates new and expanded road, rail, pipeline and port infrastructure in Oman and Saudi Arabia as GCC states seek routes that bypass the strait.
The IMF’s forecasts underline the value of those routes. It describes Saudi Arabia as “somewhat less affected” than its neighbours because of its more diversified export routes, while Oman is the only GCC state forecast to grow this year. Houthi strikes on Aramco facilities in Yanbu in September show that Red Sea infrastructure is not beyond reach, however. Defence spending is rising in both Saudi Arabia and the UAE, and repair and rehabilitation work will add to the pipeline once hostilities end.
The long-term fundamentals remain strong: the GCC has more than $3.4tn of known, planned and unawarded projects over the next 10 to 15 years, about half of it in Saudi Arabia. Many of the kingdom’s priorities are tied to fixed dates, with Riyadh hosting the World Expo in 2030 and Saudi Arabia hosting the Fifa World Cup in 2034.
The capacity to fund this pipeline depends on oil revenues. MEED’s assessment is that crude prices must remain above $70-$80 a barrel for spending levels to be maintained. With exports through Hormuz disrupted, the volume of oil Gulf producers can move to market matters as much as the price.
The GCC projects market has absorbed almost eight months of conflict better than its economies. The question for the final quarter is whether the slowdown in tendering is a temporary pause or the start of a sustained retreat. If the IMF’s assumption of a March 2027 reopening of the strait holds, clients will be setting their 2027 budgets with a rebound in sight. If it slips, the resilience of contract awards will face a sterner test.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21078685/main.gif