Riyadh steps up the Vision 2030 tempo
22 March 2023

Riyadh has begun pushing ahead with many of its Vision 2030 initiatives at a faster pace and in a much more tangible manner in the past six months, with the go-ahead given for several infrastructure packages on the kingdom’s flagship Neom project.
More than $13bn-worth of work has been awarded on Neom-linked projects since the start of 2022, including initial piling and tunnel blasting and drilling work for the Line development. More than $7bn has also been awarded in just the past five months, including $4.5bn across community housing schemes.
There has been equally robust activity on the other four official Public Investment Fund (PIF) gigaprojects. Projects worth another $1.8bn have been awarded since 2021 on the Diriyah Gate project, alongside $1.5bn-worth on the Roshn housing programme and $1.1bn each on the Red Sea Project and Qiddiya entertainment city.
Investment uptick
The shift in project tempo has also been matched by a step-up in other Vision 2030 initiatives, including the Shareek investment programme, which is aimed at supporting large Saudi companies in boosting the economic contribution of the kingdom’s private sector.
On 1 March, Saudi Arabia announced $51bn-worth of investments across eight Saudi companies as part of the programme. By 2030, Riyadh wants to increase the private sector GDP contribution to 65 per cent, while increasing the country’s non-oil exports from 16 to 50 per cent.
For external investors too, Saudi Arabia’s Vision 2030 plans are the top opportunity in the region, according to a recent poll by Egyptian financial services firm EFG Hermes. The survey showed that 34 per cent of respondents viewed Vision 2030 as the most important source of current investment opportunities.
There are meanwhile 23 companies waiting to list on the Saudi stock exchange. Those companies “are essentially on the runway waiting for the appropriate time, and obviously market conditions”, according to Mohammed ElKuwaiz, the chairman of the Capital Market Authority.
Last year was a record-breaking year for Saudi Arabia’s capital markets, with companies raising about $10.7bn (SR40bn) from initial public offerings (IPOs). The country also led regional IPO activity, with 34 out of the 48 GCC IPOs debuting on either the Tadawul or the Nomu.
Looking ahead, the Saudi market regulator is reviewing a further 77 IPO applications. It is also formulating a framework for dual listings, following the example of Americana, the first company to be dually listed in the kingdom and the UAE.
More broadly, the business confidence in the non-oil private sector continues to swell. In February, Saudi Arabia’s non-oil business activity reached its highest level in eight years due to a surge in demand, according to the Riyad Bank–S&P Saudi Arabia Purchasing Managers’ Index.
The index – in which a figure above 50 indicates expansion – increased from 58.2 to 59.8 in the fastest rate of increase since March 2015. The new orders component of the index rose to a record high of 68.7, with over 42 per cent of surveyed companies reporting a rise in new orders. The overall higher output also saw further employment and purchasing expansion.

Despite tighter monetary conditions, Naif al-Ghaith, Riyad Bank’s chief economist, noted the robust demand and supply balance spurred by the ongoing projects in the kingdom, which has caused “sharper uplifts in output and new orders for firms, as well as rising demand for labour”.
He added that while “prices have responded to the surge in demand, with the increase in input costs evident especially in the services and construction sectors”, business confidence remains high amid expectations for strong ongoing activity over the next 12 months.
Growth forecast
Despite the positive economic signs, the IMF reduced its 2023 GDP projection for Saudi Arabia to 2.6 per cent in January. This is in response to Opec+ agreements to restrict oil production 1.3 percentage points below the projection of 3.9 per cent growth in its October outlook.
Though non-oil growth remains strong, the reduction in oil output will unavoidably impact Saudi Arabia’s topline GDP. At the same time, the toll on oil revenue should be relatively contained and not unduly affect the kingdom’s capital spending, which is at this point being backed by a diverse pool of both sovereign and private assets.
According to a late February forecast by Riyad Capital, Saudi Arabia’s economy could grow by 3 per cent in 2023, driven principally by a pick-up in the non-oil sector, which it predicts will see a growth rate of 5 per cent this year.
In 2022, Saudi Arabia witnessed its strongest growth in the third quarter, when the GDP rate hit 8.8 per cent, according to the IMF, boosted by a 6.2 per cent growth rate for non-oil activity.
Riyad Capital also expects the weaker oil prices during the first half of 2023 to recover in the second half of the year, with Brent crude expected to end 2023 at a level above $100 a barrel.
MEED's April 2023 special report on Saudi Arabia includes:
> CONSTRUCTION: Saudi construction project ramp-up accelerates
> UPSTREAM: Aramco slated to escalate upstream spending
> DOWNSTREAM: Petchems ambitions define Saudi downstream
> POWER: Saudi Arabia reinvigorates power sector
> WATER: Saudi water begins next growth phase
> BANKING: Saudi banks bid to keep ahead of the pack


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Stability holds as project work continues
14 October 2026
-
 Gas-fired projects drive resilience in UAE power sector
14 October 2026
-
 Riyadh awards $1.5bn metro rolling stock contracts
14 October 2026
-
 Jeddah extends bid deadline for drainage scheme
14 October 2026
-
 US initiates procurement for Expo 2030 Riyadh pavilion
14 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Stability holds as project work continues
14 October 2026
When Dean McGrail describes the performance of the region’s construction market, he keeps returning to a single word: “stable”.
After initial concerns that the market would experience a sharp downturn and project cancellations following the onset of conflict in the region, regional president McGrail says WSP has yet to see a single major contract cancelled across its regional portfolio.
“We have seen some projects re-evaluated – questions around whether the mix between residential and commercial is right, and whether it should be luxury residential,” he says. “But as of today, we have not seen any projects cancelled, which is a real sign of resilience in the market.”
Under the surface
That resilience does not mean nothing has changed. McGrail is careful to separate re-evaluation from cancellation. Projects already on site and selling into the market are pressing ahead. It is schemes that have not yet been released for off-plan sales that are being paused and reconsidered.
“None of the projects we are currently involved in have been put on hold or suspended,” he says. “It is more re-evaluation. Some of that is investor sentiment, but some of it is materials and logistics as well, which people do not necessarily consider.”
Logistics, in particular, is a pressure that rarely makes the headlines. According to McGrail, shipping disruption has complicated the delivery of heavy equipment on certain schemes. “If we have big pieces of kit coming in – chillers or turbines for a power station – that becomes challenging,” he says.
The bigger question is viability. And while rising material costs, set against softening sales prices, are forcing developers to reappraise the numbers, for now the balance sits firmly on the side of continuity. McGrail estimates that revalidation and feasibility work accounts for less than 3% of the firm’s current order book, with the remainder progressing as normal.
“Requests for proposals have not slowed down across any of our disciplines or business units,” he says. “We are definitely seeing an uptick in infrastructure.”
Infrastructure pivot
That focus points to where McGrail expects the next few years of growth to come from. Rail sits at the centre of the UAE story, alongside road upgrades and other major developments in Abu Dhabi. In Dubai, the clearest signal of intent is the expansion of Al-Maktoum International airport.
“Al-Maktoum is a really good indicator of the future direction of travel,” he says. “That is not a project that is slowing down. There has been a commitment to Emirates that it will move there, and it is still progressing.”
The scale of the airport – and the challenge of relocating an airline the size of Emirates in one move – raises the question of how it will be funded. Here, McGrail returns to the theme of stability and to the mechanism that underpins it.
“One of the beauties of this region is the ability of government to step in,” he says. “They can fund it. If the private sector does start to suffer, that is the backstop. They push money into infrastructure – roads, rail, airports – which keeps our industry moving.”
Saudi reset
In Saudi Arabia, the recalibration story predates the conflict, and McGrail says the change should be read as a strength rather than a retreat.
“I am positive,” he says. “When the reprioritisation started at the beginning of 2025, having lived through the global financial crisis here, I saw the decision to stop, re-evaluate and reprioritise expenditure as a positive. When Vision 2030 was set, Saudi Arabia had not won Expo or the World Cup, so the reprioritisation was the right thing to do. Saudi Arabia will come out of it stronger. Short-term pain, long-term gain.”
The nature of the work is shifting with the budget. McGrail sees the kingdom moving towards a model long familiar in the UAE, in which core infrastructure and a handful of landmark buildings are delivered first, before surrounding plots are carved up and sold on.
“You establish a few key iconic buildings, then the plots on the outside are carved up and they look for external investment to come in and develop them,” he says. “It is no different from Downtown Dubai, where Emaar built the Burj Khalifa and a few buildings, then started selling plots.”
That approach is increasingly tied to public-private partnerships (PPPs), although McGrail is measured on how far the model will stretch.
“PPP is definitely becoming more prevalent on some of the larger infrastructure projects, though still not as significant as it was made out to be when they first started talking about it,” he says. He sees industrials, mining, healthcare and schools as a natural fit, rather than PPP becoming a blanket procurement route.
Aviation is another priority. WSP was recently appointed to the rehabilitation of the existing terminal at Jeddah’s King Abdulaziz International airport, alongside a new terminal. It also recently secured a role on the expansion and upgrade of King Fahd International airport in Dammam.
“Aviation is definitely a key area of focus for us as we head into the next 12, 24, 36 months,” McGrail says.
Beyond the two dominant markets, McGrail sees pockets of activity but no challenge to the balance of the portfolio. In Qatar, he points to a recovery taking shape towards the end of last year, with WSP active on the Qatar Children’s Museum and continuing its long-running work with the Public Works Authority (Ashghal). Oman is generating masterplanning work, including reviving the Blue City scheme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20545689/main.gif -
Gas-fired projects drive resilience in UAE power sector
14 October 2026
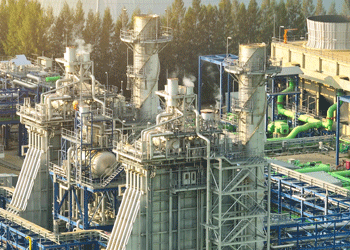
The $3bn Taweelah C combined-cycle gas turbine (CCGT) project has been the UAE power sector’s standout contract award this year, accounting for the majority of the $4.17bn in awards as of early September.
The total is well below the record $12.02bn awarded in 2025, when Abu Dhabi’s $6bn round-the-clock solar photovoltaic (PV) and battery energy storage system (bess) project lifted the market to record levels. However, 2026 remains broadly consistent with recent years, compared with $5.93bn in 2024 and $3.05bn in 2023.
According to MEED Projects, generation accounted for $3.06bn across three awards, while transmission contracts totalled $1.11bn.
Gas-fired focus
Emirates Water & Electricity Company (Ewec) signed the power-purchase agreement (PPA) for Taweelah C in June with a consortium comprising Abu Dhabi National Energy Company (Taqa), Saudi Arabia’s Al-Jomaih Energy & Water Company and Singapore’s Sembcorp Industries.
The scale of the 2.5GW independent power producer (IPP) provides a useful lens through which to view the wider market. Although the UAE continues to expand solar generation and battery storage, it is still investing heavily in flexible thermal capacity to support rising electricity demand and a grid with significant renewable generation.
Major gas-fired opportunities are also moving into the Northern Emirates, with state utility Etihad Water & Electricity (EtihadWE) preparing to receive offers from five contractor groups for the 2.6GW Al-Zawra CCGT project in Ajman.
The project follows the retirement of EtihadWE’s older 200MW Al-Zawra gas plant in 2023. With Ewec acting as offtaker, the scheme also points to a wider role for EtihadWE in developing large-scale generation.
It is understood that the Ajman project will be the first of at least three planned power plant projects procured by the utility under a new long-term roadmap for future projects across both power and water.
Abu Dhabi’s 3.3GW Al-Nouf IPP is another major gas-fired plant moving towards execution. Japan’s Sumitomo Corporation is expected to formally sign the PPA by the end of the year, while the joint venture of Spain’s Tecnicas Reunidas and Egypt’s Orascom Construction is also set to be confirmed as the engineering, procurement and construction (EPC) contractor.
To put this into context, the deal would make 2026 the second most valuable year for power sector investment on record, eclipsing both 2017 and 2018, when contract awards in the UAE reached $7.39bn and $7.27bn, respectively.
Solar and storage
The UAE’s renewable procurement is increasingly combining solar generation with storage to provide electricity beyond daylight hours.
Dubai Electricity & Water Authority (Dewa) is preparing to award the seventh phase of the Mohammed Bin Rashid Al-Maktoum Solar Park, with Abu Dhabi Future Energy Company (Masdar) submitting the lowest tariff for the project in July.
China’s BYD will act as a bess supplier for the project, which combines 2,000MW of PV capacity with a 1,400MW bess designed to discharge for six hours, equivalent to 8,400MWh of stored energy.
The storage component will allow Dewa to use more solar power after sunset, reducing the gap between daytime generation and the evening demand peak.
The 1,800MW sixth phase is also nearing completion, with Larsen & Toubro delivering the estimated $1.5bn project for Shuaa Energy 4, the project company formed by Dewa and Masdar.
Dewa has increased the planned capacity of the solar park to 7,260MW by 2030, from its earlier target of 5,000MW.
Furthermore, Ewec is advancing its 1.5GW Al-Zarraf solar PV plant, with EDF and Korea Western Power Company selected as the consortium to develop the project.
Grid expansion
Multibillion-dollar IPP schemes have driven annual award values in recent years, while transmission work continues to provide a steadier flow of opportunities for contractors and equipment suppliers.
Transmission awards fell to $1.11bn across 22 packages in 2026, from $2.98bn in 2025, reflecting the absence of a comparable large-scale package rather than a halt in network investment.
Ewec and Taqa are expanding 400kV and 132kV networks across Abu Dhabi and the Northern Emirates, while Dewa continues to reinforce its cable and substation systems in Dubai.
In September, EtihadWE received bids for a contract to carry out a techno-economic feasibility study for a proposed 2GW subsea electricity interconnector with India.
The proposed 1,400-kilometre link would be the UAE’s first direct subsea cross-border electricity interconnector, illustrating a potential longer-term ambition to connect the UAE to wider regional and international power markets.
Earlier this year, the GCC Interconnection Authority awarded Omexom, part of France’s Vinci Group, a contract to build a 400kV overhead transmission line between the UAE and Saudi Arabia.
In October, the UAE and Saudi Arabia signed a memorandum of understanding to advance cross-border electricity interconnection, paving the way for feasibility studies on power exchange, commercial electricity trading and the expansion of the wider GCC interconnection grid.
Waste-to-energy
Waste-to-energy continues to become an increasingly important part of the UAE’s infrastructure pipeline as the country seeks to reduce landfill dependence and diversify its power mix through alternative generation sources.
Dubai Municipality recently invited developers to submit expressions of interest for its planned Jebel Ali waste-to-energy public-private partnership, a greenfield facility designed to treat up to 6,000 tonnes of municipal solid waste a day.
According to a source, the municipality plans to prequalify developers later this year, then issue a request for proposals in the first quarter of 2027.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20582379/main.gif -
Riyadh awards $1.5bn metro rolling stock contracts
14 October 2026
Register for MEED’s 14-day trial access
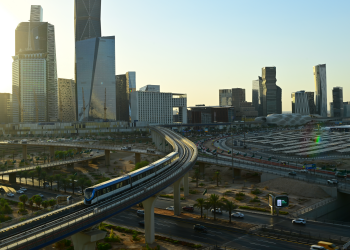
Saudi Arabia’s Royal Commission for Riyadh City (RCRC) has signed contracts worth about SR5.5bn ($1.5bn) to procure 94 additional trains for the Riyadh Metro network.
Germany’s Siemens and France’s Alstom have been awarded the contracts. They cover rolling stock manufacture, onboard systems, equipment and related services.
The procurement will increase the metro fleet from 183 to 277 trains. Deliveries are due to begin in phases in 2028, with the additional units subject to testing and operational trials before entering service.
RCRC expects the programme to increase the network’s passenger capacity by 60%.
The additional trains will be distributed across the six metro lines based on current demand and projected ridership.
The Red Line will receive the largest capacity increase, at 142%, followed by the Yellow Line at 116% and the Blue Line at 60%. Capacity on the Orange and Purple lines will increase by 27% and 16%, respectively.
Daily capacity on the Blue Line is set to increase from about 340,000 to 533,000 passengers. Capacity on the Red Line will rise from 154,000 to 370,000 passengers a day, while the Yellow Line will increase from 133,000 to more than 288,000.
The expansion is intended to meet rising demand for public transport as Riyadh prepares to host Expo 2030 and the 2034 Fifa World Cup, alongside continued growth in residential, commercial and entertainment developments.
Speaking at the 37th government press conference, RCRC chief executive Ibrahim Al-Sultan said the metro has carried more than 300 million passengers since it began operating.
Average metro ridership rose by about 25% in the first nine months of 2026 compared with the same period in 2025, he added.
The wider Riyadh public transport system, including buses and the metro, is approaching 500 million passenger journeys.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20582763/main.png -
Jeddah extends bid deadline for drainage scheme
14 October 2026
Jeddah Municipality has extended the deadline for contractors to submit bids for the construction of a rainwater drainage network for the Prince Fawaz neighbourhood.
The new deadline is 15 November. The original deadline was 12 October.
The project aims to collect and convey rainwater away from residential streets and low-lying areas. It is valued at $60m and is intended to reduce flood risk during heavy rainfall.
The scope includes manholes, stormwater catch basins and connections to existing manholes, as well as the restoration of road surfaces.
Prince Fawaz is a residential district in southern Jeddah, divided into northern and southern sections.
It is connected to the Mecca-Jeddah Expressway and Al-Harmain Road, with road improvements in the southern section designed to improve access for residents and neighbouring districts
The municipality is also advancing a second stormwater drainage project for the first package of Zone (BC), Old Zahraa, in Jeddah Governorate. The project is valued at about $30m.
According to a source, bids were submitted for the project on 16 September.
The two projects are part of the municipality’s wider drainage programme, which includes the flagship King Abdullah Road-Falasteen Road tunnel project.
MEED previously reported that Saudi contractor Thrustboring Construction Company had been selected for phases one and two of the project, each valued at about $175m, covering the construction of large-diameter stormwater drainage tunnels. As of August, an official agreement had yet to be signed.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20580980/main.jpg -
US initiates procurement for Expo 2030 Riyadh pavilion
14 October 2026
Register for MEED’s 14-day trial access
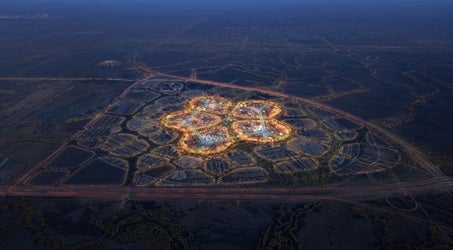
The US Department of State has initiated market research to procure a design-and-build contract for the US Pavilion at Expo 2030 Riyadh.
According to procurement documents released through the US federal contracting portal, the project covers the full design, construction, exhibition fit-out, maintenance, and eventual decommissioning and removal of the national pavilion.
The total cost for the design, construction and decommissioning packages is estimated at $55m to $65m.
The request for information notice was issued on 9 October.
The pavilion will be developed on plot P5.N1.B03.01 within the Expo 2030 masterplan’s Technology district, fronting the Loop of Nations corridor.
It spans 5,368 square metres (sq m), with a maximum permitted gross floor area (GFA) of 8,052 sq m and an overall building height limit of 20 metres.
The planned temporary structure will rise approximately three storeys and house between 5,000 and 6,000 sq m of exhibition space. The brief requires the facility to accommodate at least 23,000 visitors a day over the event’s six-month duration.
Additional programme elements include:
- A rooftop garden and restaurant
- Two commercial kitchens
- A VIP reception suite
- Dedicated retail and administrative office space
- Back-of-house operational areas and exterior shaded public landscaping
Interested contractors and joint ventures have been invited to submit capability statements by 11 November. Bidders must demonstrate prior experience delivering major pavilions or large-scale immersive exhibition spaces completed within the past 15 years, alongside international logistics and regional project delivery capabilities.
UK-based engineering consultancy Buro Happold prepared the plot masterplanning and development guidelines for the zone.
Another UK-headquartered firm, Trivandi, was selected in April as the operations partner for the US Pavilion at Riyadh Expo.
Expo 2030 Riyadh will run from October 2030 to March 2031 under the theme Foresight for Tomorrow, with host authorities projecting roughly 42 million visits.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event.
Situated north of the Saudi capital, the site will be near the future King Salman International airport and will provide direct access to Riyadh landmarks.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched Expo 2030 Riyadh Company – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20580855/main.jpeg