Resurging projects uplift UAE and Saudi economies
29 January 2024

The UAE and Saudi Arabia are almost neck-and-neck – with the UAE marginally in the lead – at the top of the MEED Economic Activity Index, which assesses the near-term economic health of regional markets.
In October 2023, both countries were forecast by the Washington-based IMF to grow at a region-beating rate of 4% in real GDP terms in 2024, though without taking into account the deepening of voluntary oil production cuts in November by half a dozen Opec+ countries, among them Saudi Arabia and the UAE.
In the Q4 Opec+ meeting, in addition to the voluntary cuts announced in April 2023 and extended until the end of 2024, Saudi Arabia and the UAE agreed to cut their oil production by a further 1 million barrels a day (b/d) and 163,000 b/d, respectively, until the end of Q1 2024.
The impact of these additional cuts, as well as the trailing of the oil price below the IMF’s forecast of $79.9 a barrel in 2024, remains to be seen, but – other factors notwithstanding – it should be negative.
In spite of this, some think tanks and ratings agencies have given both countries even more bullish real GDP projections since the start of the year. Aljazira Capital has forecast a 4.4% real GDP growth figure for Saudi Arabia in 2024 and ratings agency Moody’s has projected an even higher 4.6% growth rate.
Aljazira Capital stated that weaker oil revenues “would be offset by growth in non-oil revenues” from the private sector amid the implementation of non-oil spending programmes under Saudi Vision 2030.
For the UAE, ratings agency Standard and Poor’s (S&P) meanwhile forecast 5% growth in 2024 – also driven by the non-oil sector, which grew by 6% in 2023, led by hospitality, retail and financial services.
Beyond the headline figures, both countries are keeping their inflation and fiscal balance in check and have relatively contained unemployment levels. However, Saudi Arabia’s figures of 5.6% unemployment and 23.8% youth unemployment both remain well above average for the GCC countries.
Projects boom
Both countries have also seen a surge in projects activity. Together, they were responsible for the bulk of the $253bn in contracts that made 2023 a record year for regional project activity.
In Saudi Arabia, the total awards value for the year was 59% higher, rising to $95bn – double the long-term average value of project awards over the preceding 10 years. New work also outstripped project completions by a ratio of almost four to one, adding $70bn to the net value of projects under execution.
In the UAE, the value of project awards leapt by 175% to hit $81.5bn – a value almost close to double the long-term average. Significant project completions worth more than $48bn nevertheless weighed on the market and reduced the net change in the value of projects under execution to $33bn.
Other markets
The other GCC countries have mixed outlooks, with varying growth forecasts and projects market activity.
Qatar has a modest 2.2% growth projection for 2024 and has maintained recent project awards at a level matching the rate of completion of legacy projects, as well as the long-term award value average.
Kuwait’s economy was given a 2024 growth forecast of 3.6% by the IMF in October, after contracting in 2023, but this does not include the voluntary production cuts announced in November. The country’s projects market meanwhile continues to slip, with its 2023 awards sitting at just 76% of its average.
The revision of Oman’s 2024 growth forecast by the IMF in January provides a glimpse into the impact of the additional voluntary oil production cuts announced in November for Q1, with the country’s real GDP growth projection for the year having been revised down markedly from 2.7% to 1.4%. The country’s projects market is nevertheless largely holding its own, with its 2023 contract awards clocking in at 88% of the long-term average, even as completions slightly exceeded new awards.
Bahrain continues to struggle with a persistent fiscal deficit and deepening debt, and the squeezing of the country’s cash flow is being reflected in its sinking projects market. The $1.2bn in awards in 2023 flagged 32% behind completions and 65% below the market’s long-term average.
Morocco has increasingly emerged as one of the least troubled markets in the wider Middle East and North Africa region, with a solid 3.6% growth projection for its largely non-hydrocarbons economy. Inflation in the country has also been curbed and the $2.4bn in project awards in 2023 exceeded completions by 24%, despite dipping below the long-term average.
Egypt is heading into 2024 facing severe economic headwinds, with high inflation amid falling foreign exchange reserves and the looming prospect of a further currency devaluation, short of an IMF bailout. The country’s mounting fiscal trouble has been reflected by falling projects activity, with the $12.6bn in awards in 2023 being both below the level of completions and 44% below the long-term average.
Tunisia has a forecast of just 1.9% real GDP growth, but an unexpected burst of $1.5bn in project awards in 2023 boosted projects activity – with the value nearly double both completions and average awards.
Algeria, Iraq and Jordan face various headwinds, but chief among their problems is that their middling growth rates are insufficient to accommodate either their rising debt or double-digit unemployment. All three countries also had projects markets that underperformed in 2023, with award values below both the level of completions and long-term averages.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
-
 Drilling resumes at Iraq’s Akkas field
8 October 2026
-
 Neom extends bid deadline for Oxagon wastewater plant
8 October 2026
-
 Syria seeks interest for $1.16bn Euphrates dam
7 October 2026
-
 Arada launches UAE construction arm with Roberts
7 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Iraq discusses starting operations at $3.78bn refinery project
8 October 2026
Iraq’s Minister of Oil, Basem Muhammad Khudair Al-Abadi, has met with Japanese officials to discuss plans to commission the fluid catalytic cracking (FCC) unit at the Basra refinery upgrade project, according to a ministry statement.
The meeting was attended by the Japanese Embassy’s executive officer as well as representatives from the Japan International Cooperation Agency (Jica) and Japan-based JGC, which is the main contractor on the project.
According to the ministry, discussions focused on direct implementation steps and coordination between Iraqi authorities and the Japanese partners to bring the unit online using Japanese refining technologies.
Iraq’s South Refineries Company (SRC) sent JGC notice of the main contract award for the Basra refinery upgrade project’s FCC package in August 2020.
JGC was awarded the contract in consortium with South Korea’s Hyundai E&C.
The official contract signing ceremony was held in Baghdad on 1 October 2020.
The contract awarded to JGC, which uses the engineering, procurement, construction and commissioning model, was worth $3.78bn.
Project delays
The project has faced issues related to the ongoing regional conflict, which started when the US and Israel attacked Iran on 28 February.
JGC evacuated its personnel from the site in the southern oil hub of Basra following the start of the regional war, stopping work on the project, which was in its final stages of construction.
In August, JGC signed an agreement to restart work.
The project will produce around 5 million litres a day of gasoline and 7 million litres a day of diesel.
The FCC package is part of a broader project to upgrade the Basra refinery.
Oil Ministry officials said in late 2025 that the Basra refinery upgrade project aims to slash Iraq’s fuel import bill and convert heavy refining residues into high-value petroleum products.
The project site is located about 12 kilometres east of Iraq’s southern city of Basra.
The wider upgrade project is installing new facilities on land adjacent to the existing Basra refinery, including a vacuum distillation unit and a diesel desulphurisation unit.
In April 2021, France’s Axens won a contract to provide four process technologies to SRC for the Basra refinery upgrade project.
The technologies that SRC selected are:
- Diesel hydrotreatment unit (Prime-D)
- Vacuum gasoil (VGO) hydrotreating unit
- VGO fluid catalytic cracker unit
- Oligomerisation unit (polynaphtha)
In addition, Axens is providing catalysts and adsorbents and proprietary equipment, training and technical services.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20366574/main.png -
Drilling resumes at Iraq’s Akkas field
8 October 2026
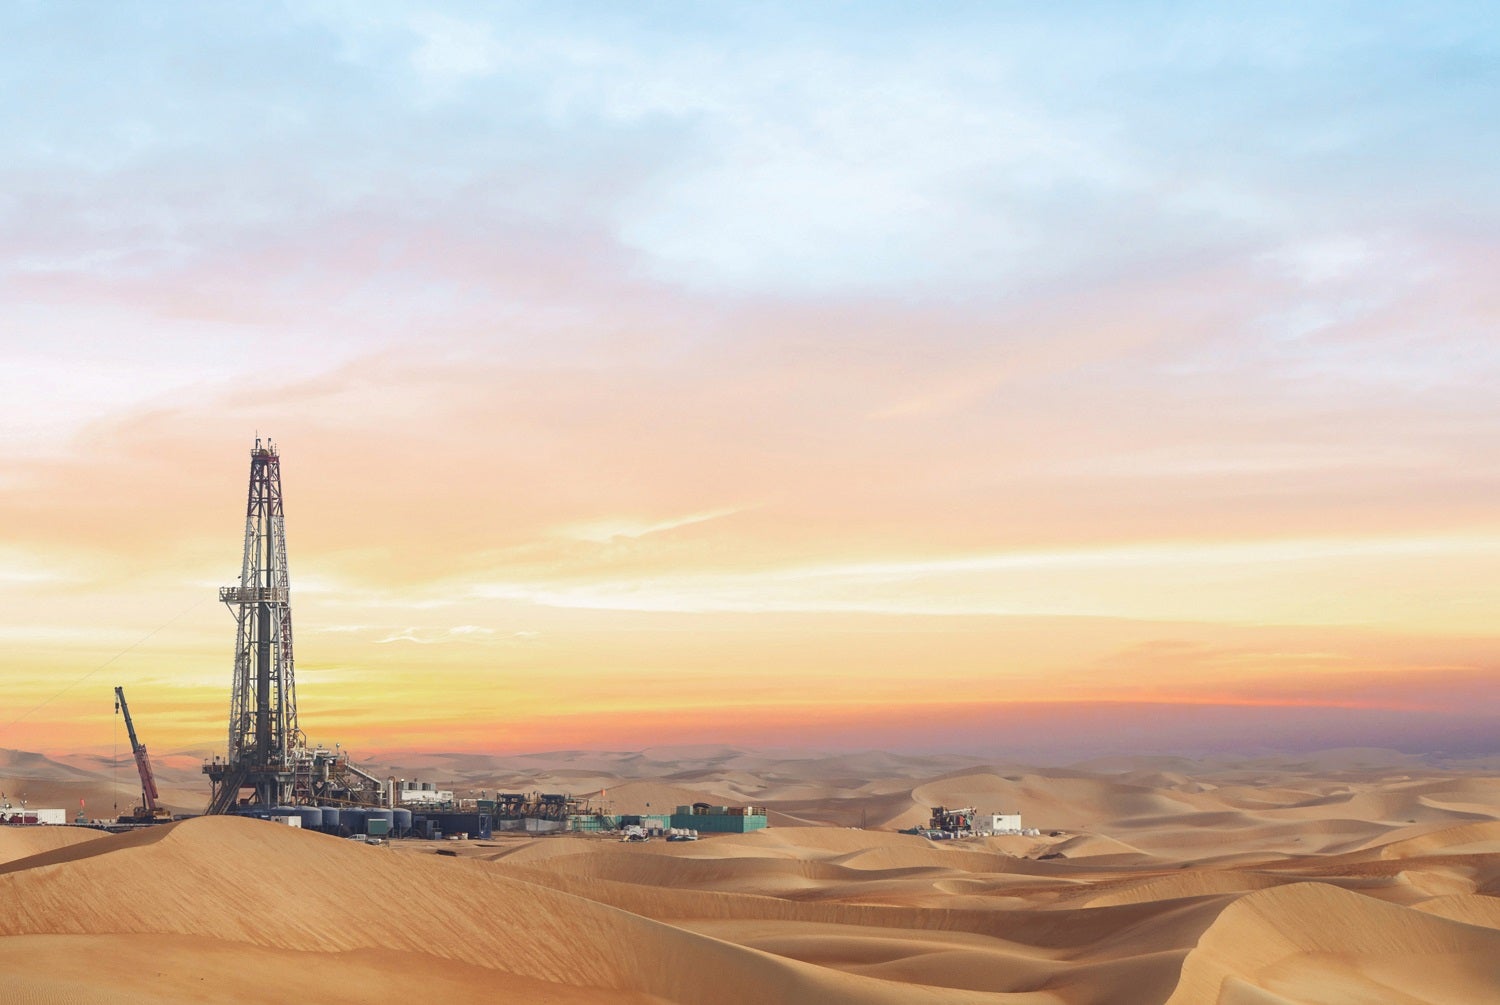
Drilling has resumed as part of the project to further develop Iraq’s Akkas gas field, according to industry sources.
In March, MEED reported that development of the field had been disrupted by security issues related to the US and Israel’s war with Iran.
Activity at the project site had been significantly reduced due to security concerns, which led to the evacuation of most non-Iraqi workers.
Now, the project is progressing and drilling at the field is ongoing, sources said.
One source said: “Many of the major issues that stopped drilling at the site have been dealt with in various ways, and the development of the field is proceeding.”
Iraq held a ceremony in January to mark the start of drilling operations under the current phase of development. In July of the previous year, the Iraqi Oil Ministry announced a contract with US-based oilfield services provider SLB to develop the field. Under the agreement, SLB is drilling wells to raise initial output to 100 million cubic feet a day (cf/d), with a long-term production target of 400 million cf/d.
The contract with SLB replaced a previous deal with Ukraine-based Ukrzemresurs, which has been terminated.
It also covers the construction of surface infrastructure and pipelines to connect Akkas to central processing units.
The gas produced at Akkas will fuel the Anbar combined-cycle power plant, which the Electricity Ministry is building.
Akkas gas field development
Located in western Anbar province, Akkas holds an estimated 5.6 trillion cubic feet of proven natural gas reserves. The field was discovered in 1992 and entered initial production in 1993, but efforts to develop it commercially have faced repeated delays.
Development rights were originally awarded to a consortium of South Korea’s Kogas and Kazakhstan’s KazMunaiGas (KMG) during Iraq’s third licensing round in 2010. After KMG withdrew, Kogas took over as sole operator under revised contractual terms before work was subsequently halted.
In April 2024, the Oil Ministry signed an agreement with Ukraine’s Ukrzemresurs targeting 100 million cf/d within two years and 400 million cf/d within four years. However, the deal faced strong domestic political resistance.
Iraq’s parliamentary Oil and Gas Committee opposed the award, with committee member Ali Al-Mashkour telling Shafaq News Agency: “This contract involves a great waste of Iraq’s wealth, and there will be a waste of Iraq’s oil, and this confirms that Iraq is once again failing to choose reputable companies to work with in the most important economic field in the country.”
He added: “We will work to uncover and expose the suspicions in this contract during the next stage, especially since this contract was made by some representatives for specific interests, which we will reveal soon with evidence.”
The deal was subsequently terminated, paving the way for the current contract with SLB.
The development of Akkas is central to Baghdad’s broader ambition to transition from a net gas importer into an exporter. Iraq remains heavily dependent on gas imports from Iran to meet domestic electricity demand. Both the US and Saudi Arabia have backed Iraq’s efforts to develop non-associated gas fields to reduce its economic and energy dependence on Tehran.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20366494/main5816.jpg -
Neom extends bid deadline for Oxagon wastewater plant
8 October 2026
Neom has extended the bid submission deadline for a contract to build a wastewater treatment plant for Oxagon, its industrial cluster.
According to a source, the new deadline is 25 October. The original deadline was 2 October.
Enowa, Neom’s energy and water utility, is tendering the contract.
The industrial wastewater treatment package will have an initial capacity of 35,000 cubic metres a day (cm/d), supplied in modular trains of 5,000 cm/d each. A separate sanitary wastewater treatment package will have a capacity of 1,000 cm/d.
The contract is structured as a design-build-operate project and covers the supply, installation and commissioning of industrial and sanitary wastewater treatment packages, as well as three years of operation and maintenance.
According to sources, local contractor Alfanar, Beijing-based PowerChina and France-based Veolia are among the companies preparing bids.
The project follows an earlier tender for the Oxagon Village Water Recycling Plant, which was cancelled despite contractors submitting bids in 2024.
MEED reported at the time that PowerChina, Alfanar and Cairo-headquartered Orascom had submitted bids for that project.
The earlier scheme included truck-receiving facilities, pretreatment, biological treatment using food chain reactor technology, tertiary treatment, sludge handling and recycled-water storage.
The latest procurement appears to take a reworked approach to wastewater treatment at Oxagon Industrial Quarter. It replaces the previous engineering, procurement and construction scheme with an interim modular and demountable facility.
The plant is designed to provide “interim wastewater treatment” capacity for Oxagon Industrial Quarter as industrial development progresses.
As MEED understands, this includes treatment systems that can be installed and subsequently removed or relocated as requirements at Oxagon evolve. The plant can be expanded to a maximum capacity of 45,000 cm/d.
The tender documents also state that Neom may consider export credit agency (ECA) financing for the project. The strength of bidders’ ECA financing proposals will form part of the commercial evaluation.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20347018/main.jpg -
Syria seeks interest for $1.16bn Euphrates dam
7 October 2026
Register for MEED’s 14-day trial access
Syria’s Ministry of Energy has invited expressions of interest (EoIs) for the development of the Halabiyeh-Zalabiyeh dam project on the Euphrates River.
The project has an indicative total cost of $1.16bn, according to the ministry’s EoI document. This includes $433.7m for the dam and hydropower plant and $729.6m for the pumped-storage power plant (PSP).
The scheme includes an 81MW hydroelectric power plant and a pumped-storage facility with a capacity of up to 1,200MW. The project will also include the construction of the dam and associated water-storage infrastructure.
The ministry seeks interest from qualified local and international companies, investors and other entities. Interested parties can participate in studies, design, financing, construction, and operation and maintenance of the project.
The ministry is considering several potential development structures, including build-own-operate-transfer, build-operate-transfer and public-private partnership models, as well as an engineering, procurement and construction (EPC) structure. It has said it is also open to proposals covering consultancy and financing services.
The EoI covers several stages, including pre-feasibility and feasibility studies, financing and bankability studies, detailed and executive design, EPC execution, and operation and maintenance.
The technical specifications envisage a 23-metre-high dam with a reservoir storage capacity of about 219 million cubic metres.
The hydropower plant will have three generating units, while the 1,200MW PSP will have 3.5 hours of storage capacity and four reversible units.
The deadline for submitting EoIs is 10 November, with enquiries accepted until 26 October.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20336025/main.jpg -
Arada launches UAE construction arm with Roberts
7 October 2026
Register for MEED’s 14-day trial access
UAE developer Arada has integrated Australian contractor Roberts into the UAE market as part of its wider business strategy.
Arada acquired Roberts in 2025 after entering the Australian market. The tier-one contractor delivers projects in the healthcare, education, commercial, residential, hospitality, industrial, life sciences and defence sectors.
At the time of the acquisition, Arada said it planned to invest about $20m in Roberts. The investment is intended to give the developer greater control over the delivery of its Australian projects and support Roberts’ expansion into markets including the UAE.
Arada has said it could invest up to $100m in Roberts’ expansion into new sectors and markets. The company is targeting $1bn in annual revenue from Roberts by 2028.
Roberts has established a UAE office, with a head office team already in place. Arada said the contractor’s capabilities will support the delivery of its high-rise residential and social infrastructure projects.
The contractor’s first UAE project will be phase two of Arada Central Business District, a commercial development within Aljada in Sharjah. Arada is developing the AED35bn ($9.5bn) mixed-use project.
Roberts is also providing preconstruction services for several Arada projects in Dubai and Sharjah, ahead of starting site work.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20334926/main.jpg