Regional stock market listings near record level
23 December 2024

This report also includes: Gulf debt markets make their mark
The Middle East and North Africa (Mena) region’s capital markets got off to a fairly strong start in 2024, with two sizeable listings on the Saudi Stock Exchange (Tadawul) in January. Broadcaster MBC Group’s listing on 8 January raised $222m, while Middle East Pharmaceutical Industries Company (Avalon Pharma) followed up with a $131m share sale on 24 January.
The year ended with a far bigger bang, however, with several multibillion-dollar listings in the UAE and Oman in the final quarter. Among them, grocery chain Lulu Group International raised $1.7bn on the Abu Dhabi Securities Exchange (ADX) in early November. The following month, food delivery and quick commerce business Talabat Middle East raised $2bn when it launched on the Dubai Financial Market (DFM).
 Between those bookends to the year there were dozens of other initial public offerings (IPOs) on the region’s stock markets. According to data compiled by EY, there were 29 new listings in the opening nine months of the year, the same as in the equivalent period of 2023 and only just behind the 31 IPOs in 2022.
The final quarter of the year has been the busiest. MEED’s analysis points to the tally reaching 49 IPOs as of mid-December, with several more listings still on the cards for the closing weeks of the year. As such, the previous record for the most IPOs in the region in a year – the 51 seen in 2022 – could well be surpassed.
As has been the case for many years, the GCC bourses have been the dominant focus of activity, with Saudi Arabia hosting 13 IPOs on the main Tadawul market and 24 on the smaller Nomu bourse.
The UAE has had a further seven, with four on the ADX and three on the DFM, while the Kuwait and Muscat exchanges have had one apiece.
Beyond the Gulf, activity has been more limited, but some markets that were dormant for several years have reawakened. There have been two IPOs in Egypt – Act Financial and United Bank of Egypt – and one on the Algiers Stock Exchange, where Credit Populaire d’Algerie’s listing in March was the first in eight years.
Fluctuating activity
IPO activity has ebbed and flowed through the year. According to EY, there were 10 IPOs in the first quarter, the same as in the equivalent period the year before, although this did not include the Algiers listing.
Saudi Arabia saw nine listings in Q1 2024, raising a combined $724m, the most significant being Modern Mills, which raised $314m. That was overshadowed by Parkin Company, however, which raised $429m by listing on the DFM.
In the second quarter, a further 14 companies came to market, raising $2.6bn between them. This was slightly up on the 13 IPOs in Q2 2023 and the proceeds were also up 45%.
Of the total, 11 were in Saudi Arabia, with five on the Tadawul and six on the Nomu. The biggest was Dr Soliman Abdul Kader Fakeeh Hospital Company at $764m, followed by Alef Education Consultancy on the ADX at $515m.
Notably, Kuwait Boursa saw its first listing in two years, with Beyout Investment Group coming to the market in June. The only other IPO outside Saudi Arabia was retailer Spinneys, which listed on the DFM, raising $375m.
Activity slowed in the third quarter, with just five new listings, which raised $930m between them. Almost all of this was accounted for by the listing of NMDC Energy on the ADX, which involved a raise of $877m – the largest of the year at the time, although that figure was overtaken several times in the final quarter.
Saudi Arabia saw three more listings on the Nomu market in Q3, raising $27m in total. During this period, Act Financial also made its market debut, becoming the first new listing on Egyptian Exchange (EGX) in two years.
At the end of Q3, EY estimated that a further 11 companies were planning to list on exchanges in the Mena region before the year was out.
Not all of these listings have gone ahead, but a number of major IPOs have been completed, including OQ Exploration & Production on the Muscat Stock Exchange (MSX), which raised $2bn on 28 October. It was followed by the IPOs of hypermarket chain Lulu Group and food delivery operator Talabat over the next two months.
In addition, there have been five more listings on the Tadawul, including Al-Majed Oud Company and Arabian Mills for Food Products Company, and nine more on the Nomu market.
Other deals have been announced but have so far yet to be completed. These included Oman’s OQ Base Industries, which in November announced plans to sell up to 49% of its shares and seek a listing on the MSX by mid-December.
The huge listings in the fourth quarter of 2024 mean that the downward trajectory of 2023 has been turned around, even if the heights of 2022’s fundraisings have not quite been matched.
After the $22bn raised in 2022, the total fell to $10.7bn in 2023. In 2024, the total reached about $12.5bn by 10 December, including $8bn raised in the final quarter.

Diverging indices
The wider market performance of regional bourses has been decidedly mixed in 2024.
There have been a handful of standout performers across the region. The Moroccan All Shares Index (MASI), for example, was up 22.7% between January and the end of November, with Egypt’s EGX 30 Index not far behind at 21.5%, according to data compiled by Kuwait’s Kamco Invest.
In the Gulf region, Dubai’s DFM General Index was up 19.4% over the same period, while Tunisia’s TunIndex also saw a creditable 12.7% gain.
In contrast, Riyadh’s Tadawul All-Share Index (Tasi), the FTSE ADX General Index, Qatar’s QE20 Index and Jordan’s ASE Index all saw their values fall in the first 11 months, with drops of between 1% and 4%.
Other major bourses saw more limited gains, with the Kuwait All Share Index posting a rise of 6.3%, while the Bahrain All Share Index was up 3.1% and Oman’s MGX 30 Index gained just 1.1%.
It is hard to see any clear pattern in these results. To date, five regional bourses have posted a better overall performance in 2024, compared to 2023, but six are faring worse.
This fits in with the mixed performances seen on the global level. The MSCI World Index gained more than 20% in the first 11 months of the year, helped by a strong performance in the US, where the S&P 500 rose by 26.5%. In contrast, the MSCI Emerging Markets Index was up just 5.4% over the same period.
The buoyant market for regional IPOs suggests that many companies and investors feel relatively optimistic, however.
A second IPO is due to take place in Algeria before the end of the year, with the listing of Banque de Developpement Local, and more are pencilled in for 2025.
In neighbouring Morocco, irrigation specialist CMGP Group is also aiming for a $110m IPO on the Casablanca Stock Exchange in the near future.
However, Gulf markets are likely to continue to dominate in the near future. At least four more listings are planned in Saudi Arabia in the closing weeks of 2024 and the start of 2025, and many more are sure to follow.
Main image: Food delivery business Talabat raised $2bn with its IPO on the Dubai Financial Market in December. Credit: WAM

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
-
 Contractors prepare bids for Morocco power line
2 November 2026
-
 Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
-
 Gulf ministers insist Hormuz is still essential
2 November 2026
-
 Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
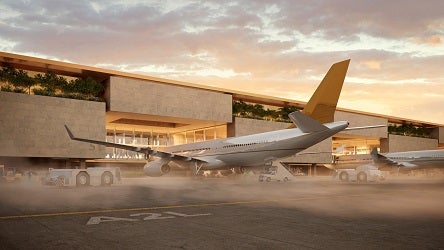
Contractors compete for Riyadh airport Terminal 6 work
2 November 2026
Contractors are preparing bids for the main construction contract for Terminal 6 at King Salman International airport (KSIA) in Riyadh.
MEED understands that the consortiums have been given until January to submit their proposals.
The participating consortiums are:
- Al-Gihaz Holding / TAV Construction / Webuild (local/Turkiye/Italy)
- Modern Building Leaders / Powerchina / Metallurgical Corporation of China (loca/China/China)
- UCC Holding / Consolidated Contractors Company (Qatar/Greece)
Last month, MEED exclusively reported that contractor teams have completed the early contractor involvement phase of the project.
Under the completed phase, the shortlisted teams submitted detailed construction methodologies and technical design proposals.
King Salman International Airport Development Company (KSIADC) is a subsidiary of Saudi sovereign wealth vehicle the Public Investment Fund.
Terminal 6 is planned to boost the airport’s annual capacity by 40 million passengers. KSIADC aims to complete the terminal ahead of Expo 2030 Riyadh.
In May 2025, MEED reported that US-based Bechtel had been appointed as delivery partner for the passenger terminals at KSIA.
UK-based Foster + Partners designed the masterplan, including the terminals, six parallel runways and a multi-asset real estate district.
US-based engineering firm Jacobs is providing specialist consultancy services for the masterplan and runway design, while UK-headquartered Mace is acting as delivery partner for the broader development. Local firm Nera secured the airspace design consultancy contract.
The KSIA project covers about 57 square kilometres (sq km) and incorporates the existing terminals at King Khalid International airport. The scheme will feature 12 sq km of airport support facilities, residential and recreational zones, retail assets and logistics parks.
The development is targeted to handle up to 120 million passengers a year by 2030 and 185 million passengers by 2050, in addition to an annual cargo throughput of 3.5 million tonnes by 2050.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21087339/main.jpg -
Contractors prepare bids for Morocco power line
2 November 2026
Contractors are preparing bids for a 160-kilometre (km), 400kV transmission line linking Guercif and Fes East in Morocco, following a site visit on 1 October.
The project is being developed by the Office National de l'Electricite et de l'Eau Potable (Onee) to connect the Saka solar photovoltaic power plant to the national electricity grid.
According to sources, at least eight contractors attended the site visit last month, including:
- Butec (Lebanon)
- CEEC Northeast Electric No.2 (China)
- Cegelec (France)
- EPME Electric (Morocco)
- Hideleco (Egypt)
- Kec International (India)
- PowerChina (China)
- Transrail (India)
The project comprises two lots. The first involves a 90km transmission line between Guercif and Taza, while the second covers a 70km section between Taza and Fes East.
The scope of work includes the construction of tower foundations, installation of transmission supports and conductors, and associated high-voltage equipment. It also includes optical fibre cables for communications and monitoring, access roads and other supporting infrastructure.
The tender was issued in September with bids originally due by 21 October. The deadline has now been extended to 25 November.
The project is part of a wider programme by Onee to expand Morocco's electricity transmission network and accommodate additional renewable energy capacity.
In June, the utility commissioned a 274km, 400kV transmission line linking Chemaia and Mediouna, near Casablanca.
Onee plans to expand its high- and extra-high-voltage transmission network from more than 30,700km to 37,000km by 2030.
In August, it approved a $26.4bn investment programme for the 2026-30 period, covering electricity and drinking water infrastructure.
The programme has allocated about $21.9bn to electricity projects and $4.5bn to drinking water infrastructure, with about 72% of the investment to be financed by the private sector, according to Onee.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083507/main1257.jpg -
Adnoc Onshore allows more time for Bab gas cap well tie-in bids
2 November 2026
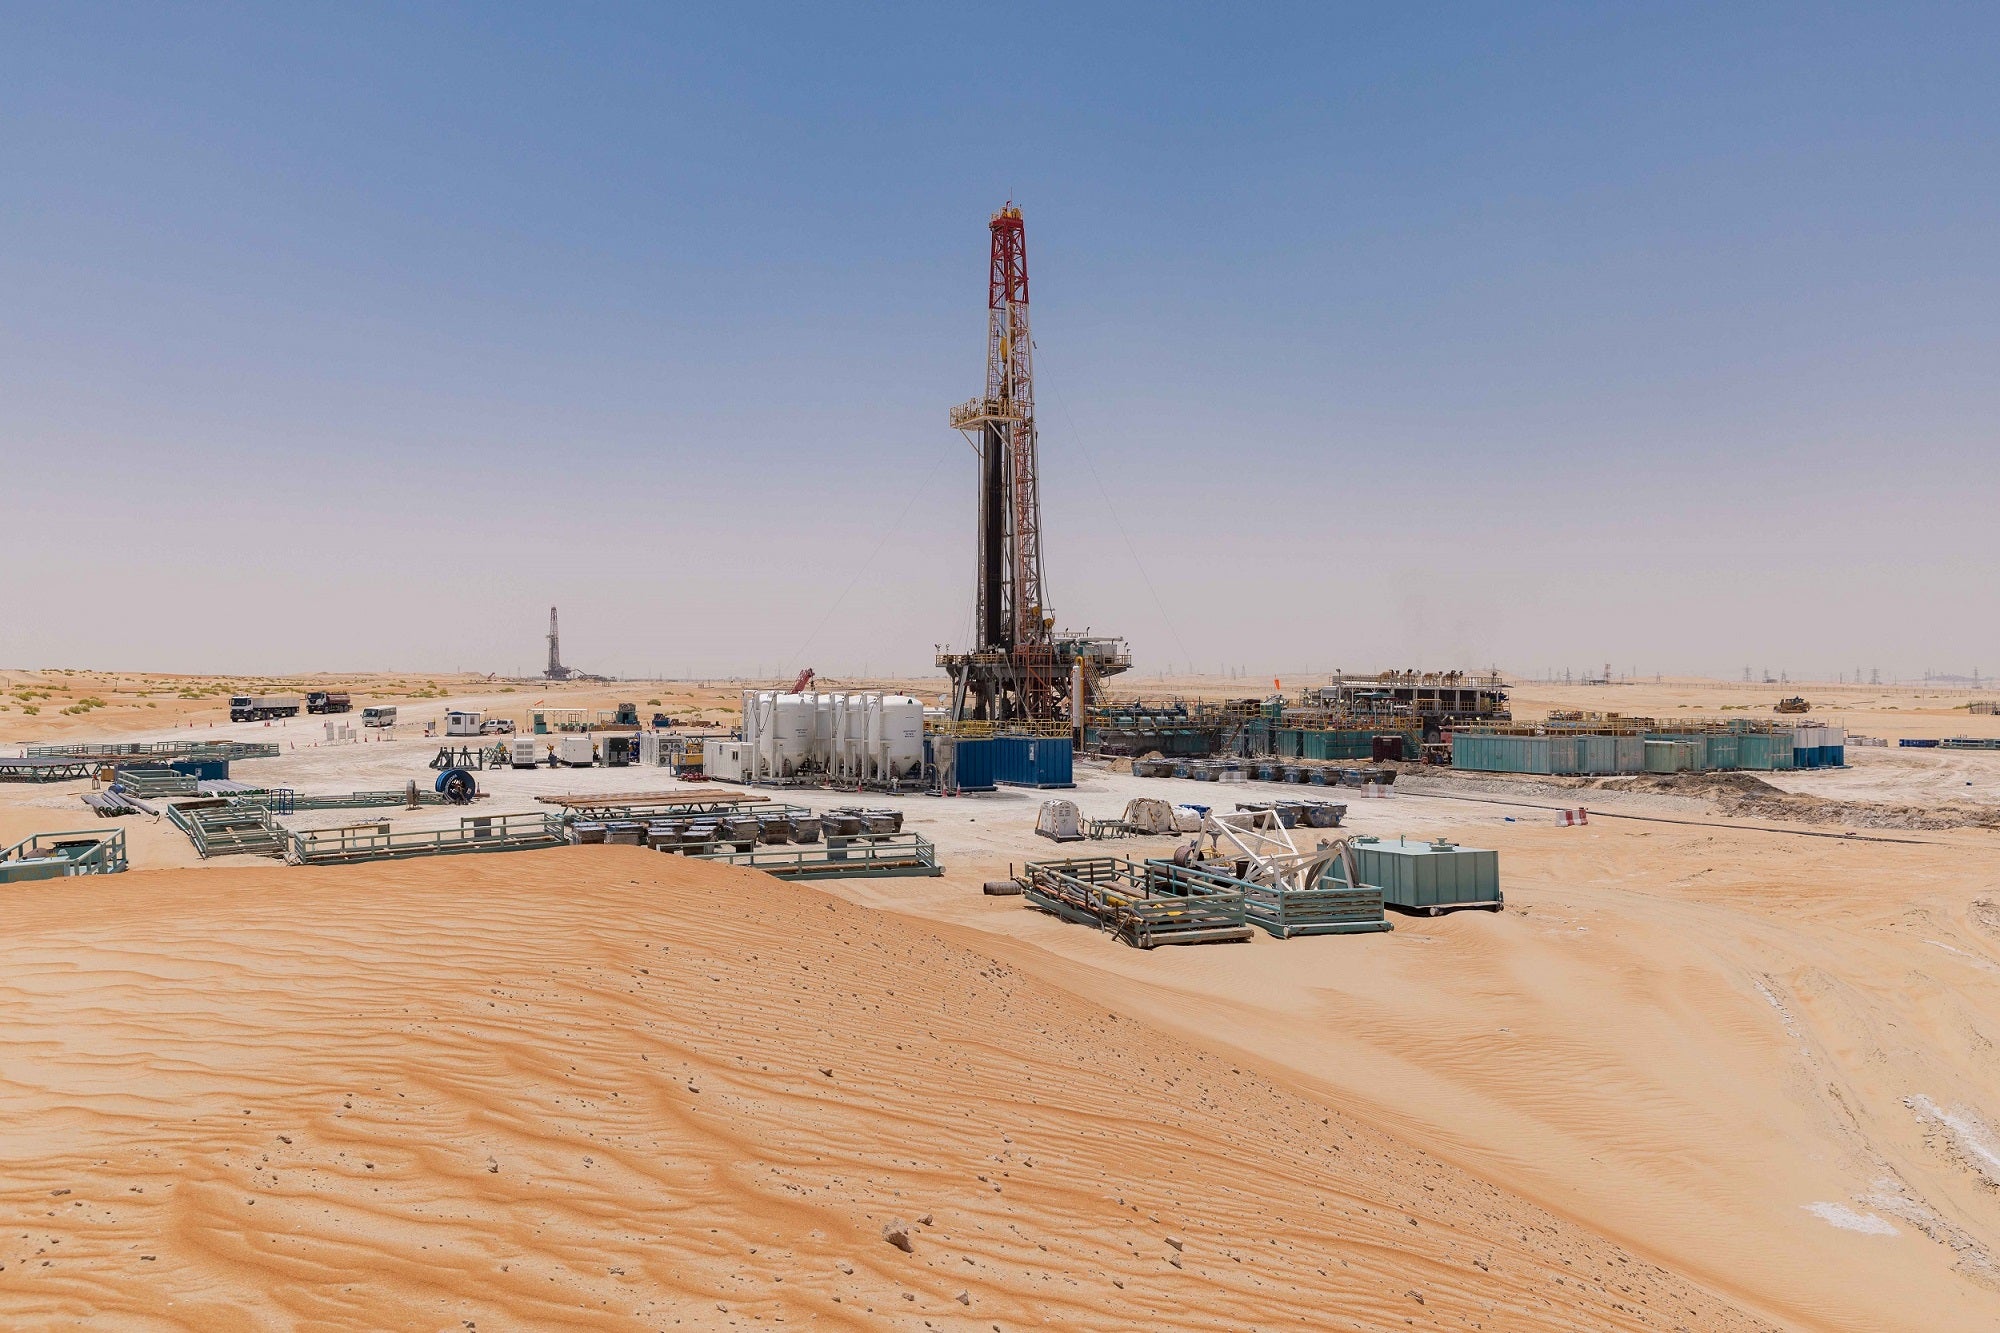
The onshore business of Abu Dhabi National Oil Company (Adnoc Onshore) has allowed contractors more time to prepare proposals for a project to tie in gas-producing and injection wells at the gas cap reservoirs of Abu Dhabi’s onshore Bab field.
The well tie-in scope, estimated to be worth more than $800m, forms part of Adnoc Group’s wider integrated Bab gas cap development programme.
The overall programme is being led and overseen by Adnoc Gas, another Adnoc Group subsidiary. Its central element is the construction of gas-processing infrastructure to handle incremental gas output expected from developing the Bab gas caps.
Adnoc Onshore issued the main tender for engineering, procurement and construction (EPC) works on the project in late September, MEED previously reported.
Contractors have been given until 16 November to submit technical bids for the project, according to sources. The previous deadline was 29 October.
MEED previously reported that Adnoc Onshore issued an expressions of interest (EoI) notice for the Bab gas production and injector well tie-in project on 13 May, with contractors submitting responses by 20 May.
The scope of work on the project covers the following:
- Tie-in of 99 new wells from Bab gas cap reservoirs KH-2, SH-1 and LK-1 (60 gas producers and 39 gas injectors);
- Installation of well gathering structures: 10 gas pads, six well bays and three virtual pads;
- Installation of a gas gathering network and a gas injection network;
- Rerouting of the LK-3 production from the existing trunkline in Remote Manifold Station 3 (RMS-3) to the project’s production trunkline, Bab Gas TL-2;
- Demolition of the existing 10-inch trunkline from RMS-3 to onshore gas development phase one.
In the EoI document, Adnoc Onshore said it intends to award the EPC contract in the last quarter of the year, with a 45-month duration of works.
Bab gas cap project infrastructure
As part of its 2030 upstream production increase goals, Adnoc Group is working to extract gas from four underdeveloped gas cap reservoirs at the Bab onshore field development – Thammama A, Thammama B, Thammama F and Thammama H.
While the Thammama A, B and H reservoirs are estimated to collectively produce 1.45 billion cubic feet a day (cf/d) of gas, output from the Thammama F gas cap is expected to be at a rate of 396 million cf/d.
Existing trains at the Habshan processing complex in Abu Dhabi will be unable to handle the new gas volumes. Therefore, Adnoc Gas is required to build new facilities to process an additional volume of up to 1.85 billion cf/d of raw gas.
Adnoc Gas is planning to build a gas processing plant in the Bab area, about 170 kilometres from Abu Dhabi, along with associated pipeline networks and other ancillary units, as part of the broader Bab gas cap development project. It has divided the EPC scope of work on the project into four packages:
- EPC package 1 – Main Bab gas cap plant
- EPC package 2 – Early civil works
- EPC package 3 – Pipelines
- EPC package 4 – Non-process area works
Abu Dhabi Securities Exchange-listed Adnoc Gas issued the tender for the main Bab gas cap plant on 25 June and set an initial deadline of 17 July for contractors to submit technical bids. The company then extended the technical bid submission deadline by four months, until 16 November, MEED previously reported.
Following a reshuffle of the consortiums gearing up to bid for the main Bab gas plant EPC package, estimated to be worth more than $6bn, the following teams have formed to compete in the main contract tendering round:
- Larsen & Toubro Energy Hydrocarbon (India) + Petrofac Emirates (UAE)
- Technip Energies (France) + JGC Corporation (Japan) + Sinopec (China)
- Tecnimont (Italy) + China Petroleum Engineering and Construction Corporation (CPECC)
The other three packages of the Bab gas cap project are also in the main contract tendering stages.
Prior to issuing the EoIs for the project packages, Adnoc Gas completed an early engagement process with contractors in September and October last year, as MEED previously reported.
In December last year, Adnoc Gas awarded the front-end engineering and design (feed) works for the development project to Australia-based consultancy Worley. The feed contract has a duration of more than 1.2 million man-hours, making it the largest-ever engineering job awarded by Adnoc Gas.
Bab Gas Cap concession
In addition to Adnoc Gas overseeing the main EPC tendering exercise for the gas processing plant, Abu Dhabi’s Supreme Council for Financial and Economic Affairs (SCFEA) awarded concession agreements in June for the development and production of the Bab gas cap reserve.
Adnoc will hold the majority 60% participating interest in the concession. The remaining stakes will be held by France’s TotalEnergies (10%), the UK’s BP (10%), China National Petroleum Corporation International (8%), Japan Oil Development Company Onshore (5%), China ZhenHua Oil (4%) and Korea GS E&P (3%).
According to the SCFEA, the Bab gas cap development and production concession represents the largest gas cap development project of its kind globally, the Abu Dhabi Media Office said in a report.
A gas cap refers to the free natural gas that sits above an underlying oil reservoir – in this case, the Bab onshore oil field in Abu Dhabi.
The project, operated by Adnoc Onshore, is expected to have a production capacity of approximately 1.5 billion cf/d of natural gas, equivalent to about 15% of Adnoc Gas’ total operational gas processing capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21083343/main.jpg -
Gulf ministers insist Hormuz is still essential
2 November 2026
Register for MEED’s 14-day trial access
Senior Gulf officials have rejected suggestions that new pipelines and rail links will allow the region to do without the Strait of Hormuz, arguing that the waterway will remain essential to the GCC and the global economy.
Speaking at the Gateway Gulf investment forum in Manama on 1 November, GCC secretary-general Jasem Mohamed Albudaiwi said keeping the strait open is the responsibility of the international community, not of any one country or group of partners. "We hear some voices that maybe we should seek alternatives to Hormuz," he said. "Fine, we will get the pipelines. We will get the GCC railway. But that doesn't mean Hormuz is nobody's business."
Albudaiwi called for the strait to remain open in line with international law, including the 1982 UN Convention on the Law of the Sea.
Shipping through the strait has been severely restricted since the US and Israel launched strikes on Iran on 28 February and Iran retaliated with attacks on GCC states and commercial vessels.
Bahrain's Finance & National Economy Minister, Sheikh Salman Bin Khalifa Al-Khalifa, said building redundancy makes sense, but treating the strait as dispensable does not. He said the waterway carries 30% of global liquefied natural gas (LNG) exports, 20% of aluminium exports and 30% of fertiliser exports. "Any thinking about the alternative of Hormuz, as in we won't need it, is illogical, because we will need it for the world economy," he said.
UAE Economy & Tourism Minister Abdulla Bin Touq Al-Marri said that "Hormuz matters, and Hormuz will keep mattering", adding that an economy dependent on a single trade route is exposed if that route closes.
Sheikh Salman said the crisis has compressed years of GCC customs negotiations into weeks. During the conflict, containers cleared at Jeddah with final destinations in Bahrain or Kuwait moved on without further checks, and the same applied to cargo routed through Salalah and Fujairah, he said. GCC ministers have since agreed to make these emergency measures permanent.
He also cited Gulf Air operating out of Saudi airports for more than 40 days without a written agreement, and a $5bn swap between the UAE and Bahraini central banks to stabilise currencies.
Bin Touq said the bloc should use 2027 and 2028 to push through reforms, including removing remaining customs barriers between member states.
Albudaiwi said GCC leaders meeting in Jeddah on 28 April had tasked the secretariat with advancing water connectivity, expanding the GCC electricity grid, planning new logistics infrastructure including ports, accelerating the GCC railway and enhancing oil and gas pipeline links.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21080732/main4958.jpg -
Bahrain’s Gateway Gulf brings $20bn of deals
2 November 2026
More than 110 announcements worth over $20bn will be made at the Gateway Gulf Investment Forum in Bahrain, according to the country's finance minister.
"Over the next two days at Gateway Gulf, more than 110 announcements worth over $20bn will be made," Sheikh Salman Bin Khalifa Al-Khalifa, Finance & National Economy Minister, said at the opening of the forum's fourth edition on 1 November in Bahrain.
He said the announcements will cover new partnerships, investments, projects and jobs. Sheikh Salman addressed an audience that included Bahrain's Crown Prince and Prime Minister, Prince Salman Bin Hamad Al-Khalifa.
The minister said the region's economies have been "tested as never before" since the previous edition of the forum a year earlier.
"In the face of unprecedented attacks, we did not waver," he said. He added that Bahrain has chosen to work more closely with its allies and partners to defend what it has built.
Sheikh Salman said the Gulf economy has grown to $2.4tn in GDP. Non-oil sectors account for more than 86% of Bahrain's GDP and more than 77% across the Gulf, he said.
He said Gulf banks hold more than $4tn in assets, while the region's sovereign wealth funds manage more than $5tn of investments. "These numbers describe a region that has chosen to build a more stable, a more prosperous future for its people," he said. "Bahrain is the gateway to that region."
The minister said Bahrain is focusing on regulation, infrastructure and people to attract investment.
He said the country has developed a regulatory framework over several decades that is "clear, modern and fast", allowing investors to commit with confidence.
On infrastructure, he highlighted logistics, connectivity, digital networks and industrial land as areas where Bahrain is building the foundations for businesses to expand. He also named finance, logistics, tourism, manufacturing, technology and telecommunications, and oil and gas as the sectors into which he expects domestic, regional and international capital to flow.
He said the investments will create jobs for young graduates and support the growth of family businesses.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21080593/main2015.jpg