Regional downstream sector prepares for consolidation
30 December 2024

The Middle East and North Africa (Mena) region’s midstream and downstream oil, gas and petrochemicals sectors together had one of their best years on record in 2024, with state-owned companies and private players collectively spending close to $38bn on projects.
 Saudi Arabia emerged as the biggest regional spender on midstream and downstream projects. To address incremental volumes of gas entering the grid as Saudi Aramco increases its conventional and unconventional gas production, the state enterprise has spent more than $17bn on gas processing and transportation projects this year.
In April 2024, Aramco awarded $7.7bn in engineering, procurement and construction (EPC) contracts for a project to expand the Fadhili gas plant in the Eastern Province of Saudi Arabia. The project is expected to increase the plant’s processing capacity from 2.5 billion cubic feet a day (cf/d) to up to 4 billion cf/d.
On 30 June, Aramco awarded 15 lump-sum turnkey contracts for the third expansion phase of the Master Gas System (MGS-3), worth $8.8bn. Then, in August, the company awarded contracts for the remaining two packages of the MGS-3 project, which were worth $1bn.
Saudi Aramco divided EPC works on the MGS-3 project into 17 packages. The first two packages involve upgrading existing gas compression systems and installing new gas compressors. The 15 other packages relate to laying gas transport pipelines at various locations in the kingdom.
The Master Gas System expansion will increase the size of the network and raise its total capacity by an additional 3.15 billion cf/d by 2028 with the installation of about 4,000 kilometres
of pipelines and 17 new gas compression trains.
 Abu Dhabi capex
The UAE has been the second-largest spender on midstream, downstream and chemicals projects in 2024, led by investments from Abu Dhabi National Oil Company (Adnoc) and Taziz – its 60:40 joint venture with industrial holding entity ADQ.
Adnoc’s biggest capital expenditure (capex) was in the form of a $5.5bn EPC contract that it awarded to a consortium of France’s Technip Energies, Japan-based JGC Corporation and Abu Dhabi-owned NMDC Energy to develop a greenfield liquefied natural gas (LNG) terminal complex in Ruwais.
The upcoming Ruwais LNG export terminal will have the capacity to produce about 9.6 million tonnes a year (t/y) of LNG from two processing trains, each of which has a capacity of 4.8 million t/y. When the project is commissioned, Adnoc’s LNG production capacity will more than double to about 15 million t/y.
Adnoc Group subsidiary Adnoc Gas has also advanced a project to expand its sales gas pipeline network across the UAE, which is known as Estidama. The Abu Dhabi-listed company has awarded two EPC packages of the project this year, which together were worth more than $500m.
Adnoc Gas is expected to award the contract for another Estidama package before the end of 2024 that covers the construction of a pipeline that will provide feedstock from its Habshan gas processing plant to the upcoming Ruwais LNG complex.
Taziz, meanwhile, awarded three EPC contracts totalling $2bn for infrastructure works at the industrial chemicals zone that it is developing in Ruwais Industrial City.
Spending to plateau
Having reached a peak in spending, and with EPC contracts awarded for strategic midstream, downstream and chemicals projects in 2024, the Mena region is set to enter a period of more pragmatic project spending in 2025. However, this does not imply that a slump in project capex is likely, and the region could once again equal the level of contract awards made in 2024.
One of the largest projects that may be awarded in 2025 is the main contract for the North Field West LNG project – the third phase of QatarEnergy’s LNG expansion programme.
The North Field West project will have an LNG production capacity of 16 million t/y, which is expected to be achieved through two 8 million t/y LNG processing trains, based on the two earlier phases of QatarEnergy’s LNG expansion programme.
 The new project will draw feedstock for LNG production from the western zone of Qatar’s North Field offshore
gas reserve.
Taziz is also on course to make progress with the second expansion phase of its derivatives complex, which will more than double the number of chemicals produced at the industrial hub. The expansion’s centrepiece will be a large-scale steam cracker that will supply feedstocks to the several new chemical plants earmarked for third-party investments.
In Saudi Arabia, there has been speculation that Aramco may be revisiting its investment strategy and execution approach for its strategic liquids-to-chemicals programme.
The aim of the programme is to derive greater economic value from every barrel of crude produced in the kingdom by converting 4 million barrels a day (b/d) of Aramco’s oil production into high-value petrochemicals and chemicals feedstocks by 2030.
Aramco has divided its liquids-to-chemicals programme into four main projects. It took a major step forward
in September 2023 by selecting US firm KBR, France’s Technip Energies, UK-based Wood Group and Australia- headquartered Worley to provide project management consultancy services for the four different segments of the scheme.
Progress on a programme as big as the liquids-to-chemicals scheme is expected to be measured and laboured.
While day-to-day the advancement might appear sluggish, Amin Nasser, Aramco’s president and CEO, said earlier in 2024 that the Saudi energy giant is on track to achieve its crude oil-to-chemicals conversion goal by 2030.
“We are on track to achieve our target of 4 million b/d liquids-to-chemicals [conversion capacity] by 2030,” he said.
Meanwhile, Kuwait is in a similar situation with its planned Al-Zour integrated complex upgrade programme (Zicup), which has suffered significant delays in recent years. However, state-owned Kuwait Integrated Petroleum Industries Company (Kipic), the project’s operator, recently appointed a team to look into the logistics of developing a benzine pipeline as part of the estimated $10bn Zicup scheme.
Although this may be a small step, it does indicate that Kuwait remains determined to achieve its ambition of developing a large-scale petrochemicals facility, which, when integrated with its $16bn Al-Zour refinery, could become one of the biggest integrated refining and petrochemicals complexes in the Mena region.


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Houthi escalation targets Saudi airports
12 October 2026
-
 Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
-
 JGC yet to return evacuated workers to Basra refinery
12 October 2026
-
 Contractors prepare Jordan stadium prequalification
12 October 2026
-
 Abu Dhabi plans Mussafah road upgrades
12 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Houthi escalation targets Saudi airports
12 October 2026
Yemen’s Houthis have placed Saudi Arabia’s civil aviation infrastructure at the centre of their campaign against the kingdom. Two strikes on King Khalid International airport in Riyadh over the weekend killed 13 people and injured 320.
The deadlier attack hit a passenger terminal on the afternoon of 10 October. The General Authority of Civil Aviation (Gaca) said it killed 12 people, including four Saudi citizens, and injured 309. Airport operations were suspended pending a damage assessment.
A second strike hit Terminal 4 on the afternoon of 11 October, sparking a fire that killed a Pakistani resident and injured 11 others, according to Gaca. The Saudi-led coalition reported intercepting a cruise missile near the airport that afternoon. Gaca also reported an attack on King Fahd International airport in Dammam that evening, following a coalition report of a projectile falling near the facility the previous night.
The weekend strikes followed attacks on Abha International airport on 6 October and on King Khalid International airport on 7 and 8 October, the last of which included a strike on a Saudia aircraft. Gaca figures put the toll from the week’s attacks on Saudi airports at 19 dead and more than 350 injured.
The Houthis said they would continue operations inside the kingdom and that all Saudi airports were potential targets, with the exception of those serving the holy cities. The group says it is acting in response to Riyadh’s support for Yemeni government forces and a Saudi air strike on Sanaa airport. It has also claimed attacks on Saudi oil facilities, which Saudi authorities have not confirmed.
Aviation exposure
The attacks strike a sector central to the kingdom’s diversification plans. King Khalid International airport’s existing terminals are to be absorbed into King Salman International airport (KSIA), a 57-square-kilometre development with six parallel runways targeting a capacity of 120 million passengers by 2030 and 185 million by 2050.
Procurement on KSIA has gathered pace this year. In July, a joint venture of China Civil Engineering Construction Corporation and Dammam-based Mofarreh AlHarbi & Partners won an estimated SR800m ($213m) contract for enabling and substructure works on Terminal 6, which will add capacity for 40 million passengers. Turkish contractor IC Ictas and Saudi Arabia’s Al-Rashid Trading & Contracting recently secured a SR800m ($213m) contract for the airport’s Private Aviation Terminal.
Government-owned Saudi Royal Aviation set 8 October as the bid deadline for an estimated SR3bn ($800m) contract to build an aviation complex within the KSIA masterplan, the same day the Houthis struck King Khalid International airport and a Saudia aircraft.
Airlines have already adjusted. Flydubai cancelled flights to Riyadh and Yanbu up to 10 October and to Abha up to 11 October, and Etihad Airways reported extended delays on its Abu Dhabi to Riyadh service after the airport closed on 8 October. The UK Foreign Office has advised against all travel to areas within 10km of the Yemeni border.
Market reaction
The Saudi stock market’s response has been muted so far. The Tadawul main index fell 15.54 points to close at 10,360.74 on 11 October, the first trading session after the Saturday attack, with turnover of SR2.6bn ($693m). The session closed before the second strike on King Khalid International airport and the attack on Dammam, and Monday’s trading will be the first to reflect the full weekend.
The weekend also brought a separate maritime incident. UK Maritime Trade Operations said an oil tanker was struck by an unidentified projectile in the Strait of Hormuz on 11 October, with its crew reported safe.
Diplomatic response
The coalition described the 10 October attack as a war crime and said it would respond decisively. It said on 10 October that it had destroyed 136 military targets in Houthi-controlled areas and was working to dismantle the group’s ballistic missile network.
Egypt, Pakistan and Turkiye joined Saudi Arabia in an R4 group statement condemning the attacks and supporting measures taken by the kingdom in response. The Arab League also voiced its support for Saudi Arabia. On 11 October, Iran’s foreign minister spoke by telephone with his Saudi counterpart, Prince Faisal Bin Farhan, to discuss the escalation. The US and UK have also signalled the possibility of further support for the kingdom.
The escalation comes against the backdrop of the regional conflict, which has drawn Saudi Arabia into a renewed Yemen front after several years of relative calm following the 2022 ceasefire. The extent of the damage at King Khalid International airport, which Gaca is still assessing, and the speed at which international carriers resume full schedules will determine how far the attacks disrupt the kingdom’s aviation programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20505600/main.gif -
Egypt and Saudi Arabia sign oil and gas deal
12 October 2026
Egypt and Saudi Arabia have signed an agreement to strengthen cooperation in the oil, natural gas and petrochemicals sectors, according to a statement from Egypt’s Ministry of Petroleum & Mineral Resources.
The memorandum of understanding (MoU) was signed in Riyadh by Karim Badawi, Egypt’s minister of petroleum and mineral resources, and Abdulaziz Bin Salman, Saudi Arabia’s minister of energy.
Under the agreement, both sides will enhance cooperation in trading, transporting, storing and distributing crude oil, petroleum products and natural gas.
They will also expand cooperation on developing the infrastructure and logistics services that support these activities.
In its statement, Egypt’s Ministry of Petroleum & Mineral Resources said: “These efforts will contribute to improving energy market efficiency, enhancing the resilience and reliability of supply chains, and strengthening energy security.”
The MoU also provides for expanded cooperation in exchanging expertise and best practices in operating and developing fuel stations, as well as in transporting and tracking petroleum products and liquefied petroleum gas cylinders.
Additionally, the agreement seeks to explore investment opportunities in joint projects and promote exports.
The latest agreement comes as Egypt becomes an increasingly important export route for Saudi Arabia.
Due to disruptions and security risks affecting shipments through the Strait of Hormuz, Saudi Arabia has been redirecting crude exports via its East-West Pipeline to Yanbu on the Red Sea.
Meanwhile, the Bab El-Mandeb Strait, at the southern end of the Red Sea, has also become a security concern due to military activity in Yemen. Egypt offers an alternative route through the Sumed pipeline, which runs from Ain Sokhna on the Red Sea to Sidi Kerir on the Mediterranean.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20503239/main.jpeg -
JGC yet to return evacuated workers to Basra refinery
12 October 2026
Japan’s JGC has yet to bring evacuated workers back to the Basra refinery project in Iraq, according to industry sources.
JGC evacuated its personnel from the site in the southern oil hub of Basra following the start of the regional conflict on 28 February, when the US and Israel attacked Iran.
The evacuation halted work on the project, which was in its final construction stage.
On 14 August 2026, Iraq’s Ministry of Oil announced that it had signed an agreement with JGC to resume work on the fluid catalytic cracking (FCC) project at Basra refinery.
One source said: “Even though the agreement to bring the evacuated workers back was signed about two months ago, there is still no sign of the evacuated workers on the project site.
“It is possible that they will return soon, but it is hard to tell what will happen next in the current security environment.”
Earlier this month, Iraq’s Ministry of Oil said it met with Japanese officials to discuss plans to commission the FCC unit under the Basra refinery upgrade project.
The statement did not say when the evacuated JGC workers would return to the project site.
Strategic project
Iraq’s state-owned South Refineries Company (SRC) sent JGC notice of the main contract award for the FCC package of the Basra refinery upgrade project in August 2020.
JGC was awarded the contract in consortium with South Korea’s Hyundai E&C.
The official contract signing ceremony was held in Baghdad on 1 October 2020.
The contract awarded to JGC, which uses the engineering, procurement, construction and commissioning model, was worth $3.78bn.
The FCC package is part of a broader project to upgrade the Basra refinery.
The project site is located about 12 kilometres east of Iraq’s southern city of Basra.
The wider upgrade project involves installing new facilities on land adjacent to the existing Basra refinery, including a vacuum distillation unit and a diesel desulphurisation unit.
In April 2021, France’s Axens won a contract in Iraq to provide four process technologies to SRC for the Basra refinery upgrade project.
The technologies that SRC selected are:
- Diesel hydrotreatment unit (Prime-D)
- Vacuum gasoil (VGO) hydrotreating unit
- VGO fluid catalytic cracker unit
- Oligomerisation unit (polynaphtha)
In addition, Axens is providing catalysts and adsorbents, proprietary equipment, training and technical services.
MEED’s latest report on Iraq includes:
> COMMENT: Iraq’s reform window narrows
> GOVERNMENT: Al-Zaidi takes Iraq’s premiership under US shadow
> BANKING: Financial challenge tests Iraq’s resolve
> ECONOMY: Iraq enters era of resilience, reform and rising risks
> OIL & GAS: Iraqi oil and gas sector in crisis
> POWER & WATER: Focus shifts to delivery of Iraq utilities expansion
> CONSTRUCTION: Momentum builds in Iraq’s post-war construction sectorTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20503212/main.png -
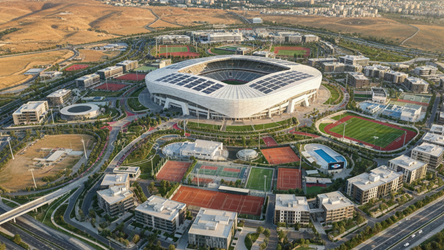
Contractors prepare Jordan stadium prequalification
12 October 2026
Contractors are preparing to submit prequalification statements on 14 October for a contract to build Jordan’s Al-Hussein Bin Abdullah II International Stadium, located east of the capital, Amman.
The project is part of the first phase of the Amra City development masterplan and is being implemented by Jordan Cities & Facilities Development Company, a Jordan Investment Fund-owned company.
Main works are expected to begin early next year, with the stadium slated for completion in 2029.
The project will cover about 1 million square metres, and the stadium will seat 50,000 spectators.
The stadium is being built within the Amra City development, which is located about 40 kilometres (km) from downtown Amman and 35km from Zarqa and Queen Alia International airport.
MEED reported that preliminary excavation and site preparation began in June.
The project forms part of Jordan’s Economic Modernisation Vision (EMV) 2023-25.
The EMV – Amman’s flagship reform programme – aims to increase real income per capita by an average of 3% annually, create 1 million jobs and more than double the country’s GDP over the next decade.
The strategy envisages a leading role for the private sector, which is expected to account for 73% of the estimated $58.8bn investment required.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20501232/main.png -
Abu Dhabi plans Mussafah road upgrades
12 October 2026
Abu Dhabi’s Department of Municipalities and Transport (DMT) has announced plans to upgrade roads in Mussafah, improving links between the industrial area, Mohamed Bin Zayed City and Zayed City.
The scheme covers about 13 kilometres of roads on the E30 and 8th Street. It aims to reduce congestion, improve road safety and cut journey times.
The works include a new three-lane highway in each direction along 8th Street, with parallel three-lane service roads on both sides providing access to local businesses and facilities.
The upgraded corridor is expected to accommodate up to 4,000 vehicles an hour.
Other works include upgrades to four E30 interchanges, improved links to 8th Street and the E20, and modifications to nine junctions.
The DMT also plans to build two bridges connecting Mussafah and Mohamed Bin Zayed City, along with a pedestrian bridge.
Abu Dhabi is planning major investments to upgrade its road network across the emirate.
Last week, it disclosed plans for a major new transport corridor in the capital, comprising a 37km coastal route linking Al-Hudayriyat Island with the E11 at Al-Nouf.
It is planned to have three lanes in each direction and will include a tunnel, about 7km of marine bridges and about 4km of causeways.
The scheme will provide a direct connection between Al-Dhafra, Al-Hudayriyat Island and Abu Dhabi Island via Halat Al-Bahrani, Al-Futaisi and Al-Aryam islands.
READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDFIndustry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20501218/main.jpg