Region to continue robust spending on oil and gas
29 December 2024

The upstream oil and gas industry in the Middle East and North Africa (Mena) region recorded more than $53bn of capital expenditure (capex) on oil and gas production projects in 2023.
 It was forecast that the sector might never repeat that level of spending on engineering, procurement and construction (EPC) contracts, especially with hydrocarbons producers striving to achieve their net-zero carbon emissions goals and broader sustainability commitments.
Abu Dhabi National Oil Company (Adnoc) led capex on Mena production projects in 2023, largely due to its $17bn spending on the Hail and Ghasha offshore sour gas development project.
Saudi Aramco was the second-largest spender in the region in 2023, on the back of the estimated $10bn-worth of EPC contracts it awarded for the second expansion phase of its Jafurah unconventional gas development. It also maintained spending on offshore field upgrade works, awarding about $5.3bn-worth of engineering, procurement, construction and installation (EPCI) contracts.
Yet upstream project spending in 2024 year-to-date has surpassed 2023’s level, with Mena hydrocarbons producers collectively spending more than $58bn on oil and gas production capacity maintenance and expansion projects.
 Record year
Iran emerged as the largest spender in the Mena upstream sector in 2024, with the country’s capex exceeding $22bn. State-owned Pars Oil & Gas Company spent $20bn on EPC contracts in March, on a project to boost gas output capacity at the South Pars field.
Iran shares the South Pars field with Qatar, where it is known as North Field. The natural gas reserve in the Gulf’s waters is estimated to hold 1,800 trillion cubic feet of gas and 50 billion barrels of condensates.
Pars Oil & Gas Company aims to produce 90 trillion cubic feet of gas and 2 billion barrels of condensates from the latest expansion phase of the South Pars field development. The company expects to generate $900bn in total revenues from the expansion project.
Qatar was the second-largest spender in the region in 2024, with state enterprise QatarEnergy advancing its North Field production sustainability (NFPS) project, which aims to support its liquefied natural gas (LNG) expansion programme with gas feedstock.
QatarEnergy LNG, a subsidiary of QatarEnergy, awarded Italian contractor Saipem an estimated $4bn EPCI contract in September as part of the second phase of its NFPS project.
Saipem was awarded two packages, the scope of which encompasses EPCI work on a total of six platforms, approximately 100 kilometres (km) of corrosion resistance alloy rigid subsea pipelines of 28-inches and 24-inches diameter, 100km of subsea composite cables, 150km of fibre optic cables and several other subsea units.
Separately, in January, Qatar’s North Oil Company awarded $6bn-worth of contracts for four engineering, procurement, construction, installation and commissioning packages on a project to increase oil production from its Al-Shaheen offshore oil field by about 100,000 barrels a day (b/d).
The project, known as Ruya, is the third capacity-expansion phase of the Al-Shaheen oil field, which has a production potential of 300,000 b/d at present. North Oil Company – a joint venture of QatarEnergy (70%) and France’s TotalEnergies (30%), which has been the operator of Al-Shaheen since July 2017 – aims to increase the field’s output through the Ruya project.
 Saudi offshore spending
In late January 2024, the Saudi Energy Ministry directed Aramco to abandon its campaign to expand its oil production spare capacity from 12 million b/d to 13 million b/d by 2027. As a consequence, Aramco cancelled the tendering process for at least 15 tenders involving the EPCI of structures at offshore oil and gas fields.
Since that decision, however, Aramco has gone the other way, spending an estimated $4.5bn in 2024 on offshore EPCI contracts, known in the Aramco ecosystem as CRPOs.
Saipem has been the biggest beneficiary of Aramco’s offshore spending, winning all of the CRPOs awarded in 2024. In early May, Aramco awarded the contractor CRPO 143, which involves replacing an oil line between the Berri and Manifa oil fields in the kingdom’s Gulf waters.
Aramco then awarded Saipem the contract for CRPO 138, which involves laying a trunkline at the Abu Safah offshore field. The contract is estimated to be worth $500m.
The firm then scooped three major CRPOs in August, starting with CRPOs 132 and 139, the combined value of which is estimated to be about $1bn. In early September, Saipem began work on the two contracts, which involve the EPCI of structures to upgrade the Marjan, Zuluf and Safaniya offshore field developments.
Just days later, Aramco awarded Saipem CRPO 127, a $2bn contract that involves EPCI of topsides and jackets for wellhead platforms, a tie-in platform jacket and topside, rigid flowlines, submarine composite cables and fibre optic cables at the Marjan oil and gas field.
 Jafurah development
Aramco has also made swift progress in 2024 on successive expansion phases of its programme to produce and process gas from the Jafurah unconventional development in Saudi Arabia. Spending on the Jafurah expansion projects, along with offshore contracts, helped to make the kingdom the third-biggest upstream spender in the Mena region.
Aramco awarded contracts on 30 June for the Jafurah second expansion phase, which aims to raise processing potential to up to 2 billion cubic feet a day (cf/d) of raw gas. Aramco awarded 16 contracts, worth about $12.4bn, for EPC works and drilling services for the second expansion phase.
Within weeks of those awards, a consortium of Spanish contractor Tecnicas Reunidas and China’s Sinopec Group announced that it had been selected by Aramco to carry out EPC works on the third expansion phase at Jafurah, worth $2.24bn. The EPC scope mainly covers building three gas compression plants, each capable of processing 200 million cf/d. Aramco officially awarded the contract to the Tecnicas Reunidas/Sinopec consortium in late September.

Capex to hold steady
While the Mena upstream oil and gas industry may not be able to match its 2024 level of project capex in 2025, the sector is expected to maintain a robust level of spending, especially with national energy companies striving to achieve their strategic long-term oil and gas production capacity goals before the end of the decade.
Data from regional projects tracker MEED Projects suggests that the Mena upstream sector could invest about $40bn on projects in 2025, with gas output expansion schemes predicted to dominate spending.
In line with its target to increase gas production by 60% by 2030, with 2021 as its baseline, Aramco is on course to further advance its Jafurah unconventional gas production programme. It issued the main EPC tender for the fourth expansion phase of the programme in July, within days of selecting the main contractors for the third phase.
 Contractors are preparing bids for the project, the scope of which is similar to that of the third expansion phase, and which is therefore understood to be valued at $2.5bn.
Saudi Arabia’s spending on offshore brownfield and greenfield EPCI contracts is set to remain high, with the tendering process under way for eight more Aramco CRPOs.
Four tenders were issued in August for CRPOs 149, 150, 152 and 153, which cover the EPCI works on the Arabiyah, Hasbah and Marjan offshore oil field developments. Of the four CRPOs, contractors in Saudi Aramco’s Long-Term Agreement (LTA) pool have submitted bids for 149, 152 and 153.
Separately, LTA contractors are also preparing bids for four tenders worth a total of $4bn, which will further expand the Zuluf offshore field development.
Meanwhile, Iran is expected to give shape to its plan for gas extraction from its North Pars field, along with raising output from its onshore and offshore oil fields. Increasing production is vital for Tehran in order to maintain steady volumes of exports to earn vital revenue for its economy, which has been crippled by years of international sanctions.
Pars Oil & Gas Company is estimated to have allocated $15bn to the North Pars gas field development project. However, with the project being in the study phase, and with Iran’s cash-strapped government barely able to provide support to its population, the scheme could see little to no progress in 2025.
In the UAE, with the deadline approaching for Adnoc’s target of raising crude output capacity to 5 million b/d by 2027, it is anticipated that the company will funnel billions of dollars into increasing the production potential of its onshore and offshore oil fields.
Adnoc Group subsidiary Adnoc Offshore is evaluating bids for three packages of a multibillion-dollar project to boost oil production at the Lower Zakum offshore hydrocarbons concession in Abu Dhabi. The goal of the first phase of the Lower Zakum long-term development plan is to raise the asset’s output capacity to 520,000 b/d by 2027 and maintain that level until 2034.
Adnoc Offshore has also started the tendering exercise for front-end engineering and design work on the second expansion phase of the Umm Shaif offshore oil field.
Another Adnoc Group subsidiary, Adnoc Onshore, has made a significant capex investment in growing crude output from its main Bab, Northeast Bab, Bu Hasa and Southeast fields. As a result, it is on course to award more contracts in 2025 to maintain and eventually increase output from these fields through its P5 projects, which aim to achieve an oil production potential of 5 million b/d by 2027.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 UAE economy shows resilience
4 November 2026
-
 Kuwait appoints KPMG for ports strategic plan
4 November 2026
-
 Combined Group signs Kuwait upstream contract
4 November 2026
-
 Qiddiya seeks interest for water infrastructure packages
4 November 2026
-
 Riyadh plans multibillion northern roads network overhaul
4 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
UAE economy shows resilience
4 November 2026
 Commentary
Colin Foreman
EditorState-backed capital is carrying the UAE projects market through the economic shock of the Iran conflict. Government and government-related entities have accounted for $22.4bn of the $34.6bn of contracts awarded in Dubai so far this year, almost two-thirds of the total, according to regional project tracker MEED Projects. Private developers have deferred new launches, and off-plan residential sales in the emirate fell from $9bn in February to $4bn in August.
In Abu Dhabi, state-affiliated developers and cultural agencies are accelerating destination projects on Yas and Saadiyat islands, including the $1.7bn Sphere Abu Dhabi venue.
The energy sector is adding momentum. The UAE’s exit from Opec in May has freed Abu Dhabi National Oil Company (Adnoc) to make greater use of its spare crude capacity, and the company is on course to exceed its 2024 upstream project spending this year. Adnoc Gas has awarded $8.2bn of contracts for the second and third phases of its rich gas development programme.
The $3bn Taweelah C combined-cycle gas turbine plant accounted for most of the $4.17bn of power contracts awarded by early September, while Dubai’s AED30bn ($8.1bn) Tasreef stormwater programme is driving water sector activity.
MEED Projects tracks $103bn of transport schemes at pre-execution stages, including rail links that would give exporters routes that avoid the Strait of Hormuz.
Non-oil activity is also holding up. The UAE purchasing managers’ index compiled by financial information and analytics provider S&P Global reached a 20-month high of 55.3 in September. Net profits at the 10 biggest UAE banks rose 7% to AED47.8bn ($13bn) in the first half, supported by loan growth of 21%.
Meanwhile, Abu Dhabi is repairing relations with Riyadh after a year of friction over Yemen and Sudan. On 8 October, the two countries signed a memorandum of understanding covering power grid interconnection and freight rail.
Risks remain. The Washington-based IMF expects the GCC economy to contract by 3.8% this year, with recovery dependent on shipping through Hormuz returning to normal. US scrutiny of Iran-linked transactions is also tightening compliance demands on UAE banks. That said, there are reasons to be hopeful. The IMF expects the economy to rebound in 2027 with 7.7% GDP growth.
MEED’s November 2026 report on the UAE includes:
> GOVERNMENT: Abu Dhabi mends fences with Riyadh
> ECONOMY: UAE growth holds up as regional risks persist
> BANKING: UAE banks profit as credit growth surges
> UPSTREAM: Adnoc steps up crude expansion
> DOWNSTREAM: Adnoc funnels billions into boosting gas processing
> POWER: Gas-fired projects drive resilience in UAE power sector
> WATER: Tasreef scheme drives UAE water investment
> CONSTRUCTION: State-backed spending cushions UAE construction slowdown
> TRANSPORT: Infrastructure drives UAE growth agenda
> MANUFACTURING: UAE vehicle manufacturing push moves into productionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20947110/main.gif -
Kuwait appoints KPMG for ports strategic plan
4 November 2026
Register for MEED’s 14-day trial access
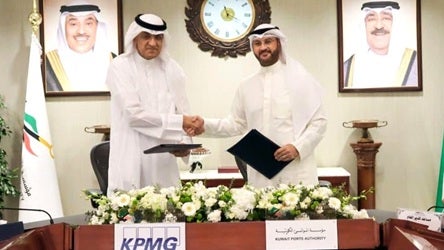
Kuwait Ports Authority (KPA) has appointed the local office of UK-headquartered KPMG to develop its ports strategic plan, which aims to improve the competitiveness, connectivity and performance of Kuwait’s commercial ports.
KPMG will act as lead consultant on the strategic consultancy engagement, with Netherlands-based Haskoning Nederland and local engineering firm Dar Gulf Consult providing engineering consultancy support.
KPMG will consolidate the three consultants’ work into a single strategic plan. It will lead the market, commercial and organisational analysis, as well as develop and implement the strategy.
The scope is split into two workstreams. The first covers strategy development, planning and an implementation framework, including an assessment of KPA’s current market position and performance.
The resulting strategic options and roadmap will be developed into detailed functional plans, supported by key performance indicators, a risk framework and a monitoring plan.
Under the second workstream, KPMG will set up and lead a strategic technical support office for 36 months. The office will provide KPA with strategic oversight, technical advisory services and integrated project management support.
KPA operates Kuwait’s three main commercial ports: Shuwaikh Port, Shuaiba Port and Doha Port.
In line with the New Kuwait Vision 2035 development strategy, KPA is transitioning its operations into high-efficiency smart ports by investing heavily in automated machinery, deeper navigational channels and significant berth capacity expansions.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21106611/main.jpg -
Combined Group signs Kuwait upstream contract
4 November 2026
Register for MEED’s 14-day trial access
Kuwait-headquartered Combined Group Contracting Company has signed a contract to repair and revamp production facilities in West Kuwait, according to a company statement.
State-owned upstream operator Kuwait Oil Company (KOC) awarded the contract, valued at KD9.7m ($31.4m).
The contract has a five-year term.
KOC issued the invitation to bid on 5 October 2025. The initial bid deadline was 4 January 2026, and a pre-tender meeting was scheduled for 4 November 2025.
The contract award to Combined Group was approved on 13 September 2026.
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruptions are the result of a regional war that started on 28 February when the US and Israel attacked Iran.
The disruptions to shipping in the Strait of Hormuz are also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the waterway.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21120792/main.png -
Qiddiya seeks interest for water infrastructure packages
4 November 2026
Register for MEED’s 14-day trial access
Qiddiya Investment Company (QIC) has issued an expression of interest for two water infrastructure packages at Qiddiya City, southwest of Riyadh.
According to a source, the first package covers a wastewater treatment plant with a capacity of 60,000 cubic metres a day (cm/d).
The second package involves a wastewater treatment plant with a capacity of 9,000 cm/d. It will also include a “sizeable” reverse osmosis (RO) facility, a source close to the project told MEED.
The deadline for submissions of interest is 8 November.
The infrastructure package will cater to Saudi Arabia’s 360-square-kilometre Qiddiya entertainment city.
QIC, which is owned by Saudi Arabia’s Public Investment Fund (PIF), is overseeing the development of Qiddiya City, including its supporting utilities infrastructure.
In October 2024, MEED reported exclusively that QIC planned to tender its utilities packages individually under an engineering, procurement and construction model.
QIC had previously planned to procure the infrastructure through a public-private partnership (PPP). However, it cancelled this approach despite receiving two bids for a multi-utility package in 2020.
The original utilities package covered power generation, water desalination, sewage treatment and water transmission networks.
In September 2023, QIC signed infrastructure contracts worth SR2.29bn ($611m) with a joint venture of Saudi Real Estate Infrastructure Company (Binyah) and InfraRoad Contracting.
The contracts covered a wider infrastructure package at Qiddiya’s Resort Core, including roads, utility networks, water storage facilities and pumping stations, as well as the construction of a sewage treatment plant (STP).
Two other major PIF-backed developments, the Red Sea project and Amaala, have each awarded multi-utility packages using a PPP model, while contractors are preparing to bid for two separate wastewater treatment plants for Oxagon, Neom’s industrial cluster.
In September, the utilities system serving Saudi Arabia’s Red Sea tourism destination reached commercial operation, marking the start of a 25-year concession for one of the world’s largest integrated off-grid utilities projects.
The project, known as the Marafiq Red Sea Project or Red Sea Utilities Multi-Utilities Project, includes three seawater RO plants, an STP, a waste management centre and 32,500 refrigeration tonnes of district cooling capacity.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21111446/main.jpg -
Riyadh plans multibillion northern roads network overhaul
4 November 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Royal Commission for Riyadh City (RCRC) is preparing to implement a 189-kilometre (km) programme of road upgrades and extensions in the north of the capital as part of a comprehensive restructuring of the capital’s northern transport infrastructure.
The programme comprises 19 road projects and 33 interchanges serving the airport and 16 surrounding developments, including the Expo 2030 site, Roshn’s Sedra and Plot 1 communities and King Salman Stadium.
Once complete, the upgraded network will have the capacity for 4.2 million daily trips.
Fifteen of the links, totalling 162km, will be funded from the Riyadh City Strategy budget and procured across three waves and five packages.
The remaining four links, covering 27km of roads within and around the airport campus, will be developed by King Salman International Airport (KSIA).
Wave one
Wave one is the most immediate phase, covering seven links totalling 49km around the airport terminals, Expo 2030 and Roshn’s developments.
Fast-tracked for design completion in August 2026, Wave 1 comprises critical primary conduits split across two packages:
Package 1: Covers 11km, comprising an initial 8km stretch of Sheikh Jaber Al-Ahmad Al-Sabah Road and the first extension phase of King Salman Road.
RCRC has already begun implementing the Sheikh Jaber Al-Ahmad Al-Sabah Road scheme, awarding multimillion-dollar contracts for the project this year.
The centrepiece of this wave is the extension of King Salman Road, which will be realigned south along the boundary between KSIA and Roshn.
The new road will have six main lanes and three service-road lanes in each direction, with three full interchanges where Airport Road, a Roshn Sedra link and Sheikh Jaber Road cross it on bridges.
The interchanges will also give separate access to the airport support facilities and terminals, and are each forecast to handle 300,000-400,000 vehicles a day by 2040.
Sheikh Jaber Al-Ahmad Al-Sabah Road will be upgraded along an 8km section and extended by a further 5km. Three grade-separated T-intersections will provide access to Roshn Sedra.
The existing 6km section of King Salman Road will be widened to six main lanes in each direction, with tunnels beneath it at the Prince Saud Bin Jalawi interchange and between Expo 2030 and Roshn Plot 1.
Package 2: Covers 28km of core alignment updates across King Salman Road, the Expo South link, Airport Road, Prince Badr Bin Abdulmohsen Road and Anas Bin Malik Road.
A new 6km road south of the Expo site will extend Prince Saud Bin Jalawi Road through three grade-separated junctions, relieving King Salman Road of Expo and Roshn traffic.
The 8km Airport Road upgrade will add five main lanes and four service-road lanes in each direction, an underpass interchange at Expo Road, a bridge linking Expo with Roshn Sedra and new elevated ramps serving Princess Nourah Bint Abdulrahman University.
Prince Badr Bin Abdulmohsen Bin Abdulaziz Road will be widened from three to four lanes in each direction for 5km, with an underpass to King Salman Stadium.
A tunnel-and-bridge junction will carry it beneath the upgraded 3km Anas Bin Malik Road.
Wave one also includes a main bridge over Riyadh Metro Line 4.
Wave two
Wave two comprises two further packages totalling 72km that extend the network west and south of the airport.
Package 3: Covers 38km and includes the 33km upgrade of Al-Janadriyah Road, the longest single link in the programme, together with the 5km western section of Mohammed Bin Faraj Road. Its design submission is due in November 2026.
Package 4: Covers 34km and comprises the extension of King Salman Road to Al-Janadriyah Road, the 10km upgrade of the Airport Extension Road serving the airport support functions and the 16km upgrade of Prince Saud Bin Abdullah Bin Jalawi Road.
Design is scheduled for submission in March 2027.
Wave three
Wave three is a single 52km package covering the outer northern and eastern corridors. It comprises the 11km upgrade of Al-Thumamah Road, the 17km upgrade of Khuzam Road and the 19km extension of Jabal Azid Road, with design due for submission in August 2027.
Alongside the RCRC-led schemes, KSIA will deliver four links totalling 27km on its own campus. These are the 10km upgrade of the Airport Extension Road adjacent to the terminals, a 6km upgrade of Mohammed Bin Faraj Road, a 5km road to the cargo and aviation services area and a 6km road to the Iconic Terminal.
All three waves are scheduled to reach tender by 2028.
Programme rationale
Designed by Lebanon-headquartered engineering firm Dar Al-Handasah, Taiwan’s Wiecon Consulting Engineers and Germany’s Bodeker, the programme responds to the concentration of Riyadh’s flagship schemes on the city’s northern edge.
Riyadh is planning major developments in the north, with most due for completion by 2030. Daily trips in the area are forecast to rise from about 775,000 today to 1.7 million by 2030 and 3.7 million by 2050.
Roshn’s projects account for 37% of that demand, with Roshn Sedra alone generating more than 520,000 daily trips by 2030.
The sequencing is driven by Riyadh’s event timetable. Wave one targets the links that unlock KSIA’s new terminals, the Expo 2030 site and King Salman Stadium, a venue for the 2034 Fifa World Cup.
The later waves then build capacity for the housing, logistics and mixed-use districts expected to drive traffic growth after 2030, sustaining a pipeline of road contracts in the capital well into the next decade.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21109126/main.jpg