Ras al-Khaimah real estate counters growing pains
21 December 2022

Even as global business conditions deteriorate due to rising benchmark interest rates and inflationary pressures, the UAE’s northernmost emirate is on its way to boasting one of the most active construction pipelines in the GCC.
Led by a strong roster of high-profile multibillion-dollar announcements by firms such as US-based Wynn Resorts, Aldar Properties, Abu Dhabi National Hotels, Dubai Investments and Emaar, it is fast emerging as one of the most exciting project destinations in the region.
But the prospect of significant development on the horizon also brings challenges of equal proportion.
As project activity intensifies, Ras al-Khaimah needs to simultaneously accelerate the scale of investment in adjacent infrastructure and facilities that can draw talent to accommodate the scale of work ahead and create an attractive living environment for its growing population.
“In the next two years, we will see a lot of cranes coming over the skyline of Ras al-Khaimah,” said Abdulla al-Abdouli, CEO of Marjan.
“Given the robust project pipeline – more than 5,000 hotel keys and more than 4,000 residential units – a slew of new requirements will come into play, beginning with the construction industry.”
“First and foremost, the demand for quality contractors and subcontractors, architectural consultants, designers, and landscape architects will undoubtedly increase,” he said.
In the next two years, we will see a lot of cranes over Ras al-Khaimah's skyline
Abdulla al-Abdouli, CEO of Marjan
Al-Abdouli said Ras al-Khaimah could incentivise construction companies to establish a base in the emirate by providing their employees with superior facilities and a quality lifestyle.
“We require more staff accommodations, not only to house workers during the construction period, but also to serve employees for all the job opportunities that will arise once the developments are completed. Coming up with good amenities for people is a must, and we need more businesses to support the supply chain.”
With such massive growth on the horizon and Ras al-Khaimah’s plans to target three million visitors by 2025, Al-Abdouli said that the emirate’s government is currently conducting a gap analysis for the destination.
“Infrastructure is our top priority to ensure that by 2026 when we open the Wynn resort, we do not have any disparities in the market,” he said. “It is about ensuring optimum quality of life through well-equipped facilities like airports, roads, networks, logistics and so on. The ultimate goal is for people to be content living in Ras al-Khaimah.”
The demand for infrastructure, retail and commercial offerings is expected to skyrocket by thousands of square metres in the next few years as Ras al-Khaimah evolves beyond its current primary waterfront tourist destination status.
Sameh al-Muhtadi, CEO of RAK Properties, said tapping into the opportunities surrounding the emirate’s real estate boom needs longer-term thinking – and fast.
“There’s a lot of support sectors that are going to be very much in demand,” he said.
“What will be needed in healthcare and education? The reality is that the whole emirate is transforming, and so with the white-collar jobs coming into play, with families moving here, with consultants moving here, we must think well in advance and prepare for that. We need to take the necessary actions and make the necessary decisions now, so we don’t miss the boat.”
One contractor attending the Business Leaders Forum added that despite the strong pipeline ahead, the size of the Ras al-Khaimah market remains “relatively small”, making it difficult to appeal to or attract large international or regional facility management and technology partners.
Marjan’s Al-Abdouli said regulators are firmly committed to finding solutions to market challenges.
The reality is that the whole emirate is transforming, and so with the white-collar jobs coming into play, with families moving here, with consultants moving here, we must think well in advance and prepare for that
Sameh al-Muhtadi, CEO of RAK Properties
Macroeconomic headwinds
Even with the undeniable positive sentiment in Ras al-Khaimah’s future direction, evolving macroeconomic challenges worldwide remain a concern.
Economic activity in the region has been resilient so far, with a multispeed recovery continuing in 2022. The Washington-based IMF projects Middle East GDP growth at 5 per cent in 2022, up from 4.1 per cent in 2021.
But growth is forecast to slow to 3.6 per cent in 2023 on deteriorating global conditions thanks to rising interest rates, high inflation and increased energy costs.
According to the IMF, inflation for the region was projected at 14.2 per cent in 2022 and is expected to remain elevated next year.
Gulf oil exporters are expected, on average, to enjoy budget surpluses of about 33 per cent between 2022 and 2026, leading to a strong improvement in their balance sheets.
The UAE hopes the economy will grow by 5 to 6 per cent this year, and by the same pace over the next few years to double its economy by 2031.
“I think the challenge we all have today is around planning and forecasting due to the current volatility and uncertainties around the world,” said Khalid Anib, CEO of Abu Dhabi National Hotels.
“It is something that is extremely difficult to deal with. But we must keep trying.”


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 What IFAD’s wind-down means for Gulf commodity markets
24 September 2026
-
 US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
-
 Hitachi wins Al-Mashaer Al-Muqadasah metro revamp
24 September 2026
-
 Contractor wins 6GW data centre campus infrastructure
24 September 2026
-
 Algeria officially launches major phosphate project
24 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
What IFAD’s wind-down means for Gulf commodity markets
24 September 2026
The wind-down of ICE Futures Abu Dhabi (IFAD) – the Abu Dhabi-based futures exchange operated by US-based global exchange and clearing house operator Intercontinental Exchange (ICE) – on 31 July 2026 was the end of an era. It was also the opening move in a transformation whose legal consequences will keep the Abu Dhabi Global Market (ADGM) Courts, Dubai International Financial Centre (DIFC) Courts and London arbitral tribunals occupied for years.
One strategy
On 31 July, Abu Dhabi National Oil Company (Adnoc) announced that all four of its crude grades would move from IFAD pricing to a Platts Dubai prompt-month mechanism in November. ICE published its wind-down circular the same day.
The Iran war was the catalyst: the official selling price of Murban, Adnoc’s flagship crude grade, surged from $63 a barrel in February to $110.75 in May, and Asian refiners – managing their margins against a crude price set two months ahead of loading – demanded a more straightforward mechanism.
But the IFAD wind-down must be read alongside three other key decisions. On 1 May, the UAE withdrew from oil producers’ group Opec, freeing Adnoc from quota constraints that had capped production at 3.4 million barrels a day against a capacity of 4.85 million. On 6 July, Adnoc launched a global liquefied natural gas marketing and trading platform in the ADGM, targeting 47 million tonnes a year by 2035. Then, on 22 July, DP World signed a 50-year concession with the Fujairah Ports Authority to develop the Al-Rugaylat and Dibba terminals on the Gulf of Oman coast.
Together, these decisions constitute a coherent strategic architecture: a Hormuz-independent, Fujairah-centred, Indian Ocean-facing trade infrastructure designed to serve the markets where commodity demand will be most durable over the next 30 years.
Force majeure battleground
The legal consequences of the Iran war are immediate and novel. The most contested issue is force majeure.
IFAD was established within ADGM, which applies English common law, and was regulated by the ADGM Financial Services Regulatory Authority (FSRA). Under English law, there is no freestanding right to invoke force majeure, and the threshold is demanding. General disruption or increased costs do not suffice. The question is whether performance has become legally or physically impossible.
When Iranian strikes damaged the Fujairah Oil Industry Zone, the sole IFAD delivery point, and vessel traffic through Hormuz fell from over 100 ships a day to fewer than 14, the impossibility argument strengthened materially. But a critical distinction separates parties whose non-delivery was attributable to the physical closure of Hormuz from those whose non-delivery reflected elevated war risk premiums and unavailable insurance: the latter falls short of legal impossibility under English law.
The governing law of each contract is therefore significant. Under UAE civil law, statutory provisions address both impossibility and the court’s discretion to reduce obligations. A party whose contract is governed by English law faces a harder test, even on identical facts.
This asymmetry is generating an uptick in advisory work as trading houses assess their positions across portfolios of contracts with different governing law provisions.
The sanctions picture adds further complexity: the successive reimposition of US sanctions following ceasefire collapses has affected the legality of positions that were fully compliant when established, raising questions for which English law provides no settled answer.
The legal consequences of the Iran war are immediate and novel
Legal infrastructure
The FSRA’s regulatory framework has demonstrated resilience during the crisis. Its Recognised Investment Exchange licensing regime, under which IFAD operated, and its Environmental Instrument classification, making ADGM the first jurisdiction in the world to regulate voluntary carbon credits as financial instruments, remain available to new market entrants.
ADGM Courts, applying English common law, has developed a strong body of legal precedent over 11 years. And London-based ICE Clear Europe’s relationship with IFAD provides a model for how future exchange infrastructure in ADGM might access London clearing capability while remaining regulated in Abu Dhabi.
With the 31st UN Climate Change Conference Cop31 opening in Antalya on 9 November 2026 and Cop32 scheduled for Addis Ababa in 2027, the Article 6 Paris Agreement carbon market framework is developing rapidly. The FSRA’s Environmental Instrument classification positions ADGM as a natural regulatory home for the Gulf-Africa carbon market infrastructure that neither London nor Singapore is positioned to provide. The DP World concession, with its East African port network providing the physical verification layer that carbon credit integrity requires, reinforces that positioning.
Legal practitioners who develop expertise in this intersection of English common law, FSRA regulation, DIFC financial services law and international commodity trading before the IFAD delivery disputes are resolved and before the replacement infrastructure is announced, will be well placed in a jurisdiction growing at 57% annually by assets under management. The story of what follows IFAD has barely begun.
 https://image.digitalinsightresearch.in/uploads/NewsArticle/19954346/main.gif
-
US DFC approves $1.8bn financing for Jordan National Water Carrier
24 September 2026
The US International Development Finance Corporation (DFC) has approved a loan of up to $1bn and political-risk insurance of up to $800m for Jordan’s National Water Carrier Project.
The $1bn loan will be provided to National Carrier Project Company (NCPC) to finance the design, development, construction, operation and maintenance of the project’s seawater desalination plant, water conveyance system and dedicated solar generation plant.
The $800m of political-risk insurance will be provided to Paris-based investment and utility firms Meridiam and Suez, which are developing the project.
The National Water Carrier, also known as the Aqaba-Amman Water Desalination and Conveyance Project, is being developed under a public-private partnership between Jordan’s Ministry of Water & Irrigation and NCPC, a special-purpose vehicle owned by Meridiam (90%) and Suez (10%).
The project involves the design, development, construction, operation and maintenance of a seawater desalination plant, a water transmission system and dedicated renewable power generation facilities under a build-operate-transfer model.
Jordan signed the project’s final technical and legal agreement with Meridiam in April, following months of negotiations.
The project’s capital cost was put at about $4.3bn, with total costs including financing estimated at $5.8bn.
Financial close has not yet been completed. The project’s technical director said in July that the final agreements required for financial close were still being prepared, with construction expected to start in the fourth quarter of 2026. Water pumping is scheduled to begin in the fourth quarter of 2030.
Jordan’s cabinet approved a $97m financing agreement with the French Development Agency in July as the government continued to complete the project’s financing arrangements.
The cabinet also approved a package of facilities and exemptions for the National Water Carrier Project on 17 September to help finalise start-up procedures for the project in the Aqaba Special Economic Zone.
Jordan’s water needs
The Aqaba-Amman water desalination and conveyance project will desalinate 300 million cubic metres of seawater annually. It will also include a 450-kilometre pipeline and pumping systems reaching elevations of up to 1,100 metres.
The project is intended to help address Jordan’s severe water scarcity. As one of the world’s most water-stressed countries, Jordan consumes nearly 1 billion cubic metres of water a year.
The domestic sector consumes approximately 50% of this, with only 61 cubic metres of water available per person a year, far below the global absolute water scarcity level of 500 cubic metres of water per capita.
According to the government, the scheme will increase overall water supply by 40%, with per capita availability expected to rise to 110 cubic metres annually.
Annual output from the Water Carrier Project will be nearly equivalent to the total storage capacity of all dams in the kingdom and almost three times the output of the Disi Water Project.
The project is expected to supply about 40% of Jordan’s drinking water needs, with operations scheduled to begin in 2030. It will also include a 280MW solar photovoltaic plant in Al-Quweira covering roughly 30% of the project’s energy needs.
Financing
The government previously said the project had secured about $663m in grants from international partners, including the US, the European Union, Germany, the Netherlands, the UK, France, Italy, Japan and the Green Climate Fund.
The Jordanian government is contributing $722m.
Meridiam is arranging about $2.9bn in private sector financing from international financial institutions. The financing package includes support from institutions including the World Bank Group, European Investment Bank, European Bank for Reconstruction & Development, Islamic Development Bank, Proparco, Japan International Cooperation Agency and the Opec Fund for International Development.
A consortium of Jordanian banks led by Housing Bank is providing up to $1.1bn in local financing, with the Social Security Investment Fund also taking an equity stake alongside Meridiam.
Local manufacturing
The project is also beginning to generate associated industrial investment.
On 30 August, Jordan’s cabinet approved the establishment of a steel pipe manufacturing and coating plant in Aqaba with investment of up to JD120m ($169m). The plant is expected to allocate 50% of its production to the National Water Carrier and create about 420 jobs. Its output will also be available for future water, gas transmission and pumping projects.
The Aqaba Special Economic Zone Authority and the Ministry of Water & Irrigation also launched a dedicated single-window platform in August to streamline licensing and permitting for the National Water Carrier project.
Once operational, the project is expected to remain under the PPP structure for 26 years before ownership transfers to the Jordanian government.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19943001/main.jpg -
Hitachi wins Al-Mashaer Al-Muqadasah metro revamp
24 September 2026
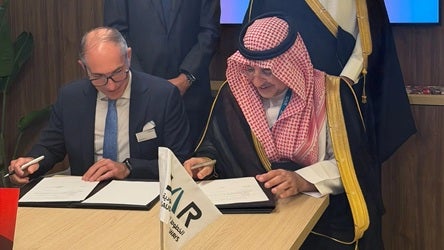
Saudi Arabia Railways (SAR) has signed a contract with Japan’s Hitachi Rail to revamp the Al-Mashaer Al-Muqadasah metro project in Mecca.
The 18-kilometre line includes nine stations and has a design capacity of about 72,000 passengers an hour in each direction.
The scope includes upgrades to improve reliability, operational performance and long-term maintainability.
SAR chief executive Bashar Al-Malik and Hitachi Rail’s Middle East and Africa signalling and rail solutions vice-president, Carlo Piacenza, signed the contract.
The rail line operates during the Hajj period and transports pilgrims between Mina, Muzdalifah and Arafat.
It was developed to reduce reliance on buses, ease congestion on pilgrimage routes, and improve safety and crowd management during Hajj.
The Saudi authorities procured the project on a fast-track basis to meet a fixed operational deadline for Hajj. It entered initial operation in 2010, with China Railway Construction Corporation acting as the main contractor for civil works and overall delivery.
Hitachi Rail supplied key rail systems, including signalling and telecommunications. SAR subsequently assumed responsibility for the asset and has led later improvement and upgrade programmes.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19941437/main.jpg -
Contractor wins 6GW data centre campus infrastructure
24 September 2026
Dammam-based construction firm Al-Yamama Company for Trading & Contracting has won a contract to develop infrastructure for a planned 6GW hyperscale artificial intelligence (AI) data centre campus in Riyadh.
The project will be delivered on an early contractor involvement (ECI) basis. Under the ECI process, selected contractors are required to submit methodologies and design proposals, after which one team will be selected to deliver the construction works.
Saudi Arabia’s AI company Humain, owned by the Public Investment Fund (PIF), tendered the contract in May, as MEED reported.
The scope of infrastructure work covers:
- Construction of 380kV/132kV/33kV electrical distribution network, two substations with a capacity of 500MVA and 200MVA, bulk supply point (2,000MVA)
- Water network and fire protection systems
- Sewage treatment plant and wastewater network
- Stormwater systems
- Roads
- Underground cable and fibre optic networks
- Landscaping works
The client is being supported by Canadian engineering firm Hatch, France’s Egis and US-based firm JLL.
The development will be built on a 24-square-kilometre site in the Al-Saad area in east Riyadh. It will be delivered in two phases across six plots, each with a capacity of 1GW.
Humain was launched in May last year to operate and invest across the AI value chain.
Humain is building full-stack AI capabilities across four core areas: next-generation data centres, hyper-performance infrastructure and cloud platforms, and advanced AI models, including Allam.
Also in May 2025, Humain signed preliminary deals with US chipmakers AMD and Nvidia to build multibillion-dollar advanced digital infrastructure in the kingdom.
AMD said it will invest up to $10bn to deploy 500MW of AI compute capacity in Saudi Arabia over the next five years.
In October 2025, PIF and Saudi Aramco signed a non-binding term sheet setting out key terms under which Aramco would acquire a minority stake in Humain, with PIF retaining majority ownership.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19940798/main.jpg -
Algeria officially launches major phosphate project
24 September 2026
Algeria’s Minister of State and Minister of Hydrocarbons, Mohamed Arkab, has officially launched the construction of the country’s Integrated Phosphate Project (IPP) during a visit to the province of Annaba.
This major phosphate project spans the provinces of Annaba, Souk Ahras, Tebessa and Bir El-Ater.
The scope of the IPP includes:
- A raw phosphate extraction and beneficiation complex at the Bled El-Hadba site (Bir El-Ater): designed for 5.5 million tonnes a year (t/y) of ore extraction and 3.2 million t/y of phosphate concentrate production
- An industrial complex at the Oued Keberit site: to include several production units, with the capacity to produce 2.4 million t/y of phosphate fertilisers as well as 570,000 t/y of nitrogen fertilisers
- Port facilities at the port of Annaba: for exporting surplus fertiliser production
- Utilities and auxiliary infrastructure
In a statement, the Ministry of Hydrocarbons said that Arkab’s official visit was taking place “within the framework of periodic field monitoring of the project’s implementation stages”.
It said: “The project stands as one of the most significant strategic and structural initiatives for the national economy; it aims to develop and exploit national mineral resources and to process and add value to phosphate locally, thereby boosting value-added output and increasing non-hydrocarbon exports.”
It added: “The integrated phosphate project is part of a comprehensive vision to valorise national mineral resources and develop associated downstream industries.
“This initiative aims to boost national production of fertilisers and high-value-added chemical products, support food security, create jobs, and contribute to diversifying the national economy and increasing non-hydrocarbon exports.”
On 12 August, Algeria’s national oil and gas company Sonatrach and the Algerian Chinese Fertilisers Company (ACFC) signed two engineering, procurement and construction (EPC) contracts for the project.
The contracts were part of the Bled El-Hadba phosphate development project, which is expected to be worth $7bn.
The contracts were signed by Italy’s Saipem and China Harbour Engineering Company (CHEC) as part of the first phase of the integrated phosphate project.
Saipem’s contract was worth about €500m ($577m), according to a statement from the Italian company.
It focuses on constructing fertiliser processing and production facilities.
The contract with CHEC focuses on constructing port facilities at the Port of Annaba.
ACFC was created in March 2022 by Algerian companies Asmidal and Manadjim El-Djazair (Manal), which own 56% of the company, and Chinese groups Wuhuan and Tianan, which own the remaining 44% stake.
Manal and Asmidal are both subsidiaries of Sonatrach.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19927744/main.jpg