Qatar banks look to calmer waters in 2025
15 January 2025

Doha’s lenders enter 2025 with a sense of quiet confidence, backed by broadly favourable macroeconomic trends shaped by still-solid oil prices and non-oil growth that will provide an uplift for operating conditions and loan growth.
Although these operating conditions are not as supportive for Qatari banks as for their peers in the UAE and Saudi Arabia, growth is nonetheless coming back to the sector, enabling banks to book more loans.
Credit growth is looking stronger. In the first 10 months of 2024, Qatari banks registered an annualised credit growth of 6.3%, more than double that of 2023, which was 2.9%.
“Resuming growth is supporting operating conditions for Qatari banks,” says Amin Sakhri, primary rating analyst at Fitch Ratings.
According to Sakhri, non-oil economic activity is also increasing. But it is the cornerstone hydrocarbons project, the North Field liquefied natural gas (LNG) expansion, that will likely give ballast to lenders in the next two to three years.
By the end of 2025, Qatari LNG production capacity will have risen to 110 million tonnes a year (t/y), ahead of a further increase to 126 million t/y by 2027. That sets the economy up well, with banks positioned to feel the impact.
“The LNG project, which benefits related sub-sectors, also supports credit growth. So there’s also another supportive element for Qatari banks,” says Sakhri.
Robust profitability
Profits have been healthy in the past year, benefitting from banks’ strong capitalisation levels and adequate liquidity.
Ratings agency Standard & Poor’s (S&P) expects this trend to continue with only a modest drop in net interest margins owing to interest rate cuts – and the impact of replacing non-resident funding (which is high in Qatar relative to other regional banking sectors) with higher-cost domestic funding sources.
Full-year 2024 results are awaited, but indications are it will have proved another solid year for banks’ bottom lines.
Qatar National Bank (QNB), which represents over 50% of total system assets – with just eight domestic commercial banks, it is one of the Gulf’s most concentrated banking sectors – reported a Q3 2024 net profit of QR4.5bn ($1.23bn), a 5.4% increase over the previous year. Loans and advances were up by 11% in the same period.
Profits were helped by still high interest rates in the first half of the year. While the lower interest rate environment will have some erosion effect on margins, Qatari banks are generally less sensitive to rates than other banks in the region.
Other metrics also look healthy. “We’ve seen the return on average equity increasing to 16.7% from 15.8% in 2023. This is despite still high loan impairment charges in Qatar, which are some of the highest in the GCC,” says Sakhri.
Property market uncertainty
One area of weakness is in the real estate sector, which has suffered from excess supply over a number of years, bringing down prices. According to Fitch, the banking sector’s exposure to the real estate and contracting sectors remains high, representing 17% of total sector lending.
“The real estate and construction sectors remain under pressure, and we see that in the banks’ loan books,” says Sakhri. “The cost of risk is still elevated in a GCC context, at 78 basis points in the first nine months of 2024 for the Qatari banking sector as a collective, well above the level observed in the UAE and Saudi Arabia.”
Those real estate pressures have contributed to higher loan impairment charges compared to the rest of the region. S&P envisages non-performing loans (NPLs) remaining elevated at 4% in 2025.
“If you look at stage 2 loans, the average for the Qatari banking sector is around 10-11%, whereas for the UAE and Saudi, it’s about 5%. Some of the smaller banks are heavily exposed to the real estate and construction sectors, leading to about a third of the loan book being classified as Stage 2, which is quite substantial,” says Sakhri.
However, Qatari lenders have tightened their underwriting standards in the real estate and contracting sectors, focusing on government-related projects and assignment of cash flow proceeds to reduce their repayment risks, notes Fitch. Some banks have also been reducing their exposure to these sectors.
In S&P’s view, while continued pressure on real estate prices could accelerate the migration of stage 2 loans to NPLs at some midsize banks, public sector initiatives and interest rate cuts will help prevent a more severe deterioration in asset quality.
Underlying strength
In any case, the sector’s strong capitalisation and conservative provisioning remain two core strengths. The average CET1 stood at a solid 15.5% at the end of September 2024. This, says Fitch, is further supported by strong provisioning practices, with 140% of stage 3 loans covered by provisions, among the strongest in the GCC.
Aside from the real estate exposure, the other key risk in Qatar is its long-standing reliance on external funding. The sector’s non-resident funding accounted for a still-high 42% of the banking sector’s funding at the end of October 2024, and the sector’s net external funding was a substantial 50% of GDP at the end of 2023.
There has been some change as GDP has grown, meaning total funding relative to GDP is decreasing. However, about half of the sector’s funding comes from external sources, which is not expected to reduce significantly.
“Yes, hydrocarbon revenues have been supporting domestic liquidity, but Qatari banks are really quite reliant on external funding. In Saudi Arabia and the UAE, you’re looking at 15%-20% coming from external funding, and Qatar has been traditionally more than twice that,” says Sakhri.
Looking forward, the broader positive impact from the LNG increase will provide improved operating conditions for Qatari lenders, which will impact on banks’ bottom lines – offsetting the lower credit demand that will result from the completion of a number of key infrastructure projects.
What’s more, notes Sakhri, lower rates mean the cost of funding will reduce, which is favourable for Qatari banks because they have some of the highest cost of funds in the GCC, and the impact on net interest margin will be less marked.
Put that together, and Qatari bank chiefs have reason to view the year as one in which the glass is half-full rather than half-empty.
MEED's February 2025 special report on Qatar includes:
> GOVERNMENT & ECONOMY: Qatar economy rebounds alongside diplomatic activity
> POWER & WATER: Facility E award jumpstarts Qatar’s utility projects
> DOWNSTREAM: Qatar chemical projects take a step forward

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Combined Group signs Kuwait upstream contract
4 November 2026
-
 Aramco Q3 profit rises 9% despite attacks on facilities
3 November 2026
-
 UAE monitors desalination plants after oil spill
3 November 2026
-
 Oman signs 1GW battery storage agreement
3 November 2026
-
 Consultants bid for Roshn’s north Riyadh scheme
3 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Combined Group signs Kuwait upstream contract
4 November 2026
Register for MEED’s 14-day trial access
Kuwait-headquartered Combined Group Contracting Company has signed a contract to repair and revamp production facilities in West Kuwait, according to a company statement.
State-owned upstream operator Kuwait Oil Company (KOC) awarded the contract, valued at KD9.7m ($31.4m).
The contract has a five-year term.
KOC issued the invitation to bid on 5 October 2025. The initial bid deadline was 4 January 2026, and a pre-tender meeting was scheduled for 4 November 2025.
The contract award to Combined Group was approved on 13 September 2026.
Kuwait’s oil and gas sector is currently in the midst of a major crisis, as disruptions to shipping through the Strait of Hormuz have dramatically reduced exported crude oil volumes.
The disruptions are the result of a regional war that started on 28 February when the US and Israel attacked Iran.
The disruptions to shipping in the Strait of Hormuz are also creating significant challenges for oil and gas construction projects, which normally import equipment and materials through the waterway.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21120792/main.png -
Aramco Q3 profit rises 9% despite attacks on facilities
3 November 2026
Register for MEED’s 14-day trial access
Saudi Aramco reported a 9% year-on-year increase in adjusted net income to $31.2bn in the third quarter of 2026, supported by stronger financial performance across its businesses, particularly downstream operations, and despite persistent attacks by the Yemen-based Houthi rebels on its facilities across the kingdom.
The company’s revenue and other income from sales reached $140.492bn in Q3 2026, up from $111.509bn in the same period last year.
Downstream adjusted earnings before interest and taxes (ebit) increased by 234% year-on-year, reflecting stronger refining margins.
Cash flow from operating activities increased to $38.7bn in Q3, compared to $36.1bn a year earlier, while free cash flow rose to $28.2bn from $23.6bn over the same period.
The company maintained a gearing ratio of 5.5% at the end of the first nine months of the year, compared to 6.2% at the end of the first half of the year.
Return on average capital employed in Q3 remained the same as in the previous quarter at 22.1%.
Aramco’s capital expenditure in Q3 2026 declined to $10.52bn from $12.55bn in the same period last year, while capex in the first nine months of the year stood at $35.78bn.
Commenting on the Q3 financial results, Aramco’s president and CEO, Amin H Nasser, said: “Geopolitical uncertainty and attacks on key energy facilities continued to amplify the global energy supply crisis in the third quarter of 2026, with serious implications for global energy security.
“Despite challenges, the unwavering dedication of our workforce, our operational excellence, the flexibility of our system and the strength of a supply network built over decades enabled us to continue delivering reliably to our customers through this extraordinary period.
“We continue to explore additional overseas storage capacity and alternative export routes to further strengthen our global supply network, and our robust operational and financial performance during this volatile period demonstrates the value of our resilience.
“Backed by our strong balance sheet, we remain focused on the disciplined execution of priority projects and on leveraging advanced technologies to enhance performance and unlock new opportunities. This is how we will continue to meet the world’s evolving energy needs and deliver value for our shareholders and customers.”
ALSO READ: Sabic swings back to profit in Q3 with $224m net income
https://image.digitalinsightresearch.in/uploads/NewsArticle/21121169/main.jpg -
UAE monitors desalination plants after oil spill
3 November 2026
State utility Etihad Water & Electricity (EtihadWE) says it is monitoring seawater quality at desalination plant intake points following an oil spill off the UAE's northern coast.
In a statement, the utility said it is continuing to "implement proactive measures to safeguard the water production system" following the spread of an oil slick towards coastal areas in the emirates of Umm Al-Quwain, Ras Al-Khaimah, Ajman and Sharjah.
The spill involved the tanker Gem No. 2, which was struck by a projectile in UAE territorial waters on 9 October. The resulting oil pollution has raised concerns over potential contamination of seawater used by desalination plants along the northern coast.
EtihadWE said its measures include continuous monitoring of seawater quality at plant intake points, regular testing of produced and distributed water, and verification of compliance with approved standards before water enters the distribution network.
The utility added that the precautionary measures will not affect the continuity of water supplies to consumers in the Northern Emirates.
In an earlier update on 30 October, the Climate Change & Environment Ministry said the oil slick was concentrated off the coast of Umm Al-Quwain, extending partially towards coastal areas in Ras Al-Khaimah, Ajman and Sharjah.
The ministry said the concentration of pollution had declined significantly and that the leak had been stopped at source. However, surveying, monitoring and clean-up operations are continuing in affected coastal areas.
The Energy & Infrastructure Ministry said specialised technical teams are continuing work to address technical issues with the tanker, including repairing damaged sections, restoring operational systems and assessing the integrity of its structure.
The proximity of the oil slick to the Naqa'a desalination plant in Umm Al-Quwain has drawn particular attention. According to media reports, the slick approached to within approximately 2 kilometres of the facility.
Naqa'a has a production capacity of 150 million imperial gallons a day, equivalent to approximately 682,000 cubic metres a day. The plant supplies water to the Northern Emirates and has been operational since 2022.
It is owned by Naqa'a Desalination Plant, a special-purpose vehicle established by Mubadala, Acwa and the former Federal Electricity & Water Authority, now known as EtihadWE.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21104534/main3427.jpg -
Oman signs 1GW battery storage agreement
3 November 2026
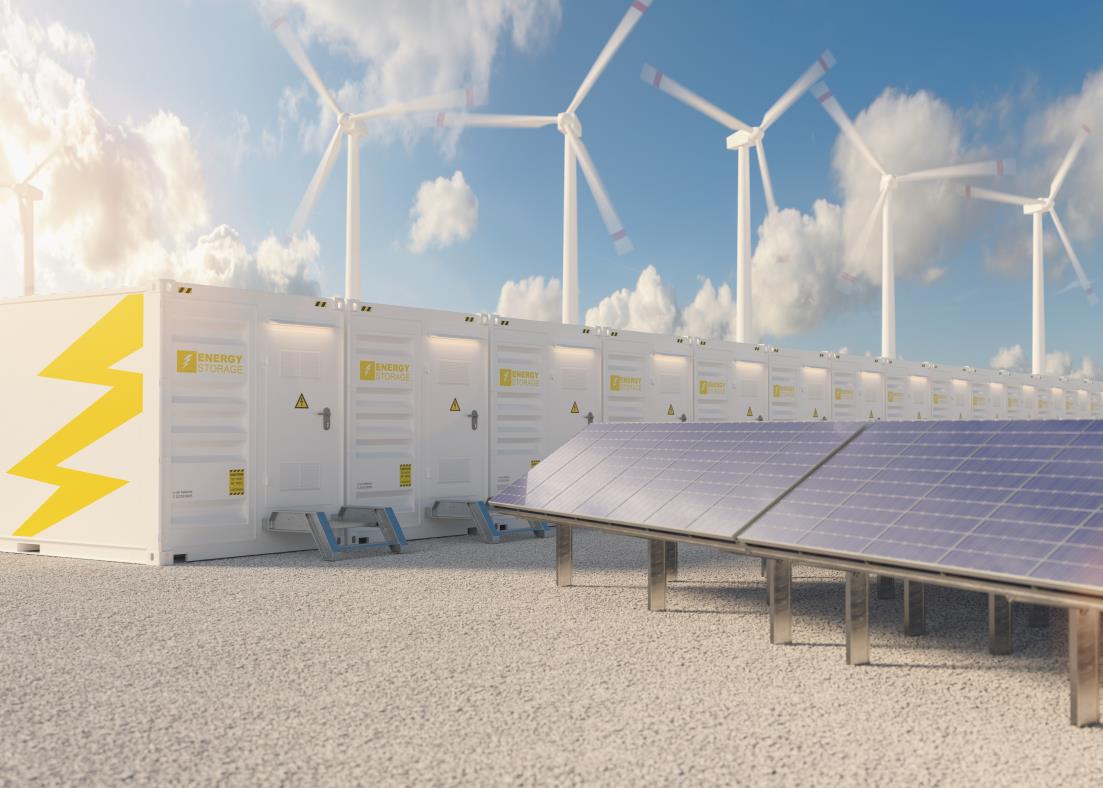
Oman's Nama Holding, a subsidiary of Oman Investment Authority (OIA), has signed a framework agreement with China's State Grid International Development to develop battery energy storage systems (bess) with a targeted capacity of 1GW.
The agreement covers two battery storage systems, each with a capacity of 500MW, at Duqm Industrial Station and Al-Subaikhi (Ibri Solar 3) Station.
It is understood that both systems will operate at 400kV and connect to Oman's national electricity transmission grid.
The deal is part of a package of economic and investment agreements signed by OIA with Chinese institutions and companies during the Oman-China conference on 2 November. OIA put the combined value of the bess projects at approximately RO384.5m ($1bn).
The agreement comes as Oman advances plans to expand its renewable energy capacity and strengthen the electricity transmission network.
Nama Power & Water Procurement Company is also procuring a separate 950MW standalone bess programme comprising five facilities in the sultanate, as MEED exclusively reported.
The wider package of agreements, signed during Sultan Haitham Bin Tariq's state visit to China, covers sectors including renewable energy, mining, logistics, digital transformation and space technology.
In the wind energy sector, Oman's O-Green and Shanghai Electric Wind Power signed a strategic partnership to establish a joint research and development centre and wind turbine testing facility at the Mawarid turbine factory in Duqm.
The partnership will focus on adapting turbine technologies to Gulf climate conditions, supporting local manufacturing and developing green ammonia projects in Oman.
The partnership is valued at RO3.85m-RO7.69m ($10m-$20m). It also identifies potential future contracts exceeding $1bn, alongside green ammonia projects and initial investment commitments in Oman exceeding $200m.
In solar, OIA signed a preliminary term sheet with Chinese firms PCG Power and Hoymiles for a partnership valued at RO38.45m ($100m).
The partnership aims to develop solar energy projects in Oman and establish a solar inverter manufacturing facility serving markets in the Middle East and North Africa.
It is also intended to support the localisation of solar-related industries, expand domestic production and develop export markets.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21102638/main.jpg -
Consultants bid for Roshn’s north Riyadh scheme
3 November 2026
Saudi gigaproject developer Roshn Group has received proposals from lead design consultants for its planned flagship development in north Riyadh.
Consultants submitted proposals on 1 November for detailed design, tender documentation and construction documents for the project’s first plot.
The planned development covers 13.7 square kilometres and will be a residential-led mixed-use scheme containing retail, office, hospitality, education and civic facilities.
The consultancy scope for plot one includes infrastructure, utilities, public-realm works and the site adaptation of Roshn’s residential prototypes. It has been divided into two work packages.
The first package covers phases A, B and E, which cover about 7.8 million square metres (sq m) and will include 17,000 units.
The second package covers phases C and D, covering about 4.7 million sq m and with more than 15,000 units.
The site is bordered by the Expo 2030 site, King Abdulaziz Park, the Sports Innovation Lab Zone and National Housing Company’s Khozam development.
Transport connectivity is a key element of the masterplan. Two metro stations are planned, including a station at the interchange between the existing Line 4 and planned Line 7, and a dedicated Line 7 station. The development could also be served by the planned Qiddiya high-speed rail link and a potential diversion of King Salman Road.
The scheme will add to Roshn’s existing development pipeline in Riyadh, which includes the multi-phase Sedra community. The developer is expanding its focus from single-family housing to larger mixed-use districts under its Roshn 3.0 strategy.
Last month, Roshn signed a preliminary agreement with TMG Saudi, the local subsidiary of Egypt’s Talaat Moustafa Group, to establish a joint venture to explore a separate mixed-use project in Riyadh.
TMG Saudi will hold a 51% stake in the proposed joint venture and Roshn will hold the remaining 49%. The companies said they will undertake detailed masterplanning and prepare a business case for the project, which preliminary studies indicate could include more than 55,000 residential units.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21101503/main.jpg