
PPP activity rebounds in 2023
26 October 2023

This report on project finance and PPP also includes: Liquidity drives project finance appetite
There has been an increase in both the number and value of public-private partnership (PPP) contract awards made across the Middle East and North Africa region in 2023, according to data from regional projects tracker MEED Projects.
The total value of PPP deals from January to early October has already overtaken the value of awards made in 2022. To date, $21.3bn of PPP deals have been finalised in 2023, compared to $18.1bn in 2022, representing a rise of 18 per cent.
With most of the final quarter of the year still to go, there is every chance that the 2021 total of $22.6bn will also be surpassed. In the five years before that, the total was at most about $12bn a year, underlining the healthy position of the market at the moment.
However, the longer-term record high of $29.6bn, set in 2009, still appears to be out of reach.
In numerical terms the picture is more balanced, with 34 PPP contract awards to date in 2023, compared to 44 in 2022 and 47 in 2021. However, the average size of PPP contracts being handed out this year is significantly up, at $627m an award so far in 2023 compared to $401m in 2022 and $482m in 2021.
Water and transport lead the way
The surge in deal-making has been particularly evident in the water sector, where $9.3bn-worth of deals have been signed this year, far ahead of last year’s figure of $3.6bn.
The largest of these is a $2.2bn contract for Abu Dhabi National Oil Company’s Mirfa seawater treatment plant. A consortium of Orascom Construction and Metito has been appointed to develop the project.
Just behind this in terms of value is the $2.1bn contract to install a water transmission pipeline from the Ar-Rayis1 independent water plant to Rabigh for Saudi Water Partnerships Company. The contract was won by a consortium of Cobra Group, Al-Khorayef Water & Power Technologies and Orascom Construction.
The transport sector has also been performing well, with $5.3bn-worth of contracts in 2023, significantly more than the $428m in 2022. The biggest schemes include a $2.2bn contract for Iran’s Roads & Urban Development Ministry to expand capacity at Tehran’s Imam Khomeini International airport, for which a joint venture of Hycan Automobile Technology Company and Khatam al-Anbia was appointed in September.
Another major contract is the $1.9bn deal that Saudi Ports Authority (Mawani) signed with China Harbour Engineering Company to upgrade Terminal 1 and expand Terminal 2 at King Abdulaziz Port in Dammam.
Construction and power struggle
There has been a relative decline in other areas, however, and most notably in construction. The high level of activity seen in the sector in 2022 has not been sustained, with contract values falling by two-thirds so far this year to $1.6bn. The number of PPP awards in the sector has also fallen, from 14 in 2022 to seven so far in 2023 – the lowest figure for this part of the market since 2019.
The power sector looks set to continue its recovery, with several solar and wind independent power projects (IPPs) in Saudi Arabia expected to be awarded before the end of the year. An estimated $4.9bn-worth of deals have been awarded in the first nine months of 2023.
The expected award of the Saudi IPP contracts, as well as the third solar photovoltaic project in Abu Dhabi, indicates that the total value of power deals this year could equal or exceed that of last year.
PPP deals in the power sector – which pioneered the model in the region – account for 139 of the 332 contracts awarded between 2015 and 2023. This is followed by the water sector with a further 86 contracts, construction with 50 awards and transport with 31 deals. The remaining contracts were awarded in the chemicals, oil and gas and industrial sectors.
Within the power sector there has been a preference for build, own and operate (BOO) contracts, with 84 in total over the period, worth a combined $30.1bn; and build, operate and transfer (BOT) contracts, of which there have been a further 76, worth $20.1bn. In the water sector, the contracts are more evenly spread between BOO, BOT and build-own-operate-transfer (BOOT) schemes, while both the transport and construction sectors tend to favour BOT models.
Across all sectors, BOT, BOO and BOOT contracts account for 77 per cent of all contracts by value in the period under review. BOT emerged as the frontrunner in 2023 in terms of the value of awards, having been second to BOO contracts last year.
For most of the past decade, these two contract models have been the dominant ones, although BOOT was far ahead of the pack in 2021 thanks to the award of a $6bn contract that year by Algeria’s Transport Ministry for the development of El-Hamdania Port.
Gulf economies remain dominant
The most important markets in the region for PPP deals in 2023 are Saudi Arabia, with $11.6bn-worth of contract awards, followed by the UAE with $5.7bn and Iran with $2.2bn – the latter almost wholly because of the Tehran airport deal.
Among the other major contracts in these markets is a $2bn deal signed by Red Sea Global in September with a team of Masdar, EDF and Korea East-West Power Company for a multi-utilities package at the Amaala development, including a solar power plant, battery storage, sewage treatment and a desalination plant.
Also notable is Etihad Rail’s $800m contract with National Infrastructure Construction Company and National Projects & Construction in early October for the first phase of the light rail network in Abu Dhabi.
No other country has yet broken through the $1bn mark in terms of PPP contract awards in 2023, although Oman may yet do so. So far this year, the sultanate has seen the award of $824m-worth of projects, including two $400m contracts awarded by Oman Wastewater Services Company to develop solar power plants at Manah, southwest of Muscat.
This year’s figure is the highest for the sultanate in several years and marks a step-change from its recent performance. In 2021 and 2022, PPP contracts worth just $50m and $60m were signed, respectively.
Other markets have been performing more poorly. Both Egypt and Iraq have seen the level of activity slump significantly, with just $520m-worth of contracts in Egypt so far this year, compared to $3.6bn in 2022. Iraq has seen no PPP contract awards in 2023 at all, after two bumper years in which $8.5bn worth of deals were finalised in 2021 and $3.7bn in 2022.
The fall in these markets is a further sign of the wider problems facing their economies and could be a signal that private-sector actors are increasingly wary of signing up to long-term deals in such uncertain economic and political environments.
Among other, smaller markets, there have been signs of activity in both Bahrain and Tunisia, with one and two deals respectively this year, after no activity was recorded in either market last year.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
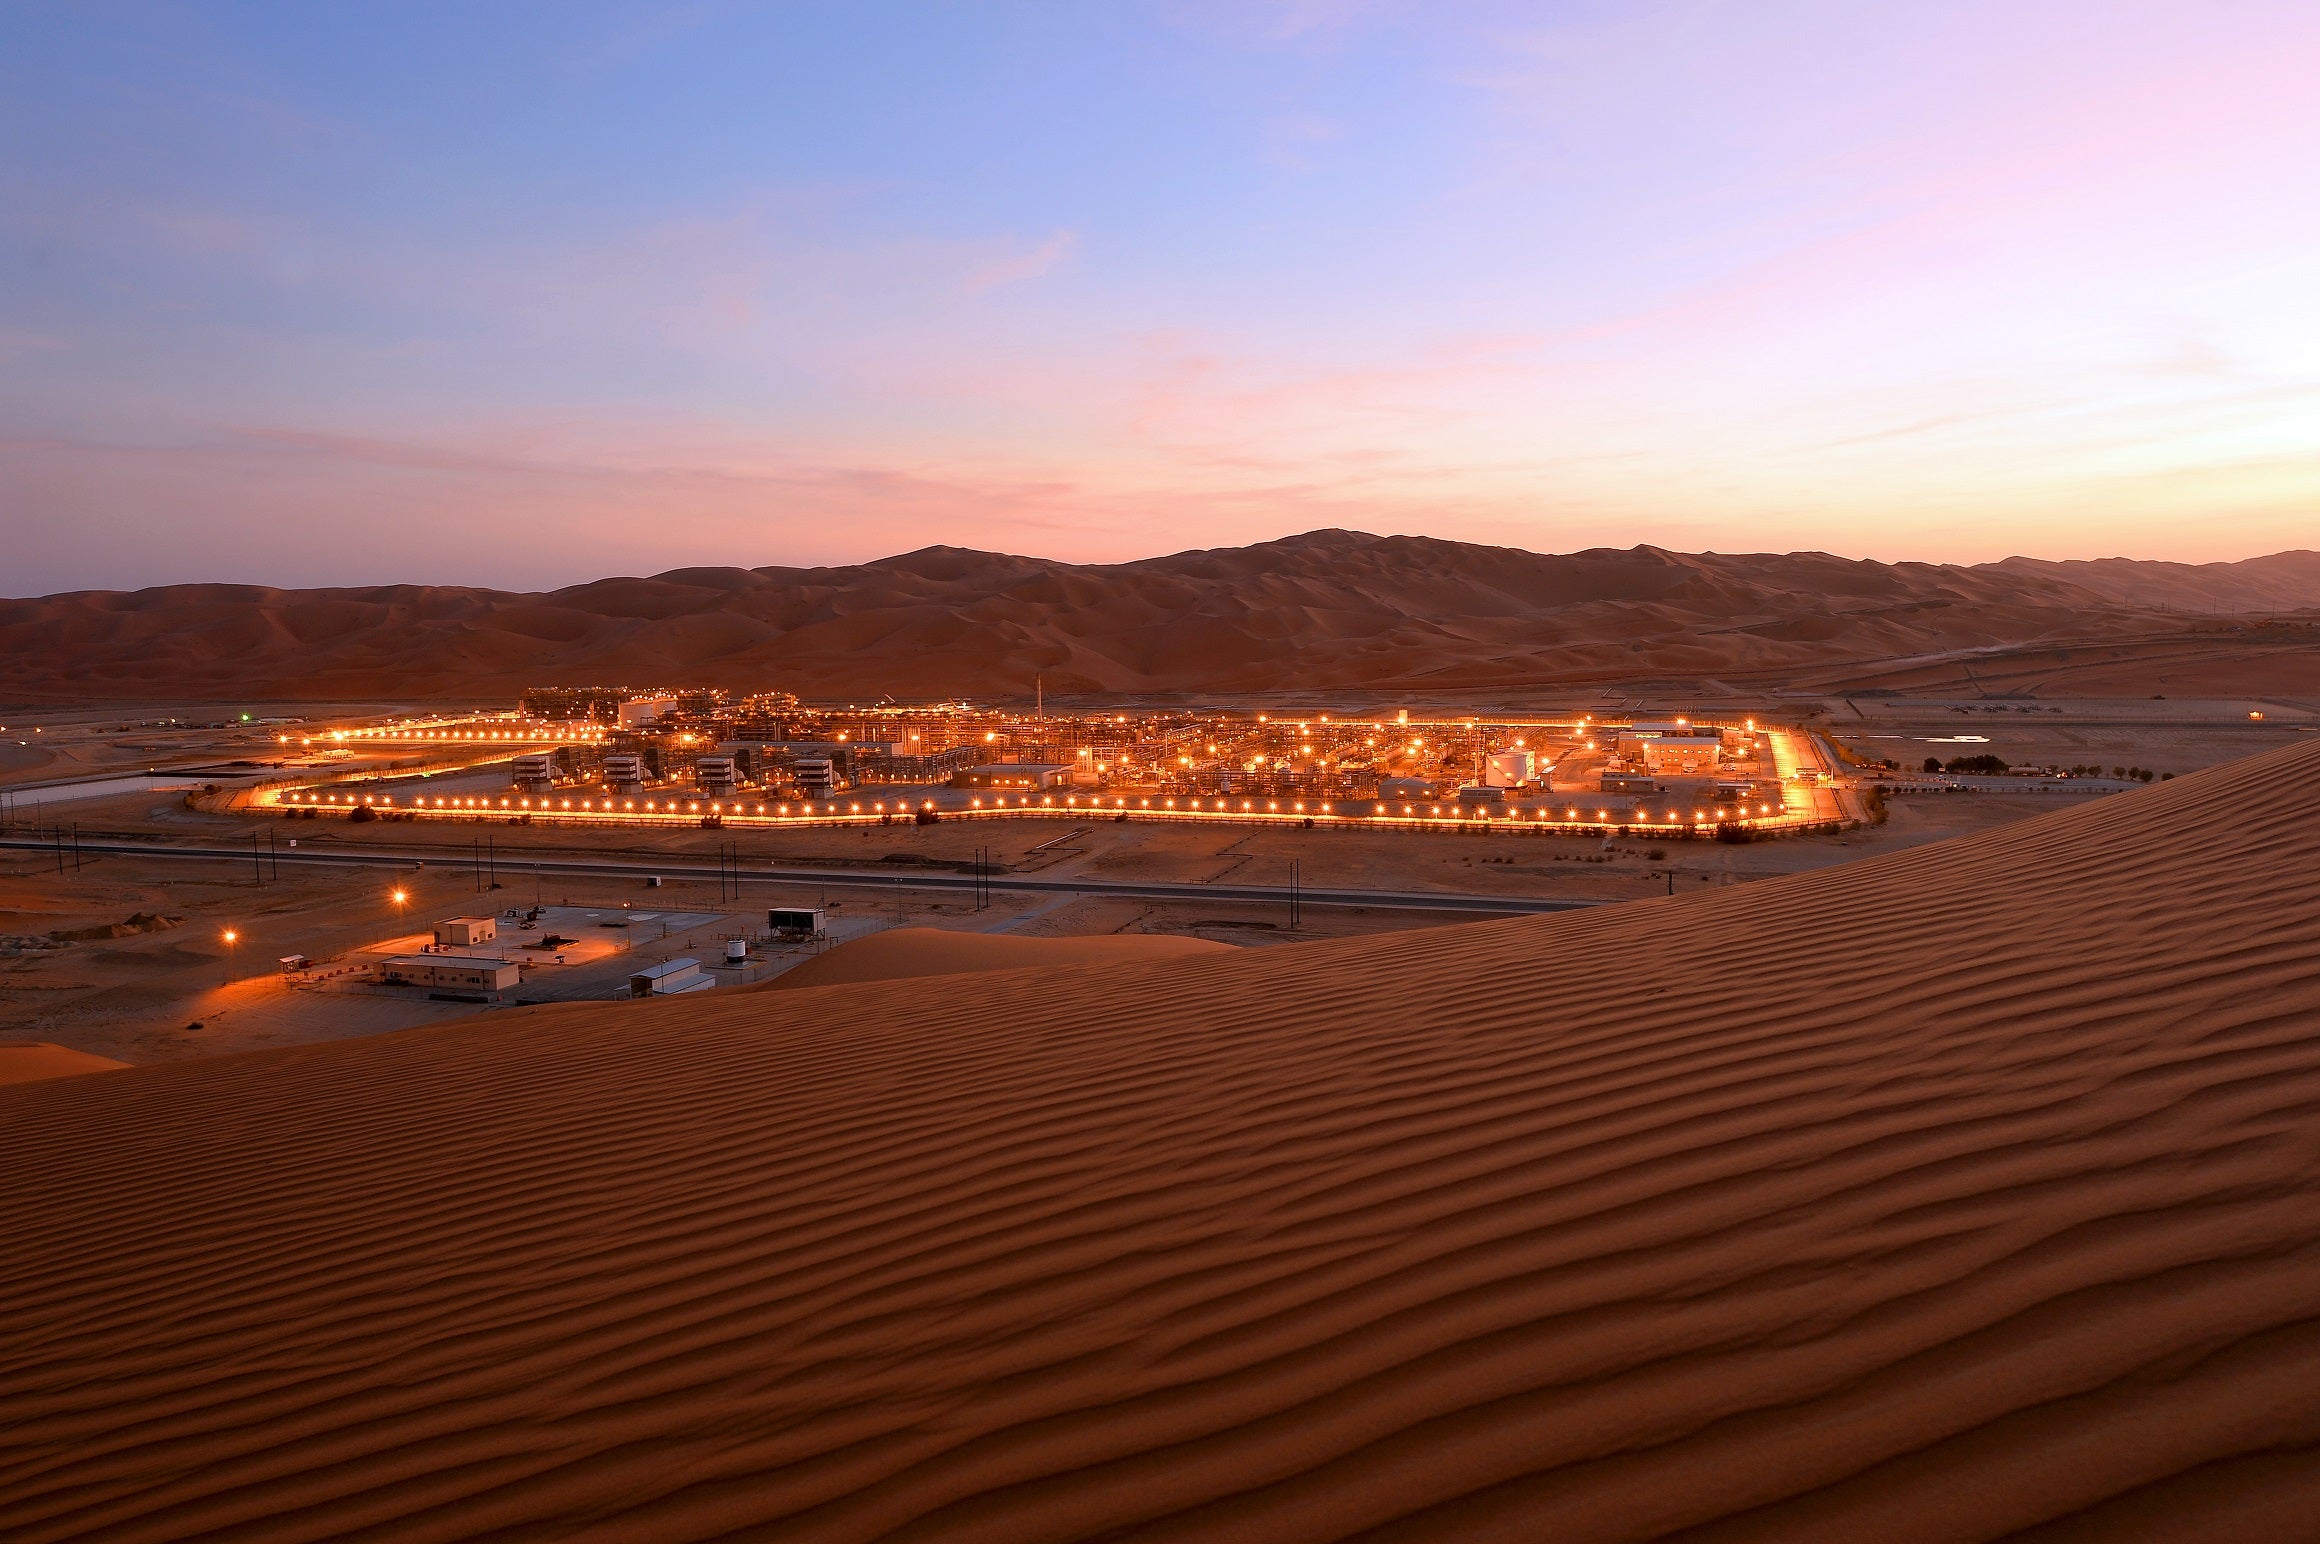 Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
-
 Dewa International signs energy and infrastructure MoUs
22 October 2026
-
 QatarEnergy and TotalEnergies to develop Lebanon solar plant
22 October 2026
-
 Building resilience into infrastructure delivery
21 October 2026
-
 Riyadh tenders Expo 2030 Adaptation and Innovation Pavilion
21 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends

Related Articles
-
Brent hits $112 a barrel following Saudi oil field attack
22 October 2026
Oil prices climbed more than 3% on 22 October after a drone targeting Saudi Aramco’s Shaybah oil field development killed two people and injured two others a day earlier, adding to concerns over energy supplies as attacks on Saudi energy infrastructure intensified.
Global benchmark Brent crude hit $112.30 in early trading on 22 October, but later pared gains and was trading at $111.52 a barrel as of 11am GST.
Three residents and a Saudi citizen were killed in two separate incidents in Saudi Arabia’s Eastern Province on 21 October, authorities said, as attacks on the kingdom accelerated following an escalation of hostilities with the Iran-backed Houthi group in neighbouring Yemen.
Overnight, the Saudi-led coalition fighting the Houthis in Yemen announced that it had intercepted and destroyed four drones in the Eastern Province.
Saudi air defences intercepted a drone attempting to target a processing facility at Saudi Aramco’s Shaybah oil field development on the morning of 21 October, the Saudi Ministry of Energy said.
The official Saudi Press Agency (SPA) carried a statement quoting an energy ministry official as saying the attempted attack resulted in the deaths of two residents – a Filipino and a Nepali – and injuries to two others – an Indian and a Pakistani – after debris fell due to the interception.
Following the interception, a fire broke out in a vehicle belonging to a contractor at the Shaybah oil field, outside the facility’s perimeter, with no impact on operations.
Dammam airport attack
Separately, a Houthi attack on King Fahd International airport in Dammam on the evening of 21 October killed an Indian resident and a Saudi citizen.
Eight people were also injured in the attack, including a Saudi national, a Nepali, and two nationals each from India, Yemen and Bangladesh. Injuries ranged from minor to critical, the Saudi General Authority of Civil Aviation (Gaca) said the next day.
“The attack also caused property damage, the extent of which is currently being assessed. Further updates will be provided,” Gaca said, adding that operations had since resumed at Dammam airport.
Saudi Arabia has come under sustained attack from the Iran-aligned Houthi rebel group in October, including strikes on Riyadh’s international airport in what authorities described as the kingdom’s deadliest incidents in years, as the war with the group escalates.
The Houthi militias also struck an administrative building at Aramco’s headquarters in Dhahran, in the Eastern Province, on 13 October, resulting in a limited fire.
The Houthi rebels opened a new front in the regional war between Iran and the US in mid-July, when they breached a four-year truce with Saudi Arabia in Yemen’s civil war, which began in 2014, and started attacking Saudi vessels and Aramco energy assets along the Red Sea, including repeated strikes on the Jizan refinery.
The 1,200-kilometre East-West pipeline operated by Aramco was also hit by Houthi missiles in September, and once directly by Iran in April.
The East-West pipeline transports crude from Saudi Arabia’s Eastern Province oil fields to the Red Sea port city of Yanbu on the kingdom’s west coast. It has a pumping capacity of 7 million barrels a day.
Saudi Arabia relies heavily on the East-West pipeline to bypass the volatile Strait of Hormuz maritime chokepoint and ship crude from its Red Sea coast. Riyadh has increasingly used the line to route exports away from Hormuz since the US-Iran conflict began on 28 February – a tactical advantage most of its Gulf neighbours lack.
Aramco resumed crude exports via the pipeline at the start of October.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20841984/main.jpg -
Dewa International signs energy and infrastructure MoUs
22 October 2026
Dubai Electricity & Water Authority’s (Dewa) new development arm, Dewa International, has signed four memorandums of understanding (MoUs) with international partners to explore investment and project development opportunities in the energy, water and infrastructure sectors.
The agreements, signed during Dubai’s Water, Energy, Technology and Environment Exhibition (Wetex 2026), follow the launch of the wholly owned subsidiary in June, as reported by MEED.
At the time, the utility said the arm would be used to export Dubai’s energy and water infrastructure model, with a focus on developing conventional and clean energy projects for global markets.
At Wetex, Dewa International signed an MoU with France’s EDF Power Solutions to explore potential joint participation in solar, wind, battery energy storage and pumped-storage hydropower projects.
A separate agreement with China Energy International Group explores the company’s potential role as an engineering, procurement and construction (EPC) partner for major energy, water and infrastructure projects. The MoU also covers cooperation in project development and EPC services.
A further agreement with UK-based Capital Dynamics focuses on potential joint investments in operational clean energy assets in Europe. The parties will also explore establishing an investment vehicle for future clean energy infrastructure investments.
Dewa International also signed a fourth agreement with Mumbai-Headquartered Tata Consultancy Services, exploring the company’s potential role as a technical consultancy partner. The scope covers technology strategy, information technology and operational technology integration, and asset performance management solutions.
Dewa currently has almost $7bn-worth of power and water projects under execution across the UAE, according to regional projects tracker MEED Projects.
Its flagship Mohammed Bin Rashid Al-Maktoum Solar Park is the largest single-site solar park in the world. The utility is currently advancing the project’s seventh phase, with Abu Dhabi Future Energy Company (Masdar) recently submitting the lowest bid for the project, as exclusively reported by MEED.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20828111/main0128.jpg -
QatarEnergy and TotalEnergies to develop Lebanon solar plant
22 October 2026
Register for MEED’s 14-day trial access
State-owned QatarEnergy and France’s TotalEnergies have agreed to jointly develop a solar power plant in Lebanon.
The agreement was announced on 16 October during the Qatari prime minister’s official visit to Beirut, where he held a joint press conference with Lebanese Prime Minister Nawaf Salam.
According to a statement published by the Lebanese Prime Minister's Office, the plant will be an initial project under a broader framework for energy cooperation between Qatar and Lebanon. Its capacity, location, investment value and implementation schedule have yet to be disclosed.
Qatar’s Prime Minister Sheikh Mohammed Bin Abdulrahman Bin Jassim Al-Thani said: “The aim is to develop a major investment project that benefits the Lebanese economy, as well as the Qatari companies and entities participating in it.”
Separately, Salam said the Lebanese and Qatari governments were “close to reaching an agreement” to rehabilitate, develop and modernise Lebanon’s electricity-generation infrastructure.
The proposed project would cover the country’s various electricity-generation sources and associated infrastructure, aiming to improve the reliability of electricity supplies and reduce costs.
The project would use a build, operate and transfer model, under which Qatari entities would finance, implement and operate the facilities without upfront investment costs for the Lebanese treasury, Salam said.
Salam also said the proposal was being prepared with support from the International Finance Corporation, and that he hoped to present it to the Lebanese government soon.
The wider initiative is intended to address Lebanon’s longstanding electricity-generation shortfall and overcome financing constraints that have delayed infrastructure projects in the sector.
As MEED previously reported, the Lebanese government continues to advance broader reforms to the country’s electricity sector.
In August, Lebanon’s Electricity Regulatory Authority invited private sector companies to submit expressions of interest (EoIs) for several upcoming power-generation projects.
The EoIs cover up to five grid-connected solar photovoltaic projects with a combined installed capacity of 350 megawatts-peak. The projects are also expected to include battery energy storage systems with a combined capacity of 1,000 megawatt-hours.
The regulator is also seeking proposals for distributed dual-fired thermal power plants with net capacities of 20MW-100MW.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20827458/main.jpg -
Building resilience into infrastructure delivery
21 October 2026
The regional disruptions earlier this year tested Gulf supply chains, challenging the movement of goods and construction materials and raising questions about the ability of infrastructure programmes to maintain momentum.
For the UAE Ministry of Energy & Infrastructure, the experience reinforced the importance of the systems that support project delivery, from transport networks and customs procedures to domestic manufacturers and international suppliers.
“The disruption reinforced an important principle: infrastructure resilience is ultimately about the ability of the national system to continue operating under pressure,” says Mohammed Al-Mansoori, undersecretary for infrastructure and transport affairs.
Supply resilience
The ministry worked with ports, customs authorities, transport and rail operators, contractors, suppliers and the private sector to maintain the flow of essential goods and construction materials. It monitored critical materials and project schedules, identified alternative sources and adjusted procurement and delivery arrangements.
The response included movement exemptions and facilitation measures for more than 6,600 lorries, while rail freight operations increased from approximately one journey a week to as many as seven journeys a day. Priority and green corridors were activated, customs procedures facilitated and critical shipments prioritised at ports.
According to Al-Mansoori, these measures contributed to an estimated 25% reduction in transport costs, a 40% improvement in customs clearance times and an increase of approximately 15% in port capacity during the response period.
For infrastructure projects, the ministry worked with local manufacturers and suppliers to identify alternative sources of road and construction materials meeting the required technical specifications and quality standards. This helped reduce reliance on disrupted international supply routes and support ongoing projects.
The experience also highlighted the value of existing coordination mechanisms and partnerships.
“It also reinforced a fundamental principle: resilience means ensuring that critical infrastructure delivery does not depend on a single supplier, a single route or a single mode of transport,” Al-Mansoori says.
The ministry is planning to build on this experience by diversifying suppliers, strengthening domestic manufacturing and improving supply-chain monitoring.
Resilience is increasingly being incorporated into procurement planning. For critical materials and services, the ministry aims to identify risks early, broaden the pool of qualified suppliers and ensure viable alternatives are available.
The approach supports the UAE’s wider industrial objectives, including the national in-country value programme, which seeks to direct a greater share of procurement expenditure into the national economy.
“Our objective is not simply to purchase more locally. It is to help create competitive national supply chains,” Al-Mansoori says.
Domestic suppliers must be able to meet the technical requirements, quality standards and volumes demanded by major infrastructure programmes. Localisation is therefore about developing competitive industrial capabilities while shortening supply chains, improving responsiveness and encouraging investment.
“Localisation is not simply a procurement choice; it is an investment in national capability and long-term resilience,” Al-Mansoori says.
The ministry is also working with contractors to manage pressures from fluctuating material, insurance and transport costs. Its approach combines commercial discipline with early engagement to prevent external pressures from affecting project delivery.
“Our approach is based on early engagement, transparency and disciplined commercial management,” Al-Mansoori says. “Long-term infrastructure delivery depends on strong contractors as much as it depends on strong contracts.”
Contractors remain responsible for normal market and contractual risks, but the ministry seeks to assess exceptional pressures objectively, supported by evidence of their impact on costs and schedules. Realistic planning, early procurement and proactive risk management also help maintain momentum.
“The objective is to strike the right balance between protecting the government’s commercial interests and securing best value for money, while maintaining an efficient, sustainable contracting market capable of continuing to deliver strategic infrastructure projects,” Al-Mansoori says.
Resilience means ensuring that critical infrastructure delivery does not depend on a single supplier, a single route or a single mode of transport
Project delivery
The ministry’s focus on measurable outcomes is reflected in the Emirates Road enhancement project, which involves widening approximately 25 kilometres of Emirates Road from three to five lanes in each direction, alongside major improvements to Interchange No. 7.
The works are expected to increase road capacity by up to 65% and reduce journey times by up to 45%.
The project illustrates the ministry’s emphasis on assessing infrastructure by the benefits it delivers, rather than simply the scale of construction.
“Infrastructure success should be measured by the value it creates – not just by the kilometres we build,” Al-Mansoori says.
That principle is increasingly important as the UAE balances new construction with the long-term costs of operating and maintaining its assets. Decisions made during planning and construction can influence maintenance requirements, operating costs and performance for decades.
For Al-Mansoori, resilience, domestic capability and effective delivery are closely connected. Stronger local supply chains can reduce exposure to external shocks, while closer engagement with contractors can help projects withstand cost pressures.
Don’t miss MEED’s MENA Construction Summit 2026, taking place under the patronage of the UAE Ministry of Energy & Infrastructure
Secure your place as an attendee or request the sponsorship deck by clicking here or emailing us at meedevents@meed.com
https://image.digitalinsightresearch.in/uploads/NewsArticle/20810056/main.gif -
Riyadh tenders Expo 2030 Adaptation and Innovation Pavilion
21 October 2026
Register for MEED’s 14-day trial access
Expo 2030 Riyadh has tendered the design-and-build main contract for the Adaptation and Innovation Pavilion in the exhibition’s Technology District.
The pavilion will be built on a plot of at least 12,710 square metres and will feature a two-level basement, ground-level public areas, an elevated skywalk, visitor experience areas, food and beverage outlets, retail space, VIP facilities, offices, back-of-house areas, exhibition spaces, an amphitheatre and a resonance hall.
The facility is being designed to accommodate a minimum of 20,000 visitors a day at peak periods, with an anticipated average of about 15,000 visitors a day. The project targets LEED Gold certification.
The tender was issued on 1 October, with bids due on 6 January 2027.
The design-and-build contractor will be responsible for completing, reviewing, verifying, coordinating and technically integrating the design, including specialist contractor design portions and coordination with the novated lead design consultant.
The scope includes completing early works and substructure activities, including grading, bulk earthworks, excavation, cut and fill, soil improvement, raft foundations, reinforced-concrete basement walls, basement columns through to the ground-floor slab, waterproofing, mechanical, electrical and plumbing (MEP) provisions, and backfilling.
The contractor will also deliver the superstructure and building envelope, including structural works, facade engineering and installation, roofs, waterproofing, external finishes, and permanent facade access and maintenance systems. The internal works will cover front-of-house and back-of-house areas, public and core spaces, internal finishes, fixtures, fixed fittings, joinery, circulation areas, lobbies, stairs, toilets, storage, waste areas and associated builder’s works.
The building services package includes MEP systems, information and communications technology, extra-low-voltage systems, building management systems, security, fire and life safety systems, specialist lighting and vertical transportation.
The contract also covers the visitor experience package, including procurement, installation, integration, testing, commissioning and handover of visitor-facing environments, media, immersive and audiovisual technologies, interactive elements, experiential lighting, digital content, interpretive and wayfinding systems, controls and supporting infrastructure.
Within-plot infrastructure and utilities, landscaping, public realm works, paving, planting, irrigation, signage, street furniture, drainage, stormwater systems, external lighting, security, and fire and life safety systems are also included.
The contractor will be responsible for procurement, off-site fabrication, construction, testing and commissioning, performance verification, training, operations and maintenance documentation, operational readiness, handover, defects rectification and close-out.
The main works tender is based on a 60% RIBA Stage 3 design, with the Stage 3 design to be completed to 100% through an addendum.
Early works and substructure works, as well as the lead design consultant, will be novated to the contractor. Visitor experience works are included as a provisional sum.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20801465/main.jpeg