Omani banks look to projects for growth
12 December 2023

As government spending on infrastructure projects ramps up, Omani lenders are poised to expand their loan books in 2024, following a year of stability that saw most banking metrics improve gradually, in line with the economy’s steady recovery from the pandemic.
Banks are looking to sink their teeth into fresh opportunities emerging from Vision 2040 diversification projects. In doing so, they will benefit from their relatively captive market for corporate credit, since – unlike in other regional states with deeper capital markets – Omani companies have limited access to alternative funding sources beyond the banking sector.
Not that banks in Muscat have it easy. This year, profits have been subdued by weaker net interest margins. Lending was also modest in the first three quarters of 2023, at 4.4 per cent, according to Fitch Ratings, which is essentially the same level as in 2022.
However, the ratings agency sees large government-backed projects, particularly infrastructure schemes, leading credit growth to accelerate to 6-7 per cent in 2024.
Jamal el-Mellali, a director at Fitch Ratings, says one aspect unique to Oman is that the government-related entities (GREs) – to which banks are highly exposed – have made some large early repayments.
“They have taken advantage of the high oil prices to pay down debt. And we have seen the same trend for the sovereign itself,” he says.
According to Fitch, Omani banks benefit very little from higher interest rates as local-currency long-term loans do not reprice with changes in the Central Bank of Oman’s (CBO’s) benchmark rate and competitive pressures limit banks’ repricing abilities.
“One aspect that is unique in the GCC is that Omani banks do not benefit to a great extent from higher interest rates,” says El-Mellali.
“That is because long-term lending in Omani rials, which represent the bulk of the lending, is not driven by the benchmark rate set by the CBO. So even though the CBO has increased rates by a cumulative 550 basis points since March 2022, the average net interest margin for the banks has only increased by 20 bps.”
This striking figure reflects Oman’s highly competitive banking sector, where banks lend to the same large corporate clients, mostly GREs.
Asset quality and impairment
Asset quality is not a major challenge in the sultanate. Loan impairment charges will continue to rise in line with banks’ conservative provisioning policies, but this should be balanced by stronger non-interest income and cost discipline, notes Fitch. Loan quality should continue to recover in 2024, reflecting more supportive macroeconomic conditions.
“Asset quality has been fairly stable again, compared with last year, with an impairment loss ratio for the sector of 4.4 per cent in the first nine months of 2023,” says El-Mellali.
“That’s unchanged compared with 2022. And this is because we are seeing a slow recovery from the sectors that were impacted by the pandemic, namely real estate and hospitality, and the construction sector.”
Lower provisions should also help banks with profit generation. However, the expectation is that any improvement to net income in 2024 will be modest because banks do not see much benefit from higher rates. On top of that, interest rates may have peaked.
“Our base case is that the Fed will start cutting rates in the second half of next year, and because the Omani rial is pegged to the dollar, the CBO will certainly follow any changes in the Fed funds rate. So from that front, we don’t see any improvement in banks’ net interest margins in 2024,” says El-Mellali.
Islamic banking and consolidation
One area of Oman’s banking system that has seen rapid growth in recent years is the Islamic sector. The latest CBO figures show that the total assets of Islamic banks and banks with Islamic windows increased by 12.7 per cent to RO7.2bn ($18.7bn), constituting about 17.6 per cent of the banking system’s assets at the end of September 2023.
Islamic banking entities’ financing of RO5.9bn ($15.3bn) at the end of September 2023 represents healthy growth of 11.6 per cent in year-on-year terms.
Although still small relative to the conventional sector, the Islamic sector in Oman is likely to continue growing, following reforms such as the introduction in 2022 of the wakala money market instrument. This allows Islamic lenders to place remunerative deposits with the Central Bank for up to a maximum of three months.
“We will continue to see a very high growth in the next year in the Islamic banking segment, especially since banks have ramped up the distribution capabilities of their Islamic windows,” says El-Mellali.
Although the past year has seen some merger and acquisition (M&A) activity, with HSBC Bank Oman gaining approval in August for its merger with Sohar International Bank – and an abortive attempt from the country’s second-biggest lender, Bank Dhofar, for Ahli Bank – the scope for further consolidation may be limited.
With less than 20 banks, Oman’s banking sector is already more concentrated than others. As Fitch notes, the three largest banks already control almost 50 per cent of total assets, which is considered a high level. That means the Central Bank has to be more careful when approving M&A deals.
Rather than inorganic growth, Omani lenders may be more inclined to grow by organic means. And with a host of new projects gaining traction, the next year should provide some new avenues for productive lending.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Oil prices rise above $100 a barrel as conflict escalates
9 September 2026
-
 What actually slows a gigaproject down
9 September 2026
-
 Qatari firm wins $221m Qiddiya stadium MEP deal
9 September 2026
-
 Jordan tenders advisory for wastewater treatment plant
9 September 2026
-
 Consultants bid for Abu Dhabi light rail project management
9 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Oil prices rise above $100 a barrel as conflict escalates
9 September 2026
Register for MEED’s 14-day trial access
Oil prices rose above $100 a barrel on 9 September for the first time since July as the US-Iran conflict escalated and Iran-backed Houthi forces attacked Saudi energy infrastructure.
Brent crude futures reached $100.95 a barrel, while US benchmark West Texas Intermediate (WTI) rose to $95.60. Brent had last traded above $100 on 24 July.
The latest escalation has heightened concerns about oil supplies from the region, with shipping through both the Strait of Hormuz and the Red Sea facing disruption.
Flows through the Strait of Hormuz had fallen below 2 million barrels a day (b/d) from about 8-9 million b/d before the latest escalation, according to Rystad Energy.
At the same time, Houthi attacks on Saudi Arabia threaten another important route for oil exports, with the group targeting energy infrastructure and shipping in and around the Red Sea.
US strikes on Iranian tankers
US forces destroyed five Iranian crude oil carriers on 8 September after Iran’s Islamic Revolutionary Guard Corps (IRGC) targeted a US Navy warship with ballistic missiles.
The US Central Command (Centcom) said the warship successfully evaded two Iranian attacks and that no US personnel were harmed.
Four of the Iranian vessels – Kaviz, Charminar, Horizon 1 and Riesco – were struck in the Gulf of Oman, while the Derya was attacked near Kharg Island, Iran’s main crude export hub.
The M/T Riesco subsequently sank in the Gulf of Oman, according to Centcom.
Iran responded by launching ballistic missiles towards Jordan. Jordan’s armed forces said 18 of 20 missiles were intercepted, with the remaining two falling in unpopulated areas.
Iran’s IRGC also said it had attacked two US naval vessels, eight oil tankers and 10 other vessels in the Gulf, although it did not identify the vessels or provide evidence of the attacks.
The latest exchanges mark a further escalation in the US-Iran conflict, which began on 28 February.
Houthi attacks raise supply concerns
The conflict has also widened into a renewed confrontation between Saudi Arabia and Yemen’s Iran-backed Houthi movement.
On 8 September, Saudi authorities said Houthi attacks had targeted civilian and economic sites in Abha, Khamis Mushait, Jazan and Najran in the south of the kingdom, injuring 73 people.
Saudi Arabia’s Ministry of Energy said several energy sector facilities and installations had been targeted, causing fires and forcing a temporary halt to some operations.
The Houthis said their attacks were in response to Saudi military action in Yemen, including what they described as attacks on Houthi positions and a Saudi blockade of ports and airports.
Riyadh condemns attacks
Saudi Arabia has strongly condemned the Houthi attacks and warned that it would take measures to defend its territory and national assets.
In a statement on 8 September, the Ministry of Energy said authorities were working to address the impact of the attacks and ensure the safety of facilities and personnel while maintaining operations in accordance with approved plans.
Saudi Arabia’s Ministry of Foreign Affairs also condemned the attacks and said the kingdom had the right to take measures to defend its sovereignty and protect its citizens, residents and national assets.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19505512/main0138.jpg -
What actually slows a gigaproject down
9 September 2026
Ask anyone delivering a major programme in the GCC what causes delays and sequencing will come up early. Utilities go in too late. Approvals lag behind construction. Stations, depots and access roads are procured as if they belong to different projects rather than one system.
“None of this is new. The industry has understood these risks for years,” says Alan Caldwell, managing director for transport and infrastructure at WSP Middle East.
For Caldwell, that is what makes the pattern worth interrogating rather than simply restating.
“The more important question is why the same issues around interfaces, approvals, stakeholder alignment and delivery sequencing continue to slow major programmes when the risks are already so well understood,” he says.
The answer, he argues, is not that these programmes are too big or too technically complex. What breaks a schedule is a wider system delivered as a set of disconnected parts; an approval sitting with an authority team with no visibility of the construction sequence downstream; or a station package proceeding without the utilities diversion it depends on.
“Infrastructure programmes do not struggle because a railway is too large or a highway network is too complex,” Caldwell says. “They encounter difficulties when interconnected elements are delivered in the wrong order.”
Sequencing decisions are rarely purely technical either, he adds. They are commercial – shaped by which assets need to unlock value first, which phases are tied to funding, and where sales or investment assumptions depend on infrastructure landing in a particular order.
Approvals sit at the centre of that logic. On many programmes, they become one of the biggest sources of lost time – not because the requirements are unreasonable, but because approvals are not planned, evidenced or owned as part of the delivery logic from day one.
Caldwell has seen the same pattern across three decades of Gulf delivery, from early work on Palm Jumeirah to today’s region-wide transport programmes.
“The decisive factor has often been the same: whether interfaces, approvals, responsibilities and delivery sequencing are aligned early enough to prevent complexity becoming delay.”
Integration needs to be well understood
“Most programme teams in the region would say they understand the need for integration,” Caldwell says. Fewer are structured to deliver it. “The harder task is turning that understanding into the way projects are actually set up and managed,” he argues.
Riyadh Metro is the reference point he returns to, precisely because engineering complexity was not the deciding factor in its delivery.
Coordinating a city-scale transport system meant aligning design, construction, systems, utilities and stakeholder interfaces across every delivery vertical.
“The lesson for the region today is clear,” Caldwell says. “Ambitious programmes need a delivery model that gives every contributor a shared view of progress, risk, decision-making and the business case driving programme priorities.”
That shared view, he argues, will be what the next phase of Gulf delivery is judged on.
Whether clients, consultants, contractors, operators and approval authorities can work to a single delivery logic will be key.
“This requires more than coordination meetings. It requires integrated ways of working, shared common data environments and governance structures that make risks, decisions and dependencies visible before they become delays,” he says.
From reporting progress to managing risk before it lands
Digital tools have a role here, Caldwell says, but not as a headline in themselves.
Digital twins, programme visualisation and data-led modelling matter only if they help teams identify and address problems before they affect the wider programme.
“The real value is not technology for its own sake,” he says. “It is the ability to see, in one place, where approvals are outstanding, where interfaces are unresolved, where programme dates are slipping, where clashes are emerging and where decisions need to be escalated."
None of it works without governance behind it, he cautions. “A dashboard will not resolve a delayed approval if nobody knows who owns the decision, when it needs to be made, or how it should be escalated.”
Data only has value if the processes and responsibilities around it are clear, which is why Caldwell frames the shift the region needs not as digitisation, but as a move “from programme management as a discipline focused mainly on reporting and coordination, and towards project and programme intelligence”.
With many of the region’s programmes running for a decade or more, he adds, delivery models also need to flex as funding assumptions, user needs and policy priorities change along the way.
“The ambition behind the Gulf’s transformation programmes is not in question,” Caldwell says.
What will determine how much of it is realised on time is whether delivery models evolve at the same pace: earlier integration, clearer approval pathways, shared data environments, and every contributor working to a delivery logic that connects technical sequencing with the funding and operational case behind it.
“The region’s next challenge is not imagining bigger projects,” he says. “It is changing the way they are delivered, operated and adapted over time.”
https://image.digitalinsightresearch.in/uploads/NewsArticle/19502016/main.gif -
Qatari firm wins $221m Qiddiya stadium MEP deal
9 September 2026
Register for MEED’s 14-day trial access
Qatari contractor Elegancia MEP, part of Estithmar Holding, has won a SR829m ($221m) mechanical package contract for the Prince Mohammed Bin Salman Stadium in Qiddiya, Saudi Arabia.
The contract covers full mechanical, electrical and plumbing (MEP) works for the stadium, and is Elegancia MEP’s largest award in Saudi Arabia to date.
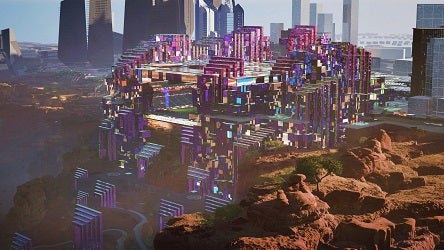
The 45,000-seat stadium will feature a fully combined retractable pitch, roof and LED wall.
The stadium’s main construction works are being undertaken by a joint venture of Spanish firm FCC Construction and local firm Nesma & Partners.
Saudi gigaproject developer Qiddiya Investment Company awarded an estimated SR15bn ($4bn) deal to build the stadium in October 2024, as MEED exclusively reported.
The contract covered the construction of a multipurpose stadium on top of the 200-metre-high Tuwaiq cliff in the new sports and entertainment district of Qiddiya City.
Once completed, the stadium will be the home ground for Saudi Pro League football clubs Al-Nassr and Al-Hilal.
US-based architect Populous is the project consultant.
The stadium is one of the venues for the kingdom’s 2034 Fifa World Cup bid and will host events such as the Saudi King Cup, the Asian Cup and the 2034 Asian Games.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19501493/main.jpg -
Jordan tenders advisory for wastewater treatment plant
9 September 2026
The Water Authority Jordan (WAJ) has issued an invitation to prequalify for advisory services for the rehabilitation and expansion of the Shallala wastewater treatment plant in Irbid, northern Jordan.
The Shallala plant was commissioned in 2013 with a design capacity of about 14,000 cubic metres a day (cm/d).
The rehabilitation and expansion project will increase its treatment capacity to about 30,500 cm/d to meet projected wastewater flows through 2050.
The PIU Support and Construction Supervision Consultancy Services tender was released on 19 August.
The submission deadline is 21 September.
The consultancy will support the project implementation unit and provide construction supervision services for the project. The project has an estimated value of $69m and is being financed by the European Bank for Reconstruction and Development.
The planned works include rehabilitating the existing activated sludge and treatment units and constructing a new treatment train.
The scope also includes installing biogas combined heat and power units, improving sludge handling and dewatering systems, and installing odour control and chemical containment systems.
WAJ is also undertaking the upgrade and expansion of the Ain Ghazal wastewater treatment plant in Amman.
The existing facility had a capacity of 330,000 cm/d and is being upgraded to 726,712 cm/d to accept and treat expected incoming flows until 2045.
The local Arab Towers Contracting Company was appointed as the main contractor for the project last year.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19498520/main.jpg -
Consultants bid for Abu Dhabi light rail project management
9 September 2026
Register for MEED’s 14-day trial access
Abu Dhabi Transport Company (ADTC) has issued a request for prequalification (RFQ) notice to consultants for a contract for project management engineering consultancy services for the first phase of the light rail transit network, also known as ADT4.
The notice was issued on 7 September, with a submission deadline of 9 November.
The project’s first phase will span 19 kilometres (km) and include 23 stations, connecting Zayed International airport (AUH) with nearby areas, including Yas Island, Al‑Raha Beach and Khalifa City.
The key sections of the tram are:
AUH to Yas Island: The tram will start from Terminal A at AUH and run through the Yas tunnel to Yas Gateway Park. It will serve areas including Yas Bay, Media Zone, Yas Plaza, Yas Drive, Yas Mall, Sea World and Water Edge.
This section covers 13km and includes 13 at-grade stations and one underground station.
Al-Raha: This section will stretch for 4.3km and run along Al-Raha Street. It will serve areas including Al-Zeina, Al-Muneera and Al-Bandar, towards the Aldar head office. The section will include seven at-grade stations.
Etihad Plaza: This section will pass the Etihad Aviation Training Centre and span about 1.7km. It will feature a main depot near the Etihad Airways headquarters, along with two at-grade stations.
The tender also covers the procurement of 25 trams, each with a capacity of 270 people, along with associated systems.
The project was officially launched at the GlobalRail exhibition in Abu Dhabi in October last year.
Referred to as Abu Dhabi Tram Line 4, the project will be delivered in three phases.
Construction of the first phase is expected to start next year. The tram is slated to begin operations by 2030.
Future phases will extend towards Khalifa City and serve additional destinations across Yas Island.
The project forms a key part of the recently announced AED170bn ($46bn) package of national transport and road projects to be implemented by 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19493532/main.jpg