Oil and gas faces pressing need to decarbonise
27 October 2023

This report on carbon capture also includes: Bright outlook for carbon capture investment
Greenhouse gas (GHG) emissions generated by oil and gas operations – also known as Scope 1 and 2 emissions – accounted for 15 per cent of the total energy-related emissions worldwide in 2022.
A further 40 per cent of the energy-related emissions came from the consumption of oil and gas for power generation, heating, vehicle fuel and industrial processes, also known as Scope 3 emissions.
Against this backdrop, developed countries are aiming to achieve net-zero emissions by 2050, while developing countries like China and India are aiming for 2060 and 2070, respectively. Such targets mean the carbon-intensive oil and gas industry has come under significant pressure to reduce its carbon footprint.
However, increased investment and new regulations are needed to effectively drive carbon-cutting measures and lower emissions, according to a report by GlobalData.
“To support global commitments towards climate change, countries and regulatory bodies have started introducing emissions trading systems or enhancing existing ones,” says Barbara Monterrubio, managing analyst for energy transition at GlobalData. “This is pushing companies to strengthen internal targets and diversify their portfolios into clean and sustainable products and technologies.”
 Tackling emissions
Most national oil companies in the Gulf have announced net-zero emissions targets. Saudi Arabia aims to reach net zero by 2060 through the circular carbon economy approach, while Saudi Aramco aims to be carbon neutral by 2050.
Abu Dhabi National Oil Company (Adnoc) has adopted a plan to achieve net zero by 2045 and to reach zero methane emissions by 2030. The company’s methane intensity was about 0.07 per cent last year.
Adnoc also achieved GHG emission reductions of about 4 million tonnes in 2022 by using grid energy from solar and nuclear power to supply 100 per cent of its onshore operations, as well as about 1 million tonnes from energy-efficiency and flaring reduction projects.
Qatar has set a goal to reduce its GHG emissions by 25 per cent by 2030. State enterprise QatarEnergy has been tasked with achieving a net carbon intensity reduction of 15 per cent from upstream operations and about 25 per cent from its liquefied natural gas facilities by 2030.
QatarEnergy also has targets of 0.2 per cent methane intensity by 2025 and zero routine flaring by 2030.
Bahrain’s state energy holding company Bapco Energies has listed its Scope 1 and 2 net emissions intensity reduction targets as 15 per cent by 2025, 25 per cent by 2030, 30 per cent by 2035, 50 per cent by 2040, 75 per cent by 2050 and net zero by 2060. It has committed to cut Scope 3 emissions within Bahrain by 30 per cent by 2035 and reach net zero by 2060.
“Switching to low carbon products is a long-term process, with many oil and gas majors in the early stages of their energy transition strategy,” says Monterrubio. “A combination of well-designed regulations as well as huge investments are needed to tackle emissions and support low-carbon industry.”
Ravindra Puranik, oil and gas analyst at GlobalData, adds: “Oil and gas companies are currently working to reduce Scope 1 and 2 emissions generated by their operations. Several leading companies have set themselves the target to reach operational net-zero emissions by 2050.
“To achieve this, companies are focusing on adopting new technologies, such as low-carbon hydrogen and carbon capture and storage; and making other operational changes like building renewable energy and biofuels capacities.”
Carbon capture campaign
Carbon capture and storage (CCS) involves the separation of carbon dioxide from a gas stream in industrial processes through technologies such as chemical absorption or physical separation. The carbon dioxide is then transported and stored through injection into deep underground rock formations, usually at depths of 1 kilometre or more.
Further to this, rather than simply storing the captured carbon dioxide, after transportation it can be used for a variety of industrial processes. This is referred to as carbon capture, utilisation and storage (CCUS).
One application for captured carbon dioxide is enhanced oil recovery. Injecting the carbon dioxide into depleted oil reservoirs not only helps to push oil to the surface, but also keeps the carbon locked underground.
CCUS will be important in lowering emissions in sectors where a complete eradication is not possible. As one of the largest emitters of carbon dioxide, the oil and gas industry needs to be at the forefront of driving CCS and CCUS activities.
The International Energy Agency (IEA) estimates that in order to achieve net-zero emissions by 2050, CCUS capacity will have to increase more than 40 times by 2030. This will require capacity to increase by 50 per cent every year.
According to IEA data, there were a total of 13 CCUS projects planned or operational in the GCC region as of March 2023, with total capture capacity estimated at 20 million tonnes a year of carbon dioxide. The region’s energy producers account for the majority of these planned CCUS investments.
 Bright outlook for carbon capture investment

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Neom’s industrial pivot gathers pace
1 October 2026
-
 Contractor wins Dammam airport water infrastructure deal
1 October 2026
-
 Kuwait tenders LNG project
1 October 2026
-
 Riyadh approaches contractors for 2km tower
1 October 2026
-
 Aldar and Arada to pursue Abu Dhabi projects
1 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Neom’s industrial pivot gathers pace
1 October 2026
 Commentary
Colin Foreman
EditorReprioritisation has been the buzzword in Saudi Arabia over the past two years and nowhere has that been more evident than at Neom.
 The slowdown of development at The Line and the postponement of the 2029 Asian Winter Games at Trojena have dominated international headlines. As these projects scale back, Oxagon’s industrial and logistics base has become the $500bn gigaproject’s flagship development. There are tangible results: in August, the $8.5bn Neom Green Hydrogen project was commissioned, marking Neom’s most significant completion to date.
Construction activity elsewhere at Oxagon supports this trend. The AI data-centre campus being developed by Humain and DataVolt has broken ground on its first 100MW phase, backed by $5bn of investment and targeted for service in 2028. Neom has issued an expression of interest for a rail line linking the Port of Neom to Saudi Arabia Railways’ North-South network, tenders are out for an industrial wastewater plant and the upgrade of Highway 55, and the port itself is advancing towards a 2030 capacity target of 1.5 million TEUs.
The regional conflict that began in February has strengthened the business case by giving Oxagon’s Red Sea port added strategic weight as a second maritime gateway outside the Strait of Hormuz, at a time when Riyadh has committed to directing about 80% of the Public Investment Fund’s portfolio into domestic investment.
These developments reflect a kingdom recalibrating rather than retreating
Elsewhere, Saudi Arabia’s wider projects market is holding steady despite conflict-related disruption, with contract awards reaching $68bn so far this year. The regional power market is also diversifying, with Aljomaih, EDF and Kepco all more than tripling net capacity in recent years as Acwa retains its lead.
These developments reflect a kingdom recalibrating rather than retreating, with priority given to projects capable of delivering commercial returns.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20178338/main.gif -
Contractor wins Dammam airport water infrastructure deal
1 October 2026
Saudi Arabia-based Alkhorayef Water & Power Technologies has won an SR80m ($21.3m) contract to rehabilitate water and wastewater infrastructure at King Fahd International airport in Dammam in the kingdom’s Eastern Province.
The contract was awarded by Dammam Airports Company (DACO), and work is scheduled to be completed within 18 months, the firm said in a disclosure to the Saudi Exchange (Tadawul) on 29 September.
The scope covers the design, construction, supply, installation, replacement, rehabilitation and integration of water and wastewater infrastructure.
It includes pumps, storage tanks and reservoirs, reverse osmosis facilities, piping and tie-ins, as well as electrical and instrumentation works.
The award comes as DACO advances a wider programme of investment at King Fahd International airport.
DACO signed more than SR1.2bn ($320m) in agreements in June covering airport infrastructure, including a new power station, a medium-voltage distribution network and upgrades to the existing electrical grid.
In September, it also appointed WSP Middle East, the regional arm of Canadian engineering firm WSP, to develop the airport’s expansion under its masterplan.
The expansion is intended to increase annual passenger capacity to more than 19.3 million by 2030, with a longer-term target of 32 million passengers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20169118/main.jpg -
Kuwait tenders LNG project
1 October 2026
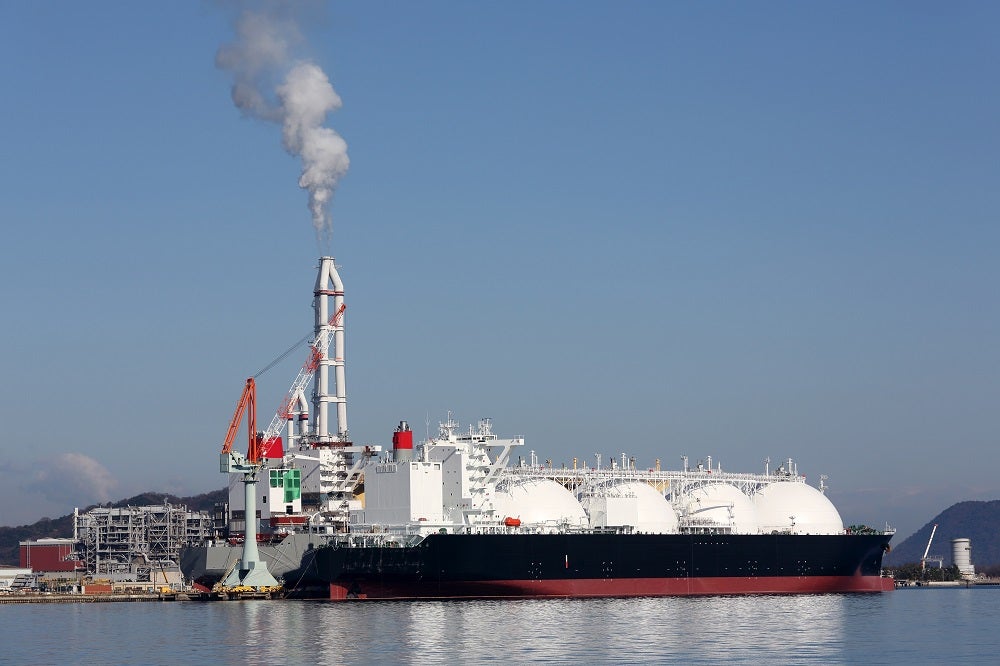
State-owned Kuwait Integrated Petroleum Industries Company (Kipic) has tendered a project to develop a reliquefaction unit at the Al-Zour liquefied natural gas (LNG) import terminal.
The project focuses on developing a boil-off gas (BOG) unit at the terminal, with bids due on 22 December.
A meeting for contractors to discuss the project is scheduled for 18 October.
The project scope includes engineering, procurement and construction works, along with pre-commissioning, commissioning and performance testing services.
The list of prequalified companies is:
- Fluor (US)
- GS Engineering & Construction (South Korea)
- Tecnicas Reunidas (Spain)
- Larsen & Toubro (India)
- Hyundai Engineering (South Korea)
- CTCI Corporation (Taiwan)
- Daewoo Engineering & Construction (South Korea)
- Hyundai Engineering & Construction (South Korea)
- Saipem (Italy)
- Samsung Engineering (South Korea)
- Sinopec Engineering (China)
- JGC Holdings (Japan)
- KBR (US)
- China National Petroleum Corporation (China)
- Technip (France)
A BOG unit at an LNG facility captures, compresses and processes natural gas vapours that evaporate from cryogenic storage tanks, enabling the gas to be recycled back into the system rather than flared.
In April, MEED revealed that contractors expected the project to be worth about $200m.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20168625/main2005.jpg -
Riyadh approaches contractors for 2km tower
1 October 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Public Investment Fund (PIF) has reached out to contractors as part of a market-sounding exercise for the construction of the proposed 2-kilometre megatall tower project.
MEED understands that a PIF subsidiary, the Tower District Real Estate Development Company, is undertaking the process.
It is understood that several experienced international contractors, as well as some prominent local contractors, have been approached.
The latest development follows PIF receiving offers in June last year from firms seeking a contract to provide project management consultancy (PMC) services for a new central business district (CBD) on the outskirts of Riyadh, which includes the proposed 2km tower.
The PMC role covers both the tower and the surrounding district.
Firms understood to have been invited to bid include US-based Aecom, Jacobs, Parsons and Turner, as well as the UK’s Mace.
UK-based Foster & Partners is working as the architect for the tower after winning a design competition launched in late 2022.
Record breaker
The proposed tower would be more than double the height of the world’s tallest building, Dubai’s Burj Khalifa, which stands 828 metres tall. It is expected to be at least several hundred metres taller than the 1,000-metre-plus tower under construction in Jeddah.
Contractors that have priced megatall towers in the region say a 2km-tall structure could cost about $5bn to construct, depending on the final design.
The 2km tower and the surrounding CBD – known as Project Rise – sit within a larger masterplanned development to the north of Riyadh called the North Pole.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20156496/main.jpg -
 Singapore’s Temasek plans Middle East expansion
1 October 2026
Singapore’s Temasek plans to open offices in Riyadh and Abu Dhabi early next year as it targets investment and partnership opportunities in Saudi Arabia, the UAE, Qatar and the wider region.
The state-owned investor had a net portfolio value of S$518bn ($401bn) as of 31 March 2026.
It said the new offices will serve as regional hubs for Temasek and its portfolio companies, with some businesses expected to co-locate to work more closely with partners and pursue deals alongside the group. The openings are subject to regulatory approvals.
Temasek said it will also step up engagement with institutions in Qatar, although it has not announced plans to establish an office there.
The company said the expansion reflects its confidence in the region’s long-term fundamentals and the economic transformation being driven by national diversification programmes.
It added that a presence in Riyadh and Abu Dhabi will also support investment activity beyond the region by improving access to opportunities across the wider Middle East, Central Asia and Africa.
Several Temasek-owned or Temasek-backed companies are already active in the GCC, providing a platform for the group’s planned expansion.
These include Singapore-headquartered engineering and consultancy firm Surbana Jurong, which has been involved in masterplanning and advisory work on major regional developments, alongside other portfolio companies with interests spanning infrastructure, logistics, financial services and technology.
According to data from regional project tracker MEED Projects, Surbana Jurong is involved in several major projects in Saudi Arabia, including King Abdulaziz International airport (KAIA) in Jeddah, Jeddah Islamic Port, Red Sea Global’s Amaala masterplan, the Trojena dams scheme, Oxagon, King Salman International airport and Saudi Arabia Railway’s North-South Phosphate Railway 3.
The firm has also worked on projects in the wider region, including the West Link project, Urban Loop, Musaffah Innovation District masterplan, Etihad Rail’s high-speed rail programme and Abu Dhabi airport’s Midfield Terminal.
Surbana Jurong has also secured masterplanning contracts from Abu Dhabi’s Department of Municipalities & Transport and Abu Dhabi Ports.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20157511/main.jpg