No end in sight for Lebanon’s economic woes
12 June 2023
 This package on Lebanon also includes:
> Political deadlock in Lebanon blocks reforms
> Lebanon moves to secure $150m solar financing
> Dar al-Handasah acquires Turkish consultant
> Eni and Total complete Lebanon gas deal
Experts remain pessimistic about the outlook for Lebanon’s economy as the crisis continues to worsen more than three years after it began in 2019.
The country only has a caretaker government and no president – and it is hard to see how it will implement the reforms the IMF says are needed.
On 8 June, IMF spokesperson Julie Kozack said: “Lebanon needs urgent action to implement a comprehensive economic reform programme to arrest the severe and deepening crisis and to allow Lebanon’s economy to recover.”
She added that the IMF was concerned that delays in implementing key reforms were keeping the economy severely depressed.
“We are concerned about irreversible consequences for the economy, especially for the poor citizens of Lebanon and the middle class,” she said.
Lebanon’s currency has weakened dramatically since the start of the country’s economic crisis, plunging much of the population into poverty.
In March, the Lebanese pound, officially pegged at 15,000 to the dollar, was trading at 100,000 against the dollar on the country’s parallel market, down from 1,507 before the economic crisis hit in 2019.
In May, a World Bank report stated: “The systemic failure of Lebanon’s banking system and the collapse of the currency have resulted in a large, dollarised cash-based economy.
“It not only threatens to compromise the effectiveness of fiscal and monetary policy, but also heightens the risk of money laundering, increases informality and prompts further tax evasion.”
In April 2020, the Lebanese government agreed with IMF staff to implement a series of reforms to end the crisis, but very few have been executed.
This is mainly due to the country’s ongoing political deadlock.
Lebanon has had no head of state since President Michel Aoun’s term ended at the end of October 2022, worsening the country’s political paralysis at a time when important policy decisions are needed to get the economy back on track.
According to the IMF, the economic outlook for Lebanon is highly uncertain and depends on policy actions taken by the authorities to carry out the agreed reforms.
Kozack said: “Timely implementation of these reforms is critical to end the current crisis and prevent a further deterioration in living standards of the people of Lebanon.”
She added: “Lebanon will need strong financial support from the broader international community and the financial needs of Lebanon over the next several years are very large given the magnitude of the economic crisis.”
Bailout prospects
While the IMF has said that Lebanon will need significant financial support from other countries to help it get through its economic crisis, it is unclear where that support will come from.
Nicholas Blanford, a non-resident senior fellow with the Atlantic Council’s Middle East programmes, says it is unlikely that Saudi Arabia will be willing to bail the country out financially as it has done in the past.
He said: “Saudi Arabia has pumped billions of dollars into Lebanon over the years, including helping with the reconstruction programme in the 1990s after the civil war. Saudi has also helped Lebanon financially through various economic slumps.”
The change of leadership in Saudi Arabia when King Salman came to the throne in 2015 led to a change in policy regarding financial bailouts for Lebanon, according to Blanford.
“It seems like Saudi feels that it got very little in return for its past investment in Lebanon due to the fact that Hezbollah remains a dominant force in the country politically and militarily.
“The Americans and the French have, for several years, been pressing the Saudis to show more interest in Lebanon as a pushback against Iranian influence, but, so far, they haven’t shown much interest.”
The Lebanese are keeping their fingers crossed that economically viable quantities of oil and gas are found, but there is also a huge amount of scepticism given the state of the political system here and the nature of the politicians
Nicholas Blanford, Atlantic Council’s Middle East programmes
In October last year, Lebanon and Israel agreed a deal to end a long-running maritime border dispute in the Mediterranean Sea, clearing the way for increased oil and gas exploration activity in Lebanese waters.
Following the deal, in May this year, it was announced that a consortium led by France’s TotalEnergies would start drilling for oil and gas off the country's coast at the beginning of September.
While it is possible that new hydrocarbon discoveries in Lebanese waters could help ease the country’s economic problems over the long term, it is doubtful that this would provide any benefit in the short term, according to Blanford.
“The Lebanese are keeping their fingers crossed that economically viable quantities of oil and gas are found, but there is also a huge amount of scepticism given the state of the political system here and the nature of the politicians themselves.”
Blanford believes that many Lebanese citizens are worried that if commercially viable quantities of hydrocarbons are found, they are ultimately only likely to benefit the country’s oligarchs rather than the general public.
Due to the wide range of severe political and economic problems that Lebanon faces, there is unlikely to be any improvement over the coming months unless common ground is found between the country’s rival political blocs.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026
-
 Hormuz crisis sparks regional pipeline project boom
11 November 2026
-
 Saudi Arabia approves revival of Iraq oil pipeline
11 November 2026
-
 Dubai approves metro extension to Al-Maktoum airport
10 November 2026
-
 Bahrain tenders 100MW Bilaj Al-Jazayer solar project
10 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Riyadh shifts bid deadline for King Salman Stadium works
11 November 2026

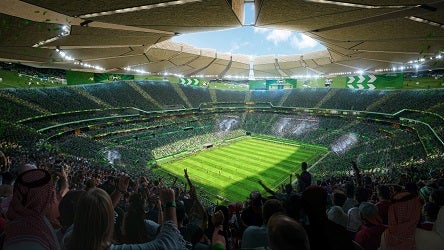
Saudi Arabia’s Sports Ministry has set a deadline of 1 December for a contract covering early works at the King Salman International Stadium in Riyadh.
The tender scope encompasses enabling works, site preparation and initial construction activities. The tender was issued on 11 October, carrying an initial submission deadline of 19 November. Contractors previously submitted prequalification statements for the main design-and-build contract in February.
Designed by US-based architectural firm Populous, the stadium will cover approximately 660,000 square metres (sq m), seat 92,000 spectators and stand adjacent to King Abdulaziz Park. Facilities will feature a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The broader masterplan encompasses more than 360,000 sq m of ancillary facilities, featuring two training fields, fan zones, a closed sports hall, an Olympic-sized swimming pool, an athletics track, and outdoor courts for volleyball, basketball and padel.
Scheduled for completion by 2029, the venue will serve as the home base for the Saudi national football team and host the opening match and final of the 2034 Fifa World Cup.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia plans to build 11 new stadiums and refurbish four existing venues for the 2034 tournament. Eight venues will be located in Riyadh, four in Jeddah, and one each in Al-Khobar, Abha and Neom.
An additional 10 cities will host team base camps: Al-Baha, Jazan, Taif, Medina, AlUla, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah. Across the kingdom, organisers plan to deploy 134 training sites, comprising 61 existing facilities and 73 new builds.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of member associations at the Fifa Congress on 11 December 2024.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21325461/main.jpg -
Hormuz crisis sparks regional pipeline project boom
11 November 2026
 Analysis
Wil Crisp
Oil & gas reporterRegister for MEED’s 14-day trial access
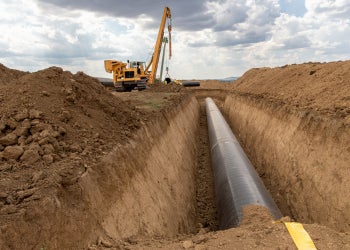
The ongoing disruption to shipping through the Strait of Hormuz and the Bab Al-Mandab Strait has sparked a regional pipeline project boom, as countries seek to diversify export routes for oil and gas.
Since the US and Israel attacked Iran on 28 February, several major pipeline projects have been announced, while others are being revived or accelerated.
Countries that are participating in this regional pipeline boom include Iraq, Syria and Egypt.
While the regional conflict has changed the dynamics within the oil and gas sectors of each of these countries in different ways, all of them see major pipeline projects as a key part of their strategic response to the conflict.
Iraqi expansion
Iraq is one of the region’s oil exporters that has been hit the hardest by the disruption to shipping through the Strait of Hormuz.
Prior to the start of the regional conflict, the country was routing 94% of its total exports through the strait, with about 3.4 million barrels a day (b/d) being exported through its southern ports at the start of the year.
At the same time, about 200,000 b/d was being exported via the Iraq-Turkiye Pipeline (ITP) in the north of the country.
In the wake of the disruption to shipping through the Strait of Hormuz, Iraq has increased the volumes being exported via the ITP and has boosted its crude exports by truck through Syria.
Earlier this month, domestic news outlets reported that Iraq’s State Oil Marketing Organisation is exporting 500,000 b/d through the ITP.
The daily exports consist of 125,000 barrels of Kirkuk crude, 175,000-200,000 barrels of Kurdistan Region crude and about 200,000 barrels of Basra crude, according to the reports.
The Basra oil reaches collection stations at Sarallu and Khurmala by truck and from there is pumped north to Ceyhan in Turkiye.
The volume of crude exported from Iraq by truck to the Syrian port of Baniyas has risen significantly in recent months.
In October, Youssef Qablawi, the chief executive of the state-owned Syrian Petroleum Company, said that about 1,000 trucks were transporting fuel oil to Syria each day, with each truck carrying about 220 barrels.
This represents exports of 220,000 b/d, which is a significant volume for Iraq, but transporting crude by truck is much more expensive than using a pipeline.
Because of this, Iraq sees pipeline projects as a long-term solution to its reliance on the Strait of Hormuz and is rapidly pushing ahead with projects that are designed to replace exports currently transported by road, as well as increasing the volumes that can be exported via both Syria and Turkiye.
Earlier this month, MEED reported that the governments of Iraq and Syria, state-owned oil companies and a consortium led by Qatar’s UCC are currently discussing the terms of a deal for four interconnected pipeline packages that are expected to have a total value of about $5bn.
Stakeholders expect a contract to be signed before the end of the year that will make the UCC-led coalition the selected developer responsible for tendering engineering, procurement and construction (EPC) contracts for the project.
The consortium includes US-based Chevron, investment company TI Capital and France’s TotalEnergies.
The four pipeline routes that are being discussed are:
- Basra to Najaf
- Najaf to Haditha
- Haditha to Fish Khapour
- Haditha to Banias Port in Syria
The proposed plan will use a fast-track framework to bring the pipelines online as quickly as possible.
Red Sea route
Iraq and Saudi Arabia are also considering reviving an old pipeline route between the Zubair oil field in Basra and the Red Sea port of Yanbu.
Operations of this 1,568-kilometre (km) pipeline were halted in August 1990 following Iraq's invasion of Kuwait and the onset of the Gulf War.
At the end of October, Saudi Arabia granted preliminary approval to revive the joint oil export pipeline project, according to a report published by Saudi Arabia’s Shafaq News, which cited anonymous sources.
If the pipeline is reinstated, it could allow Iraq to export oil via the Red Sea, reducing its reliance on the Strait of Hormuz.
The pipeline was originally built at a cost of more than $2.6bn and featured a large network of storage tanks and offshore loading terminals.
Syrian strategy
In addition to its involvement in Iraq’s strategic export pipeline project, Qatar’s UCC is developing a pipeline project in Syria that will increase the country’s ability to deal with future supply disruptions.
On 30 September, UCC announced that it has , which will extend 186km between Homs and Aleppo.
The 36-inch pipeline will have a transmission capacity of up to 11 million cubic metres a day (cm/d) of gas and will connect gas networks in Jordan to those in Turkiye via Syria.
In its announcement, UCC said that the project is scheduled for completion within 22 months and will contribute to strengthening Syria’s gas infrastructure; enhancing the capacity of its gas transmission network; and supporting regional connectivity with Jordan, Turkiye and Lebanon.
Hisham Al-Saleh, Syrian Petroleum Company’s deputy chief executive for the gas sector, has said that the project includes the installation of three compressors in Furqlus, which will allow gas to be transported in both directions between Turkiye and Jordan.
Speaking to the state-owned Syrian Arab News Agency, he said that the project will add an estimated 8 million cubic metres of storage capacity to the Syrian gas network, providing greater flexibility in managing gas production and use.
Egyptian ambitions
Egypt is also ramping up pipeline project activity in order to increase the number of oil and gas links that it has with neighbouring countries.
The North African nation has long had ambitions to try and become a major regional energy hub.
These plans have been given a boost by the ongoing disruption to shipping through the Strait of Hormuz and the Bab Al-Mandab Strait, which has reduced exports from nations like Qatar, Kuwait, Iraq, the UAE and Saudi Arabia.
Concerns about the reliability of exports from Iraq and the GCC have led to increased investment in oil and gas infrastructure in countries that are not reliant on these waterways to transport hydrocarbons.
In recent months, significant progress has been made on an integrated project that was launched in order to export offshore gas reserves in Cyprus via Egyptian energy infrastructure.
In October, Italian oil and gas company Eni signed the main EPC and drilling contracts for the project, which will develop the Cronos field.
The project includes contracts with several companies that will develop infrastructure in both Egypt and Cyprus.
The awards include a $170m contract that has been won by Egypt’s Petrojet for a new onshore gas pipeline in Egypt that will help to transport gas to Egypt’s Damietta liquefied natural gas (LNG) facility.
Separately, US-based Baker Hughes signed a contract for the design, procurement and construction of subsea production systems, including associated equipment and control systems.
In September, it was announced that US-headquartered McDermott will carry out offshore work for the project, including the transportation, installation and connection of subsea pipelines and equipment.
The Cronos development project will significantly increase the volume of gas being imported into Egypt, where it can be exported as LNG as well as helping to meet domestic demand.
On top of the major pipeline project allowing the importation of gas from Cyprus, Cairo is also looking at other regional pipeline projects, including gas links to Libya.
In a statement released earlier this month, Egyptian Foreign Minister Badr Abdelatty said that a Libyan team will visit Cairo soon to continue technical talks about the gas pipelines, as well as other energy projects, with Egypt’s petroleum and electricity ministers.
Pipeline problems
While the planned oil pipeline projects in Iraq are seen as a possible solution to the disruption to shipping through the Strait of Hormuz, they are also likely to face problems relating to the importation of necessary equipment that would normally be shipped through the waterway.
The Common Seawater Supply Project, designed to bring water from the sea to inject into oil fields, is currently behind schedule, largely because of problems importing the pipeline segments through the strait.
This issue could plague other planned pipeline projects in Iraq if the disruption to shipping continues, forcing contractors to use other, more costly, import routes.
Challenging conditions
Even when Iraq’s major export pipeline projects are completed, they may fail to resolve the country’s oil export problems to the extent many are expecting.
While the export pipelines will go some way towards diversifying away from reliance on exports through waterways where oil and gas tankers are vulnerable to militant attacks, many industry insiders say Iraq could just be replacing one vulnerable export route with another.
Oil pipelines in the Middle East and North Africa region have a long history of suffering attacks and often stretch long distances through remote regions where they are difficult to defend.
Ultimately, it is likely that finding a diplomatic solution to the regional conflict will be the only way that Iraq can reliably increase its oil exports in the long term.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21305172/main.jpg -
Saudi Arabia approves revival of Iraq oil pipeline
11 November 2026
Register for MEED’s 14-day trial access
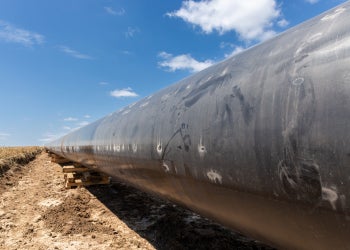
Iraq and Saudi Arabia are considering reviving an old pipeline route between the Zubair oil field in Basra and Saudi Arabia’s Red Sea port of Yanbu.
Operations of this 1,568-kilometre (km) pipeline were halted in August 1990 following Iraq’s invasion of Kuwait and the onset of the Gulf War.
At the end of last month, Saudi Arabia granted preliminary approval to revive the joint oil export pipeline, according to a report published by Saudi Arabia’s Shafaq News that cited anonymous sources.
If the pipeline is reinstated, it could allow Iraq to export oil via the Red Sea, reducing its reliance on the Strait of Hormuz.
The pipeline was originally built at a cost of more than $2.6bn and featured a large network of storage tanks and offshore loading terminals.
Under current discussions, Iraq will be required to fund the restoration of its own section of the pipeline.
The Middle East and North Africa region is currently experiencing a boom in pipeline project activity due to disruption to shipping as a result of the war that started when the US and Israel attacked Iran on 28 February 2026.
As a result of the conflict, the shipping of gas, chemicals, oil and refined products has been disrupted in both the Strait of Hormuz and the Bab Al-Mandab Strait.
Many countries, including Saudi Arabia and Iraq, see pipelines as a key way of diversifying export routes so that they are less reliant on shipping through these two waterways.
MEED’s October 2026 report on Saudi Arabia includes:
> COMMENT: Saudi projects hold steady
> GOVERNMENT: Riyadh looks to reset its regional defence outlook
> ECONOMY: Conflict bolsters case for Saudi economic diversification
> BANKING: Saudi lenders readjust to lower lending and deposit climate
> UPSTREAM: Aramco upstream spending gathers pace
> DOWNSTREAM: Sabic steps up Saudi petchems investment
> POWER: Saudi Arabia’s power award activity slows
> WATER: Saudi water sector hits sharp slowdown
> CONSTRUCTION: Saudi construction defies the headwinds
> TRANSPORT: Saudi infrastructure pushes forward amid conflict
> DATABANK: Saudi data indicates project spending shiftTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/21304885/main.jpg -
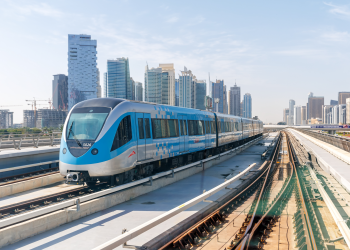
Dubai approves metro extension to Al-Maktoum airport
10 November 2026
Register for MEED’s 14-day trial access
Dubai’s Executive Council has approved a project to extend the Dubai Metro’s Route 2020 to Al-Maktoum International Airport City, with passenger services scheduled to begin operations in 2031.
Sheikh Hamdan bin Mohammed bin Rashid Al-Maktoum, Crown Prince of Dubai, announced the decision following a council meeting held during the UAE Government Annual Meetings 2026.
The rail project forms part of a package of strategic schemes worth over AED11bn ($3bn) approved by the council.
The wider approvals include a comprehensive framework to upgrade community facilities and public services by 2040, with priority given to residential communities for UAE citizens.
حمدان بن محمد يترأس اجتماع المجلس التنفيذي لإمارة دبي ضمن الاجتماعات السنوية لحكومة دولة الإمارات، ويعتمد خلاله موازنة بقيمة أكثر من 11 مليار درهم لمشاريع استراتيجية جديدة في دبي، وخطة شاملة لتطوير الخدمات والمرافق المجتمعية، ومشروع امتداد مترو دبي إلى مطار آل مكتوم الدولي، كما أعتمد سموه خلال الاجتماع نتائج دراسة مستقبل السوق العقاري في دبي.
— Dubai Media Office (@DXBMediaOffice) November 10, 2026
The project approval follows the procurement of detailed design work for the rail link. MEED exclusively reported in September that Dubai’s Roads & Transport Authority (RTA) had awarded US-based engineering consultancy Aecom the design contract for the Route 2020 extension.
The planned extension will run for about 3 kilometres from the existing Expo 2020 terminus station to connect directly with the West Terminal of Al-Maktoum International airport. The scheme will add two new stations to the network.
The existing Route 2020 corridor is a 15km spur that branches off the Dubai Metro Red Line at Jebel Ali station. It comprises 11.8km of elevated viaduct and 3.2km of underground track, serving five elevated and two underground stations.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21301168/main.png -
Bahrain tenders 100MW Bilaj Al-Jazayer solar project
10 November 2026
Register for MEED’s 14-day trial access
Bahrain’s Electricity and Water Authority (EWA) has issued a tender for the Bilaj Al-Jazayer independent power project (BAJ solar IPP), a utility-scale solar scheme with a planned capacity of at least 100MW.
The project will be procured on a public-private partnership basis using a build-own-operate (BOO) model.
The selected developer will develop, finance, design, construct, operate, maintain, decommission and restore the project site over a 25-year contract period.
EWA has set a target commercial operation date of 31 December 2028.
The scope includes photovoltaic generation facilities, utility-scale inverters, access roads and internal roads. The plant will use proven photovoltaic modules and inverters designed for Bahrain’s local operating conditions.
The tender was published on 8 November. Companies have until 20 December to submit bids, with bid opening scheduled for 21 December.
The tender requires an initial bond of BD300,000 ($796,000).
The project will be awarded through a single-stage request-for-proposals process.
Bidders will first be assessed against minimum eligibility requirements covering financial strength, project-financing capability and experience in large-scale solar developments before their technical and financial proposals are evaluated.
A single bidder must demonstrate tangible net worth of at least $50m.
In a consortium, each member must demonstrate net worth equivalent to its proposed shareholding in the $50m threshold, while the managing member must have a tangible net worth of at least $20m.
The managing member must also have secured at least $150m of limited-recourse financing across three or more infrastructure projects during the past 10 years. It must hold at least a 15% equity stake in each reference project.
Bidders or their engineering, procurement and construction contractors must demonstrate experience delivering either three grid-connected ground-mounted solar projects of at least 100MWac each globally, or two projects of at least 70MWac each in the GCC. The reference projects must be connected to the grid at 66kV or above.
The BAJ solar IPP supports Bahrain’s target of sourcing 20% of its energy from renewable sources by 2035.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21291585/main.jpg