Muscat performs tricky budget balancing act
12 December 2023

On 11 November, Oman’s Etco Space sent its first nano-satellite, Aman-1, into orbit aboard a SpaceX Falcon 9 rocket launched from California. It is the sort of endeavour Muscat is keen to promote as it tries to diversify its economy.
Etco Space chief executive Abdulaziz Jaafar said his company will be “pushing the boundaries of our space programme in the coming months and years”. It aims to launch more satellites and get involved in deep-space missions.
Oman’s economy needs to find new areas to exploit. GDP growth slowed from 4.3 per cent in 2022 to 1.3 per cent in 2023, according to the Washington-based IMF. The organisation expects the growth rate to revive to 2.7 per cent in 2024, but that is at least partly dependent on a rebound in hydrocarbons production.
This may not come to pass. Oman is part of the wider Opec+ arrangement to curb production and at the group’s meeting on 30 November, Oman agreed to cut 42,000 barrels a day (b/d) from its output during the first quarter of 2024. Opec said the cuts will be gradually unwound later in the year “subject to market conditions”.
Soft oil prices
It is not just about output, however. Oil prices have also been weaker in 2023. The Finance Ministry says Oman received $81 a barrel on average in the first nine months of 2023, compared to $94 in the same period last year.
Caroline Bain, chief commodities economist at Capital Economics, said the Opec+ cuts “should at least act as a floor under prices at current levels, but we would be surprised if it prompted a sustained price rally”.
As it stands, Oman’s net oil revenues were RO4.8bn ($12.5bn) in the first nine months of 2023, 10 per cent lower than a year ago.
Gas revenues have fallen even more significantly – by 42 per cent to RO1.6bn – prompting an overall drop in public revenues of 16 per cent, or RO1.7bn.
Wider market dynamics mean the pressure is likely to continue into 2024. Bhushan Bahree, executive director at S&P Global Commodity Insights, says that crude prices are “under pressure from a looming oil over-supply early next year”, amid strong oil production growth in the Americas.
The economic pressures follow a period of fairly benign conditions. High oil revenues in recent years have enabled Omani authorities to post fiscal and current account surpluses and pay off some sovereign debt.
Such trends have prompted the main credit ratings agencies to issue upgrades. In May 2023, Moody’s Investors Service promoted Oman from Ba3 to Ba2, while both Standard & Poor’s and Fitch Ratings upgraded the sovereign from BB to BB+ in September.
Debt and spending
Government debt rose from just 5 per cent of GDP in 2014 to a peak of 68 per cent in 2020, but since then there has been a concerted effort to reverse that trend. By 2022, it had dropped to 40 per cent of GDP and Fitch predicts it will stabilise at about 35 per cent in 2024-25.
Overall public debt is now at about RO16.3bn, levels last seen in 2018-19.
Despite the lower oil and gas revenues, the government has kept its spending discipline, with expenditure down 14 per cent in the first nine months of the year. This has meant the budget remains in surplus, albeit at lower levels than in 2022. Figures from the Finance Ministry show a surplus of RO791m for the first nine month of 2023, down from RO1.1bn in the same period a year earlier.
In the longer-term, Oman is pinning much of its hopes on hydrogen production. Hydrogen Oman (Hydrom) signed five deals for projects in Duqm in mid-2023, involving total potential investment of $30bn. It is hoping a second round of deals, covering blocks of land in the Dhofar region, could attract a further $20bn-$30bn, with awards due in early 2024.
Hydrom managing director Abdulaziz al-Shidhani has said total investments in the sector could reach $140bn by 2050, by which time the country is hoping to produce 8 million tonnes a year (t/y) of green hydrogen. There is an interim target of 1 million t/y by 2030.
Even if these investment and production targets are achieved, oil and gas will remain central elements of the Omani economy for some time. In a sign of the sector’s continuing importance, the $7bn OQ8 refinery project in Duqm is due to be completed by the end of 2023, with partners OQ and Kuwait Petroleum International aiming to process about 230,000 b/d of oil once it is up and running.
Compared to the undulations in oil and gas and the wider economy, Oman’s political scene is far more stable. Since taking over in 2020, Sultan Haitham bin Tariq al-Said has pushed economic reforms but made few changes on the political side, other than gradually adjusting some of the key personnel. In late October, he appointed new governors to take over in South Al-Batinah, North Al-Sharqiyah and Al-Wusta.
There have also been public protests in Muscat over the Gaza war, but they have been more limited than some other demonstrations in recent years, such as the protests against high unemployment and inflation seen in 2018 and 2019 in cities around the country.
As long as the government can keep the economy relatively stable, it should also be able to maintain the political equilibrium.
MEED's January 2024 special report on Oman also includes:
> BANKING: Omani banks look to projects for growth
> POWER & WATER: Oman expands grid connectivity


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Wison breaks ground on Abu Dhabi’s Habshan train 7
16 November 2026
-
 Meraas launches new Solaya phase in Jumeirah
16 November 2026
-
 Borouge puts butene-1 expansion project on hold
16 November 2026
-
 Contractor wins Saudi Energy substation deal
16 November 2026
-
 WEBINAR: End-of-Year Mena Market Review
13 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Wison breaks ground on Abu Dhabi’s Habshan train 7
16 November 2026
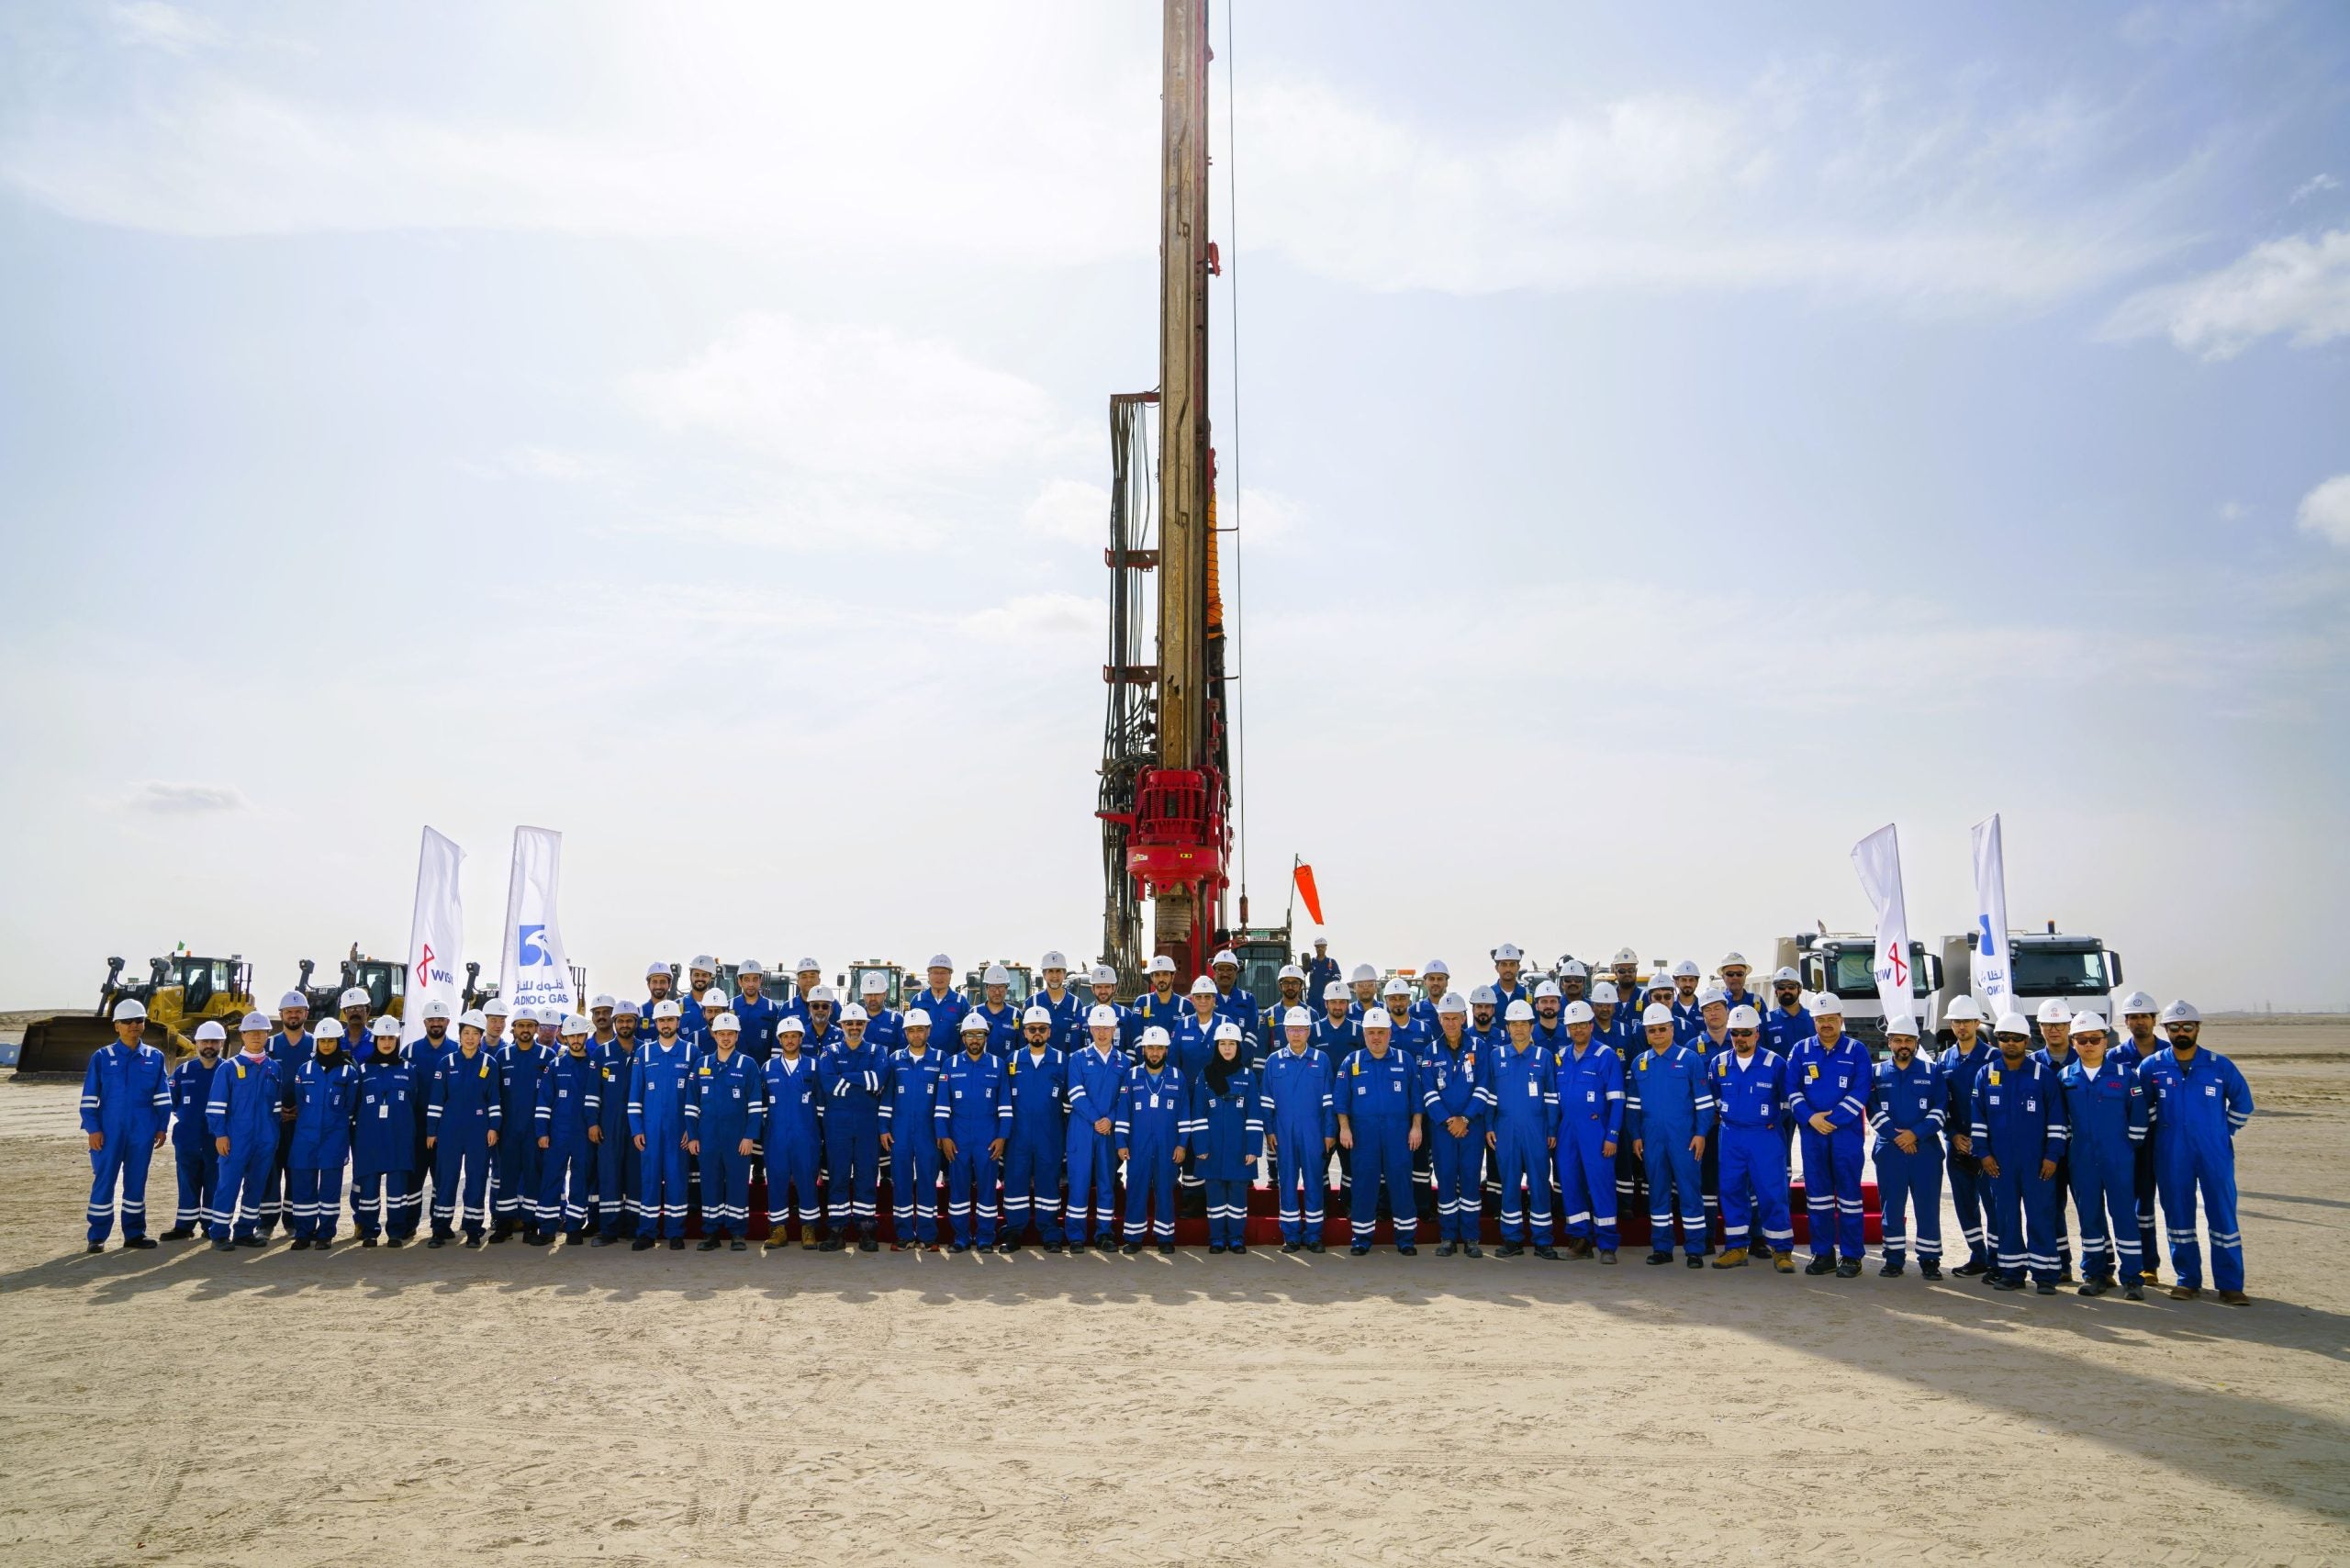
China-based Wison Engineering has held a groundbreaking ceremony for the second phase of Adnoc Gas’ Rich Gas Development (RGD) programme. The project covers the engineering, procurement and construction (EPC) of a seventh gas-processing train at the Habshan complex in Abu Dhabi.
Adnoc Gas, the natural gas processing subsidiary of Abu Dhabi National Oil Company (Adnoc Group), awarded Wison Engineering the $3.9bn EPC contract for the Habshan 7 project in August.
Wison said the RGD phase 2 contract is the largest in its history. Its scope includes gas pipelines, separation and condensate stabilisation units, acid-gas removal units and deep natural gas liquids (NGL) recovery units. The work also includes a 220kV switch station, bringing the total contract value to $4.04bn, according to the Hong Kong-listed contractor.
MEED previously reported that the groundbreaking ceremony for the Habshan 7 project would take place on 11 November.
Adnoc Gas plans to install the Habshan 7 train adjacent to the Habshan 5 train. This arrangement will allow the new train to use spare capacity in Habshan 5’s sulphur recovery and tail-gas treatment units, helping to optimise operations.
The full scope of work on the Habshan 7 gas train project covers the EPC of the following units:
- New high-pressure pipeline from the main Habshan complex to the new gas train
- Separation and condensate stabiliser unit
- Acid gas removal unit
- Mercury removal unit
- Deep NGL recovery unit
- Sales gas and residue gas compressor
- NGL product storage and transfer pump, as well as metering skid
- Utility units (IA, N2, PW, FW, steam generation, DM)
- Flare unit, to be located in Habshan 5 on common derrick
- Flare gas recovery package
- Water treatment package
- Non-process buildings, to be located outside the Habshan 5 train
- Power generation system – associated 220kV switch station
- NGL pipeline from Habshan 5 to Ruwais, based on an existing pipeline assessment
- Sales gas pipeline from Habshan 5 to sales gas network
UK-headquartered Wood Group completed the concept study and initial engineering design for Habshan 7.
Adnoc Gas also broke ground on the third phase of the RGD programme in September. This phase will add a fifth NGL fractionation train at the Ruwais complex. Italian contractor Tecnimont secured the $4.3bn EPC contract for the NGL-5 project in August. Once commissioned, the train is expected to produce more than 8 million tonnes a year of NGLs for export.
The RGD phases, together with the Ruwais liquefied natural gas export terminal, the Maximising Ethane Recovery and Monetisation scheme and the Estidama pipeline expansion, form part of Adnoc Gas’ previously announced $28bn capital expenditure program for 2026-30.
Financial performance
Adnoc Gas posted net income of $1.34bn for the third quarter, doubling its profit from the prior quarter. Revenue momentum and cost controls lifted quarterly ebitda by 70% sequentially to $2.03bn.
Domestic gas sales volumes grew 20% quarter-on-quarter, driving a 28% increase in domestic ebitda. International commercial activities expanded further, with export-traded liquids lifting international product ebitda by 106% sequentially, supplemented by a 249% surge in sulfur margins.
Operating cash flow reached $3.82bn for the first nine months, providing 1.35x coverage for the $2.82bn year-to-date dividend distribution. The board approved a third-quarter dividend of $940m (AED0.18 per share annualised), representing an indicated dividend yield of 5.34% and reinforcing the company’s position as the largest dividend payer on the Abu Dhabi Securities Exchange.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21447026/main00163733.jpg -
Meraas launches new Solaya phase in Jumeirah
16 November 2026
Dubai-based developer Meraas, part of Dubai Holding Real Estate, has launched a new phase of its Solaya beachfront residential scheme in Jumeirah 1. The project is being developed in partnership with BGRE, formerly Brookfield Properties.
The latest release comprises two- to five-bedroom residences, four-bedroom duplexes and a penthouse. In total, Solaya will feature 234 residences across nine buildings on a 40-acre site, offering direct beach access near J1 Beach, landscaped communal areas and private residential amenities.
UK-based Foster + Partners is the project architect, with 1508 London handling interior design. Dubai-based Brewer Smith Brewer Group (BSBG) serves as lead consultant, while US-based Aecom is the project management consultant.
Meraas and BGRE broke ground on the development in August, appointing Swissboring Overseas Piling Corporation to carry out shoring, excavation, piling and dewatering works.
The launch comes amid sustained momentum in the local market. According to GlobalData, the UAE construction industry will expand at an average annual rate of 3.9% between 2025 and 2027, driven by investments across infrastructure, energy, housing and tourism. The country’s residential construction sector is forecast to grow by an average of 2.7% annually between 2025 and 2028, supported by ongoing private development and government initiatives to meet population growth.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21446815/main.png -
Borouge puts butene-1 expansion project on hold
16 November 2026
Abu Dhabi petrochemicals producer Borouge, now part of Austria-headquartered Borouge International, is said to have put on hold a project to increase butene-1 production from the olefins conversion unit (OCU) at its Borouge 2 facility in Ruwais Industrial City.
Under the proposed project, Borouge planned to produce 60,000 tonnes a year (t/y) of butene-1 from the existing fractionator column while limiting propylene production from the OCU to 500,000 t/y.
The company intended to achieve this by adding co-monomer production technology and selective hydrogenation units, while retaining the capability to run the unit at its original design capacity of 752,000 t/y of propylene and 39,000 t/y of butene-1. The scope also entailed expanding butene-1 storage capacity by converting existing N1 mixed-butane spheres into dedicated butene-1 units.
According to sources, Borouge informed contractors in the weeks after receiving bids that it had decided to shelve the tender.
Contractors submitted technical bids for the engineering, procurement and construction (EPC) package by 1 September 2025, following several extensions to the original 23 June deadline. Borouge had initially released an advanced tender notice in May last year, followed by the main EPC tender on 4 June, and hosted a site visit for bidders on 25 June.
Contractors understood to have submitted bids include:
- Galfar Emirates (UAE subsidiary of Oman’s Galfar Engineering & Construction)
- Target Engineering Construction (UAE)
US-based Lummus Technology was previously awarded the contract to provide the process design package for the new co-monomer production unit as the OCU licensor. Lummus sub-contracted the extended process design package and basic engineering works to South Korea’s Samsung E&A. Borouge had targeted an EPC contract award in the first quarter of 2026.
Butene-1 is a colourless gas primarily used as a co-monomer in the production of high-grade polyethylenes and poly(1-butene), serving end markets such as specialty films, bags and food packaging.
ALSO READ: Borouge prepares to tender construction works for ethane cracker expansion
Borouge International was formed through the combination of Adnoc Group and OMV’s shareholdings in Borouge and Austria-based Borealis, alongside the acquisition of Canada-based Nova Chemicals. In July, Adnoc announced it would transfer its holding in Borouge International to its global investment arm, XRG.
Borouge began operations in 2001 with 450,000 t/y of polyethylene capacity. The Borouge 2 and Borouge 3 expansions raised overall capacity to 2 million t/y in 2010 and 4.5 million t/y in 2014, respectively. Once the Borouge 4 expansion is commissioned, total production capacity will increase from 5 million t/y to 6.4 million t/y, creating the world’s largest single-site polyolefins facility.
Borouge 4 will add two polyethylene units with a combined capacity of 1.4 million t/y (700,000 t/y each) based on Borealis’s third-generation Borstar technology, supplied by a 1.5 million t/y ethane cracker and associated derivative units.
ALSO READ: Borouge restores Ruwais complex after Iranian attacks
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443754/main.jpg -
Contractor wins Saudi Energy substation deal
16 November 2026
Local firm Alfanar Projects has signed a contract with Saudi Energy, formerly Saudi Electricity Company, to build a 115/13.8kV substation in Al-Aqiq, Al-Bahah province, a source confirmed to MEED.
The station will receive electricity at 115kV and step it down to 13.8kV for local distribution. The scope of work includes site preparation, civil works, substation buildings and foundations, and the supply and installation of power transformers and associated electrical equipment.
Seventeen firms submitted bids for the project in May. The bidders included:
- Al-Babtain Contracting
- Al-Gihaz Holding
- Al-Haider Company
- Alfanar Projects
- Cepco
- Energy & Infrastructure Company (Eico)
- Expertise Contracting
- Haif Company
- JAL International
- Maetel Saudi Arabia Construction Company
- Mohammed Al-Ojaimi Group
- Nesma Infrastructure & Technology
- Nour Energy Company
- PA Cost International
- Sama Energy
- Saudi Projects & Supplies Company
- Tareg Al-Jaafari Contracting Establishment
According to regional project tracker MEED Projects, AlFanar Projects had won up to eight awards for substation projects this year, prior to the Al-Aqiq award.
The largest is a contract worth more than SR122m ($32.5m) to construct a 132/13.8kV substation for the Expo 2030 Riyadh site.
The firm was one of four contractors selected by Saudi Energy to deliver electricity infrastructure for the site, MEED reported in August.
Recent contracts include the 380kV Tumair PV substation (#9127), the Busita-C 132/33kV substation, the 132/13.8kV substation north of Al-Kharj (#8721) and the Al-Sahafa 132/13.8kV new substation (#8316).
Saudi Energy has tendered several other 380kV substations and associated transmission lines this year, including projects serving planned solar and wind developments in the kingdom’s central, western and southern regions.
Earlier, in November, MEED exclusively reported that China’s TBEA Shandong Luneng Taishan Cable Company (TBEA) and Egypt’s Elsewedy had submitted the lowest bids for two substation projects in Riyadh Province, estimated to cost a combined $100m.
The tenders for the Thadeq PV and Qiddiya 2 bulk supply points were issued earlier this year, with bids submitted in August and November, respectively.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21443095/main.jpg -
WEBINAR: End-of-Year Mena Market Review
13 November 2026
Webinar: The big questions shaping the Gulf market. You decide what gets debated.
Tuesday 24 November 2026 | 11:00 AM GST | Register now
What makes this session particularly interesting is that the audience gets to decide the agenda. Registrants can vote for the topics they’d like Ed and Colin to debate, with the most popular questions forming the final shortlist for the live session.
Topics in the ballot:
- Is the Gulf trying to build too much, too quickly?
- Saudi Arabia or the UAE: where would you place your next big bet?
- Are gigaprojects the best use of public money?
- Who is really responsible when projects go wrong?
- Should the lowest-price tender become a thing of the past?
- Can private capital take over from the government in financing infrastructure and diversification?
- Is the Gulf’s AI and data centre boom a smart bet or the next overbuilding risk?
- Should the Gulf double down on hydrocarbons to fund diversification?
- Is localisation strengthening the economy or making delivery harder?
- Are Gulf countries building complementary economies or competing for the same customers?
The session will also feature live audience polling and Q&A, giving attendees an opportunity to share their views.
Hosted by:
Edward James, head of content and analysis at MEED
 A well-known and respected thought leader in Mena affairs, Edward James has been with MEED for more than 19 years, working as a researcher, consultant and content director. Today, he heads up all content and research produced by the MEED group. His specific areas of expertise are construction, hydrocarbons, power and water, and the petrochemicals market. He is considered one of the world’s foremost experts on the Mena projects market. He is a regular guest commentator on Middle East issues for news channels such as the BBC, CNN and ABC News and is a regular speaker at events in the region.
Colin Foreman, editor of MEED
 Colin Foreman is editor and a specialist construction journalist for news and analysis on MEED.com and the MEED Business Review magazine. He has been reporting on the region since 2003, specialising in the construction sector and its impact on the broader economy. He has reported exclusively on a wide range of projects across the region including Dubai Metro, the Burj Khalifa, Jeddah Airport, Doha Metro, Hamad International airport and Yas Island. Before joining MEED, Colin reported on the construction sector in Hong Kong.https://image.digitalinsightresearch.in/uploads/NewsArticle/21380319/main.gif