Region heads for hotel boom
28 March 2024

This report on hotel investment also includes: GCC becomes a top tourist destination
Alongside the major infrastructure and construction schemes currently under way in the region, contractors in the Middle East and North Africa (Mena) are looking forward to a significant inbound spree of hospitality-linked project work.
A combination of government-led touristic masterplans – led by expansive and ambitious schemes in Saudi Arabia – alongside private sector investment in individual hotels and resorts has led to the build-up of a $54bn pipeline of hospitality-linked projects in the pre-execution, study and planning stages across the Mena region, according to regional projects tracker MEED Projects.
With this ramp up in planned hotel schemes, the region is now leading the global recovery in tourism projects, in a reflection of broader travel trends that have seen tourist arrival numbers grow to exceed pre-pandemic levels by 22%, according to GlobalData.
Projects under way
The $54bn project pipeline compares to a value of $22.7bn of work currently under execution in the region, and a long-term tally of $95.4bn-worth of hotel and resort project contract awards over the past decade and a half.
In contrast to the pace of activity since 2009, however, the region’s upcoming projects are set to be delivered in a much tighter timeframe. Almost the entire $54bn-worth of planned hotel and resort projects is scheduled or expected for award before the end of 2025 and set to be completed in advance of 2030.
This sets the stage for an intensified period of hotel investment and development over the next five years that could surpass the last investment boom cycle in 2014 and 2015, when hotel project award totals reached $9.1bn and $10bn, respectively.
Since 2009, the average annual value of hotel and resort project awards has been $6.4bn, with activity waxing and waning over the intervening period. Hotel and resort schemes fell away dramatically in 2020 amid the Covid-19 pandemic, with awards reaching a low of $2.6bn in 2021. Activity then recovered in 2022 and 2023 to the above-average values of $6.7bn and $6.6bn, respectively.
So far in 2024, there have been $1.3bn of hotel and resort project awards, but there is a further $5.2bn in work under bid and set to be awarded this year. The award of those projects would take the tally for 2024 up to $6.5bn – a comparable awards total to those of 2022 and 2023. There is then an additional $15bn-worth of projects in design and due for award in 2024 on the basis of announced and expected delivery timeframes.
If the value of projects under bid and just a third of the projects under design and also provisionally due for award in 2024 are let as expected, it will be a record year for hotel project awards in the region.
Saudi investment spree
Looking at the $54bn-worth of projects split by market, the pipeline is dominated by the touristic megaprojects currently under development in Saudi Arabia, which account for $39.9bn or 74% of the total value of upcoming work.
The hotel and resort projects in the kingdom are in turn heavily weighted towards several provinces that have been targeted for touristic development. These include Tabuk Province, which has $12.6bn-worth of upcoming hospitality-linked projects as part of the Neom and Red Sea Project developments; the Medina and Mecca provinces, which together hold $16.4bn-worth of upcoming schemes linked to the annual Hajj and Umrah tourism industry; Riyadh, with $7.1bn-worth of upcoming work, including that linked to the Qiddiya masterplan; and smaller values in Asir, the Eastern Province and others.
In recent months, several hotel schemes have been announced in the kingdom. In late February, Neom announced plans for a Raffles-branded property at its Trojena mountain resort development. The hotel will be located in the Discover cluster of the resort and is slated to open in 2027. The first hotel projects at Trojena are meanwhile well under way, with local contractor Isam Khairi Kabbani Group beginning work in December on the estimated $100m Chedi Trojena, with completion expected in 2026.
In early March, Red Sea Global (RSG) announced plans for a Four Seasons hotel at its Triple Bay development at Amaala, with Dubai-based U+A Architects, owned by the French engineering firm Egis, as project architect. Four Seasons has also announced other upcoming projects in the kingdom, including a Red Sea project at Shura Island, another at Neom’s Sindalah Island and projects on the Jeddah Corniche and at Diriyah, outside of Riyadh. Saudi Arabia’s Kingdom Holding Company has a 24% stake in Four Seasons, alongside majority shareholder Cascade Investment.
March also saw work begin on Neom’s Epicon Towers – a technically complex twin-tower hotel – with enabling works being undertaken by the local Ammico Contracting. Previously known as the Gas Station Hotel, the design for the project was developed by Singapore’s Meinhardt Group, with the Hong Kong-based 10 Design serving as the lead consultant on the project.
These upcoming schemes are set to join $7.8bn-worth of Saudi hotel projects awarded in the past three years, including $1.8bn-worth of awards in Tabuk. In July 2023, RSG awarded a contract at Triple Bay to the local Mas Engineering for the construction of the Marina Lifestyle Hotel & Village. In May, RSG contracted a joint venture of Egypt’s Hassan Allam Holding and the local Rawabi Specialised Contracting to construct the Triple Bay Rosewood Hotel.
Also in Tabuk, Hilton International opened its first Hampton hotel in March, having jointly developed the project with the Riyadh-based Cayan Group. The project was awarded in January 2022 to local contractor BEC Arabia, with Egypt’s Sabbour Consulting acting as project manager.
Elsewhere in the kingdom, the Public Investment Fund-backed Dan Company also tendered three hotels to be operated by Hilton at its Palm One project, a farm-based tourism destination in Al Ahsa. The deadline for bid submissions is 30 April. Hong Kong-based LWK Partners is the lead designer for the project.
Broader regional spending
In a prominent example of government-led hotel and resort development activity outside of Saudi Arabia, Oman has recently been progressing several new touristic masterplans.
Oman’s Heritage & Tourism Ministry issued a tender in February inviting consultants to bid to develop a tourism project masterplan for the Remal Al Sharqiyah dunes of North and South Al Sharqiyah. The tender was issued on 27 February, with a bid submission deadline of 17 April.
Earlier in February, Oman’s Housing & Urban Planning Ministry (MHUP) also revealed the designs for a new $2.4bn development on Jebel Al Akhdar named the Omani Mountain Destination and masterplanned by Canadian engineering firm AtkinsRealis.
The same month, the MHUP also announced the $1.3bn Al Khuwair Downtown and Waterfront project in Muscat, engaging Zaha Hadid Architects for the project design alongside real estate consultant CBRE.
In the UAE, much of the hotel and resort development is proceeding in a more piecemeal manner, with a greater number of smaller, more discrete touristic schemes. One major development in November was Dubai developer Al Wasl’s award of the $1.3bn contract to build The Island to China State Construction Engineering Corporation in the largest construction contract in Dubai since 2017.
The Island is a 10.5-hectare reclaimed island that will feature MGM, Bellagio and Aria branded hotels. The local APCC was the earthworks contractor, with the project being managed by Germany’s Buro Kling Architectural Engineering Consulting and the local Consultant HSS.
Another recent example of UAE project activity was Modon Properties’ award in November of the contract for a four-star sports hotel on Abu Dhabi’s Al Hudayriyat Island to Trojan General Contracting. The UK’s Atkins is the project consultant, with Canada’s Ellisdon as the project management consultant.
What is apparent from all of this activity is the clear strengthening of hotel project development as regional governments pursue tourism investments both as a long-term economic diversification strategy and one that dovetails with robust and rising visitor traffic to the region.
As long as these trends remain, strong ongoing government and private sector investment in hospitality-linked projects can be expected, and with it, the delivery of the region’s $54bn hotel project pipeline by 2030.
 GCC becomes a top tourist destination

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 H&H continues to deliver Dubai projects
29 October 2026
-
 Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
-
 Iraq oilfield water scheme to hit milestone next year
29 October 2026
-
 Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
-
 Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
H&H continues to deliver Dubai projects
29 October 2026
Dubai-based developer H&H has launched Water Gardens, a mixed-use development in Dubai International Financial Centre (DIFC), and expects to award most of the construction contracts for its wider pipeline before summer 2027.
Water Gardens comprises four buildings designed by UK architect David Chipperfield, arranged around a central garden and pedestrian-friendly public realm. The scheme combines offices, residences, hospitality and retail offerings, including the Four Seasons Private Residences Dubai at DIFC and residences under H&H’s Eden House brand.
 Construction is under way, and the developer says the project is scheduled for completion in 2028. DIFC Investments describes it as one of the final components of the original Gate District masterplan.
Speaking to MEED at the launch, H&H chairman Shahab Lutfi said the office building and Eden House are due for completion in about 18 months. The Four Seasons residences are scheduled for delivery at the end of 2028, with a five-star hotel following later.
Water Gardens is one of several projects H&H has under way. The company undertakes a selective portfolio of high-end real estate developments in prime locations in Dubai. These include the Carlyle Residences in DIFC; an Eden Hills villa community in Mohammed Bin Rashid City; and Dubai Peninsula, a waterfront scheme in the Jumeirah area that will include hotels operated by Aman and Rosewood.
“We are awarding day in, day out,” says Lutfi. “I think we are awarding most of our contracts from now until summer next year.”
Most of the company’s construction volume is in DIFC and Dubai Peninsula, with the Eden Hills villas accounting for a smaller share. Lutfi says H&H is talking to several of the emirate’s biggest contractors about upcoming packages.
We are awarding [contracts] day in, day out
Staged procurement
H&H is managing cost pressures by splitting up its procurement. It awards main contracts covering concrete works with a large number of provisional sums, then tenders further packages as designs are completed. “We are taking on some of the risk, but we know how to manage the risk instead of just offloading it on the contract,” says Lutfi.
He does not expect construction costs to fall in the next 12 months. Global inflation, driven by fuel prices and logistics costs, is already factored into the company’s plans.
“Waiting and trying to award at a cheaper price is not an option for us,” he says.
Lutfi says rising costs need not erode margins for developers that keep unsold stock to sell at higher prices later in a project. Developers that sell out early are more exposed. “If you have already sold out two years ago, you are hurting your profitability,” he says.
H&H is comfortable leaving 15%-20% of a project to sell on completion. The market usually expects developers to sell out before handover.
The company has not revised its masterplans or product mix in response to market conditions and continues to focus on large units.
Supply chains have been a challenge this year, but Lutfi says the company is over that hurdle. H&H has sourced more materials locally and planned logistics further in advance.
Materials are reaching Dubai through bonded routes from Oman, Fujairah and Khor Fakkan in the UAE, and Jeddah in Saudi Arabia.
“It takes a little bit longer, but at least things are coming in,” he says.
H&H relies on a relatively small group of contractors that work on most of its projects, and treats them as long-term partners.
Lutfi says contractors are attracted by the company’s financial stability and volume of work. “That can keep some people busy for the next five or six years,” he says.
Lutfi notes that sales in the Dubai market have dropped, although enquiries have picked up since the summer as buyers weigh whether it is the right time to purchase. The distressed sales that some had expected have not materialised.
“A 5% discount in some units is not really a distress sale,” he says. “It is just someone trying to get a discount because of the region’s situation, which actually builds confidence.”
For Water Gardens, H&H has sold 85% of Four Seasons Private Residences Dubai at DIFC since sales began in 2024. The company launched sales at the Carlyle Residences before the regional disruption and has since sold units one-to-one to selected clients. More Four Seasons units have been sold in the past two weeks.
“Branding makes a big difference,” says Lutfi.
The company markets its branded residences through a global network of brokers rather than via public campaigns or launch events. Eden Hills, which is aimed mainly at Dubai residents, is marketed more widely.
Lutfi expects buyers to be more cautious about buying off-plan. H&H is building new sales centres at Dubai Peninsula and in DIFC so that clients can see the product before they commit.
“People have to come in, know exactly what they are buying, and they will feel comfortable paying the price – instead of just having a pretty brochure,” he says.
He expects demand for villas to become more local and regional, while branded residences will continue to attract international buyers.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21012636/main.gif -
Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
Expo 2030 Riyadh Company (ERC), responsible for delivering the Expo 2030 Riyadh venue, has allowed contractors until 11 November to submit bids for a contract to deliver the Souq areas within the Expo site.
The tender was floated on 30 July, with an initial submission deadline of 9 October.
The Souq areas are divided into five distinct precincts, with a total development area of about 300,000 square metres (sq m).
The scope includes the five precincts and their associated vertical elements, infrastructure and public realm works.
The precincts comprise:
- Precinct 1 – The Icon: 41,417 sq m
- Precinct 2 – Place & Planet: 62,306 sq m
- Precinct 3 – Culture of Wisdom: 67,112 sq m
- Precinct 4 – Kingdom of Saudi Arabia: 45,967 sq m
- Precinct 5 – Adaptation & Innovation: 82,358 sq m
The package will interface with three public parks. It will also tie into the Natural Corridor, including bridges.
The Souq areas will form a mixed-use destination at the centre of Expo 2030 Riyadh, connecting the site’s iconic and thematic assets.
The development will include rented and partnership pavilions, alongside a range of food and beverage, retail and visitor-experience offerings.
Site progress
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to build a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts to local firm Al-Yamama Company for the next phase of infrastructure works at the site.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, and electric vehicle charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20998514/main.jpg -
Iraq oilfield water scheme to hit milestone next year
29 October 2026
China Petroleum Pipeline Engineering (CPP) expects to start laying pipeline for Iraq’s Common Seawater Supply Project (CSSP) in Basra in mid- or late next year, according to industry sources.
The project is behind schedule, partly because importing sections of pipeline is proving challenging due to disruptions to shipping through the Strait of Hormuz.
The project is being managed by state-owned Basra Oil Company (BOC), with Australia’s ILF acting as a project management consultant after completing the front-end engineering design (feed).
Under current plans, the pipelines will be buried, which is expected to make them more secure than if they were installed on the surface.
Phased development
The client for the first phase of the CSSP is France’s TotalEnergies in partnership with QatarEnergy and BOC.
The first phase is split into two packages currently under execution and will ultimately have the capacity to transport 5 million barrels a day (b/d) of water.
The first package focuses on developing pipelines, and the second on developing a water treatment facility.
CPP is executing the pipeline package contract.
It signed a $2.5bn contract with BOC for the package in September last year.
Also in September 2025, South Korea’s Hyundai announced that it had signed a contract worth 4.39tn won ($3.16bn) for the processing plant package.
In September this year, MEED reported that early groundworks had started for both packages of the first phase of the CSSP.
Phase one of the project is scheduled to start up in late 2028 or early 2029.
Earlier this month, US-headquartered Exxon Mobil signed a memorandum of understanding related to the project’s second phase, which is expected to add 2.5 million b/d of water capacity.
The CSSP will inject processed water into several of Iraq’s biggest oil fields. These include Rumaila, Zubair, West Qurna 1, West Qurna 2 and Majnoon. Water from the project will also be used in the Maysan and Dhi Qar fields.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20981033/main.jpg -
Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
Dubai Municipality has invited contractors to bid for a contract to build sewerage and stormwater infrastructure in New Al-Awir 1st.
The project (DS317-C1) comprises about 95 kilometres of sewerage gravity network, excluding house connections, and about 105km of stormwater pipelines. The scope also includes house connection pipes, a stormwater pond and oil interceptors.
According to tender documents seen by MEED, the tender was issued on 23 October, with a bid submission deadline of 12 November.
The project comes amid wider residential and infrastructure development in Al-Awir 1. In January 2025, Dubai’s Roads & Transport Authority (RTA) announced plans to build 16.5km of internal roads in the area, including a new entrance from Emirates Road.
In February 2025, MEED exclusively reported that the RTA had selected a local firm to undertake the road construction works.
The Mohammed Bin Rashid Housing Establishment has also reported progress on housing projects in Al-Awir as part of a wider programme to develop residential communities across Dubai.
The sewerage and stormwater project is relatively large compared with recent stormwater tenders, with the total cost estimated at up to AED1bn ($272m).
The works will include approximately 69.2km of house connection pipes and 4,630 inspection chambers. The sewerage network will also include about 1,511 manholes, while the stormwater network will comprise approximately 1,247 manholes.
Contractors will also be required to use no-dig construction methods for sections of the pipeline. The scope includes ground investigations, utility protection and traffic management.
The bill of quantities specifies a stormwater pond with a composite volume of approximately 1.2 million cubic metres.
Earlier this week, Dubai Municipality confirmed it had awarded contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects are part of Dubai’s AED30bn Tasreef programme and will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom.
The overall programme aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20977734/main.jpg -
Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
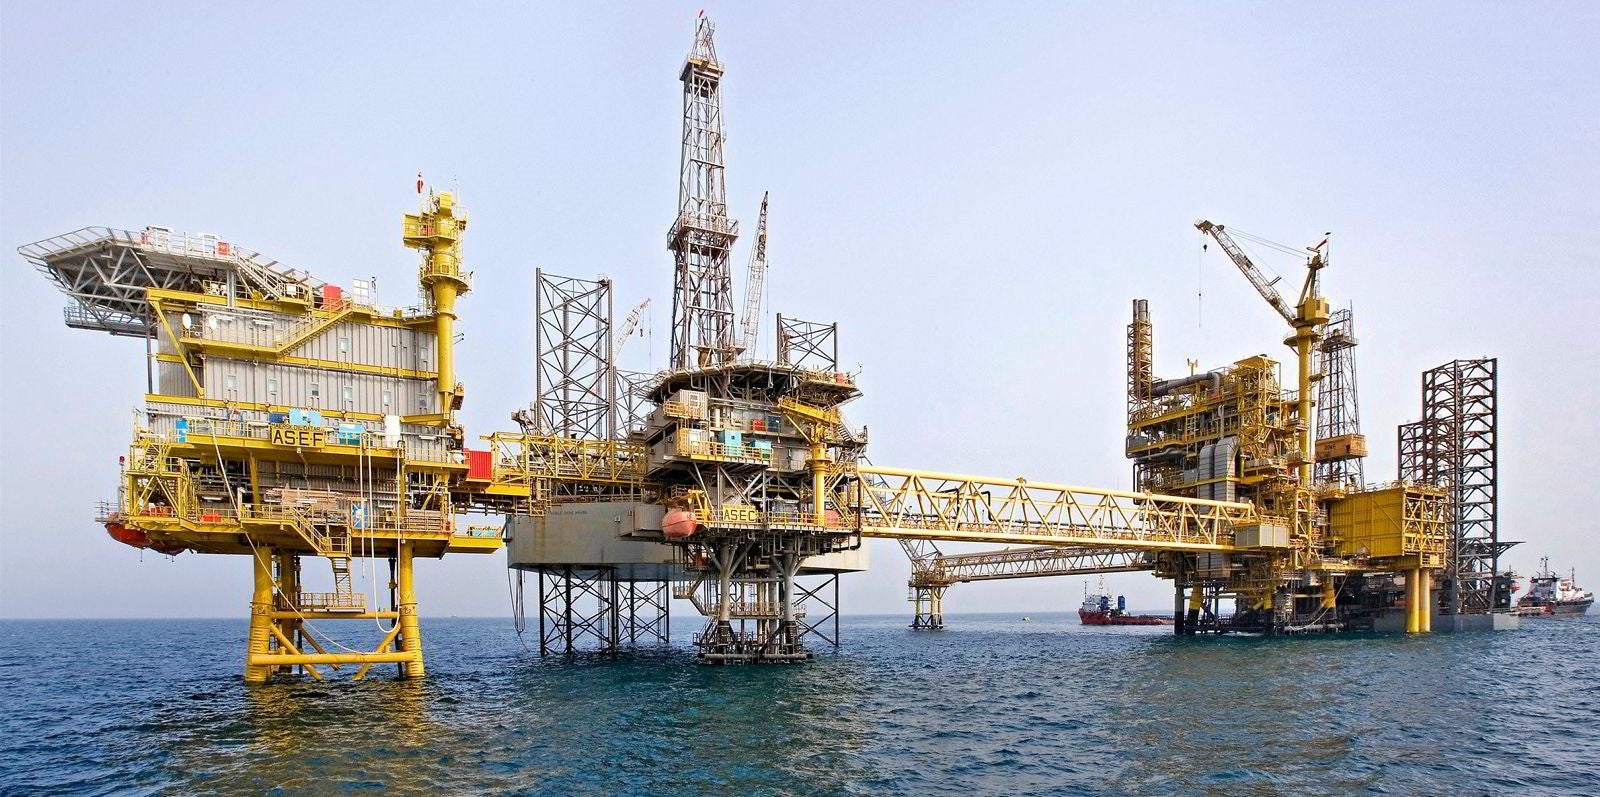
QatarEnergy has received technical bids from contractors for a key tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors submitted their technical bids by the 26 October deadline, according to sources.
Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The modules will increase gas production from North Field reservoirs and supply additional gas feedstock to the NFW liquefied natural gas (LNG) development.
Issued earlier this year, the tender forms part of the wider NFW project, the third and final phase of QatarEnergy’s North Field LNG expansion programme.
The technical-bid deadline has been extended several times, from 30 August to 15 September, 28 September, 12 October and 19 October. Commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott an EPCI contract for four offshore jackets to support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20973187/main.jpg