Region primed for global green hydrogen leadership
15 August 2022
 Published in partnership with

There have been fewer hot topics in the Middle East and Africa (MEA) over the past 18 months than the development of green hydrogen production.
Ever since Neom, Acwa Power and Air Products announced their $5bn investment in a world-scale green hydrogen production complex as the anchor project of the $500bn Neom development in 2020, energy companies around the world have been racing to establish plans of their own in the region.
Today, there are at least 46 known green hydrogen and ammonia projects across the MEA region, with an estimated total budget of more than $92bn.
Almost all have been announced since the start of 2021, equivalent to nearly two new projects a month.
Competitive advantage
This sudden surge of interest in hydrogen needs little explanation. Due to its climate, the region enjoys the world’s highest solar irradiation levels, enabling the production of some of the cheapest renewable energy anywhere.
The 600MW Al-Faisaliah independent solar photovoltaic (PV) power project in Saudi Arabia, for instance, currently holds the world record for the lowest renewable energy levelised cost of electricity of just $1.04 cents a kilowatt hour.
This electricity from renewable sources is used to electrolyse vast amounts of treated and filtered seawater to extract hydrogen, which in turn is processed with air-derived nitrogen to produce the more easily transportable ammonia.
The ammonia can then be liquefied, compressed and exported by ship to the end-user market, where it can be converted back to hydrogen to be used as a clean fuel or utilised as ammonia for fertiliser or other industrial processes.
Other alternatives include converting the hydrogen to methanol, another more easily transportable fuel product, or piping the hydrogen directly to the end user, either for domestic purposes or for export.
Along with plentiful sunlight, the other main requirement to house the huge solar and wind farms is space, something the region is generally not short of. Oil and gas-importing nations such as Morocco, Ethiopia and South Africa can also benefit from the hydrogen project boom.
 First mover status
Aside from the environmental benefits of green hydrogen as a carbon-free fuel, it also offers the oil-exporting states of the Middle East the tantalising prospect of diversifying their dominant crude production position with hydrogen, thereby safeguarding their economies for decades to come as well as enhancing their geopolitical significance.
Speed of capital investment to drive technological leadership and potentially first-mover advantage is arguably going to be another important factor.
From a demand perspective, there is no doubt about green hydrogen’s potential. Demand in Europe alone is forecast to double to 30 million tonnes a year (t/y) by 2030 and to 95 million t/y by 2050.
Thanks to its geographical position, the Middle East is ideally located to meet this demand either by ship or pipeline.
Until recently, green hydrogen may not have been considered financially viable. Today, it could be described as an economic necessity
MEA Energy Week insights
The massive potential and development of a green hydrogen production industry was one of five central themes and insights emerging from the Middle East & Africa Energy Week hosted by Siemens Energy in June.
Yet a live poll of up to 400 delegates as part of Siemens Energy’s Middle East & Africa Energy Transition Readiness Index, produced in partnership with Roland Berger, highlighted that a substantial majority felt that Power-to-X technology – of which hydrogen production is a major component – was slow in meeting its potential.
To put this into perspective, with the notable exception of the Neom-based Helios project and the pilot green ammonia scheme at Ain Sokhna in Egypt, none of the other 44 announced green hydrogen projects in the region have yet to start work on the ground. Many have not even reached a full investor agreement.
The principal challenges revolve around financing, supply and power purchase agreements, land allocations and permitting. Ultimately, even with cheap electricity, green hydrogen is still comparatively expensive to produce after factoring in electrolysis, processing and transportation costs.
There is also some debate over whether the end-user market is ready to pay a premium for cleaner fuel or chemical feedstock.
A related poll question among the Energy Week’s attendees underlined this. Of 11 energy priorities presented, Power-to-X solutions were ranked as the lowest priority in terms of the impact on their companies’ achievement of climate targets.
However, this could change rapidly. The Russia-Ukraine crisis has focused European capitals on the pressing need to diversify fuel sources. Until recently, green hydrogen may not have been considered financially viable. Today, it could be described as an economic necessity.
Transitioning to hydrogen requires huge investment to develop technology, build projects and establish marketplaces that collectively contribute to a cleaner energy future. This coordinated effort by all stakeholders must be supported by policymakers
Nabil al-Nuaim, Saudi Aramco
Encouraging local demand
Equally important is the development of local hydrogen demand. To date, few formal policies or strategies have been announced to stimulate a market for domestic demand, reflected by the fact that almost all of the planned green hydrogen projects pipeline are export orientated.
While this export focus may make sense commercially, there was unanimity among the event’s participants that more could be done to encourage home-grown demand.
“Transitioning to hydrogen requires huge investment to develop technology, build projects and establish marketplaces that collectively contribute to a cleaner energy future,” said Saudi Aramco’s chief digital officer, Nabil al-Nuaim. “This coordinated effort by all stakeholders must be supported by policymakers to achieve success.”
This view was echoed by Khaled Sharbatly, CEO of solar PV panel manufacturer and power developer Desert Technologies. “We need to accelerate the growth of energy in Africa, accelerate energy storage and innovation, and build a regulatory framework where everyone is in sync,” he said.
The development of regulations and policy reforms to provide impetus will be vital for the market to grow, as will associated strategies such as introducing carbon pricing, reducing electricity subsidies, unbundling power networks and incentivising electric vehicle usage.
If it fails to do so, the region may miss the opportunity to capitalise on hydrogen’s potential to create jobs and a local manufacturing industry, diversify economies, and, most importantly, reduce carbon emissions and achieve net zero.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Riyadh Expo sets November bid deadline for Souq construction
29 October 2026
-
 Iraq oilfield water scheme to hit milestone next year
29 October 2026
-
 Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
-
 Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
-
 US military approaches contractors for Qatar air base project
28 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Riyadh Expo sets November bid deadline for Souq construction
29 October 2026

Expo 2030 Riyadh Company (ERC), responsible for delivering the Expo 2030 Riyadh venue, has allowed contractors until 11 November to submit bids for a contract to deliver the Souq areas within the Expo site.
The tender was floated on 30 July, with an initial submission deadline of 9 October.
The Souq areas are divided into five distinct precincts, with a total development area of about 300,000 square metres (sq m).
The scope includes the five precincts and their associated vertical elements, infrastructure and public realm works.
The precincts comprise:
- Precinct 1 – The Icon: 41,417 sq m
- Precinct 2 – Place & Planet: 62,306 sq m
- Precinct 3 – Culture of Wisdom: 67,112 sq m
- Precinct 4 – Kingdom of Saudi Arabia: 45,967 sq m
- Precinct 5 – Adaptation & Innovation: 82,358 sq m
The package will interface with three public parks. It will also tie into the Natural Corridor, including bridges.
The Souq areas will form a mixed-use destination at the centre of Expo 2030 Riyadh, connecting the site’s iconic and thematic assets.
The development will include rented and partnership pavilions, alongside a range of food and beverage, retail and visitor-experience offerings.
Site progress
Construction activity at the Expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract to build a new metro station serving the Expo 2030 site.
In April, ERC awarded two contracts to local firm Al-Yamama Company for the next phase of infrastructure works at the site.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems, and electric vehicle charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025 to build and operate facilities for Expo 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20998514/main.jpg -
Iraq oilfield water scheme to hit milestone next year
29 October 2026
China Petroleum Pipeline Engineering (CPP) expects to start laying pipeline for Iraq’s Common Seawater Supply Project (CSSP) in Basra in mid- or late next year, according to industry sources.
The project is behind schedule, partly because importing sections of pipeline is proving challenging due to disruptions to shipping through the Strait of Hormuz.
The project is being managed by state-owned Basra Oil Company (BOC), with Australia’s ILF acting as a project management consultant after completing the front-end engineering design (feed).
Under current plans, the pipelines will be buried, which is expected to make them more secure than if they were installed on the surface.
Phased development
The client for the first phase of the CSSP is France’s TotalEnergies in partnership with QatarEnergy and BOC.
The first phase is split into two packages currently under execution and will ultimately have the capacity to transport 5 million barrels a day (b/d) of water.
The first package focuses on developing pipelines, and the second on developing a water treatment facility.
CPP is executing the pipeline package contract.
It signed a $2.5bn contract with BOC for the package in September last year.
Also in September 2025, South Korea’s Hyundai announced that it had signed a contract worth 4.39tn won ($3.16bn) for the processing plant package.
In September this year, MEED reported that early groundworks had started for both packages of the first phase of the CSSP.
Phase one of the project is scheduled to start up in late 2028 or early 2029.
Earlier this month, US-headquartered Exxon Mobil signed a memorandum of understanding related to the project’s second phase, which is expected to add 2.5 million b/d of water capacity.
The CSSP will inject processed water into several of Iraq’s biggest oil fields. These include Rumaila, Zubair, West Qurna 1, West Qurna 2 and Majnoon. Water from the project will also be used in the Maysan and Dhi Qar fields.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20981033/main.jpg -
Dubai tenders Al-Awir sewerage and stormwater works
29 October 2026
Dubai Municipality has invited contractors to bid for a contract to build sewerage and stormwater infrastructure in New Al-Awir 1st.
The project (DS317-C1) comprises about 95 kilometres of sewerage gravity network, excluding house connections, and about 105km of stormwater pipelines. The scope also includes house connection pipes, a stormwater pond and oil interceptors.
According to tender documents seen by MEED, the tender was issued on 23 October, with a bid submission deadline of 12 November.
The project comes amid wider residential and infrastructure development in Al-Awir 1. In January 2025, Dubai’s Roads & Transport Authority (RTA) announced plans to build 16.5km of internal roads in the area, including a new entrance from Emirates Road.
In February 2025, MEED exclusively reported that the RTA had selected a local firm to undertake the road construction works.
The Mohammed Bin Rashid Housing Establishment has also reported progress on housing projects in Al-Awir as part of a wider programme to develop residential communities across Dubai.
The sewerage and stormwater project is relatively large compared with recent stormwater tenders, with the total cost estimated at up to AED1bn ($272m).
The works will include approximately 69.2km of house connection pipes and 4,630 inspection chambers. The sewerage network will also include about 1,511 manholes, while the stormwater network will comprise approximately 1,247 manholes.
Contractors will also be required to use no-dig construction methods for sections of the pipeline. The scope includes ground investigations, utility protection and traffic management.
The bill of quantities specifies a stormwater pond with a composite volume of approximately 1.2 million cubic metres.
Earlier this week, Dubai Municipality confirmed it had awarded contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects are part of Dubai’s AED30bn Tasreef programme and will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom.
The overall programme aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20977734/main.jpg -
Contractors bid for QatarEnergy’s North Field West topsides
28 October 2026
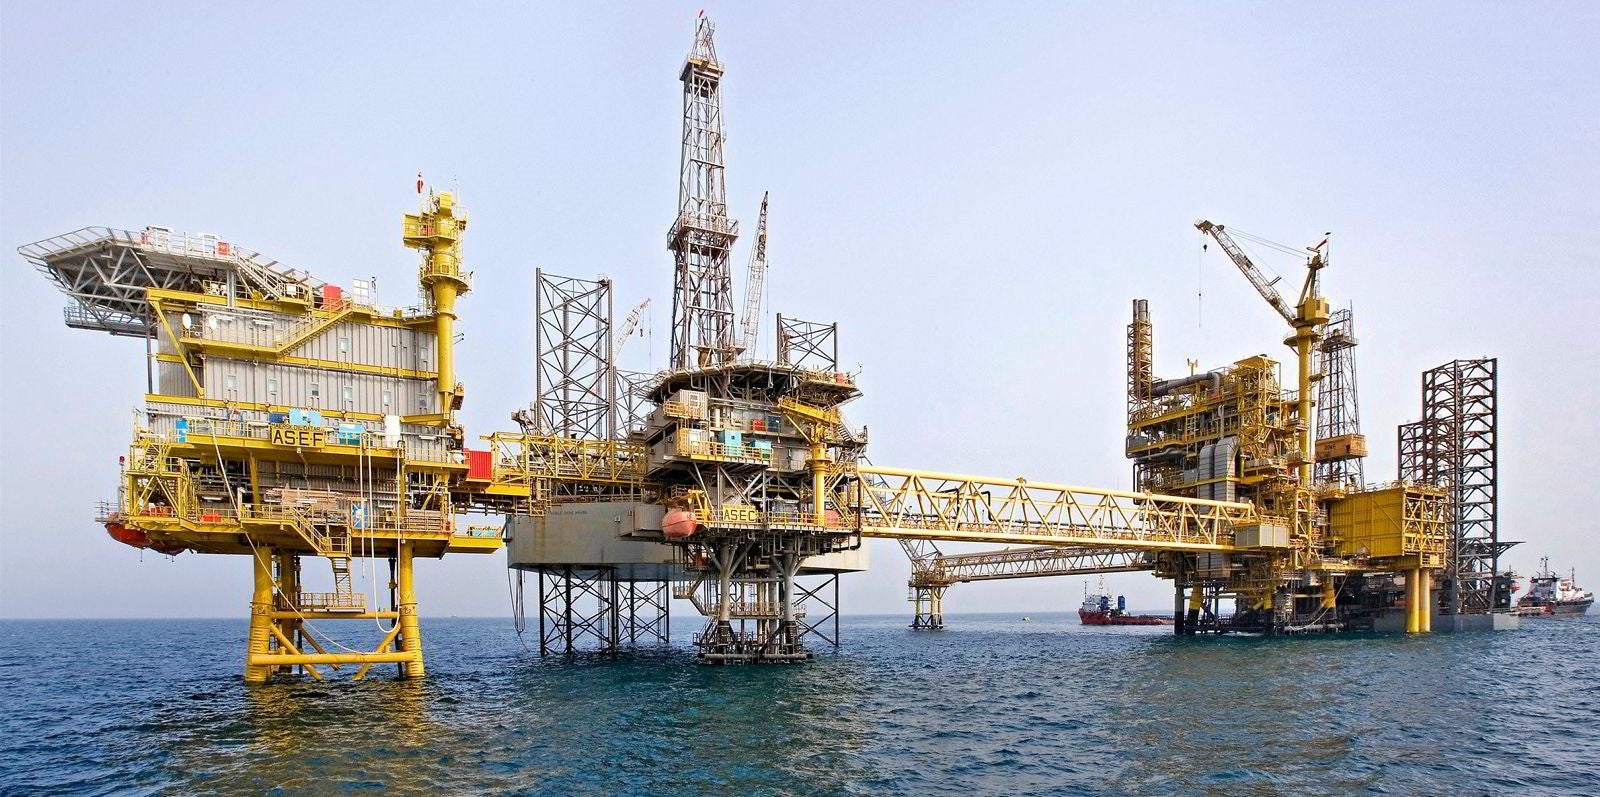
QatarEnergy has received technical bids from contractors for a key tender covering the engineering, procurement, construction and installation (EPCI) of large platforms for the North Field gas field in Qatari waters.
Contractors submitted their technical bids by the 26 October deadline, according to sources.
Commercial bids are currently due on 10 November.
The following contractors, among others, are understood to be bidding for the North Field West (NFW) production deck modules (PDMs) tender:
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The core scope comprises the EPCI of four PDMs and associated structures. The modules will increase gas production from North Field reservoirs and supply additional gas feedstock to the NFW liquefied natural gas (LNG) development.
Issued earlier this year, the tender forms part of the wider NFW project, the third and final phase of QatarEnergy’s North Field LNG expansion programme.
The technical-bid deadline has been extended several times, from 30 August to 15 September, 28 September, 12 October and 19 October. Commercial bids were previously due on 25 October, as MEED reported.
Before issuing the PDMs tender, QatarEnergy awarded US firm McDermott an EPCI contract for four offshore jackets to support gas feedstock supply for the NFW LNG project. The contract is estimated to be worth about $200m, MEED reported in January.
North Field LNG expansion
QatarEnergy is advancing the three phases of its estimated $40bn North Field LNG expansion project. EPC works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million tonnes a year (t/y) to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the EPCI of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on NFW earlier this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the front-end engineering and design work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20973187/main.jpg -
US military approaches contractors for Qatar air base project
28 October 2026
The US Army Corps of Engineers (USACE) has begun market engagement for an anticipated contract to design and build a Space Campus at Al-Udeid Air Base in Qatar.
USACE’s Southwestern Division, Middle East District, has issued a sources-sought notice to identify contractors capable of delivering an integrated design-and-construction (IDaC) contract.
The successful contractor will provide pre-construction services and build secure facilities that comply with Intelligence Community Directive 705 (ICD 705) standards.
Interested firms must submit capability statements by 30 October.
The construction market engagement follows USACE’s procurement of architect-engineer services for the development. The authority intends to award a single-award, task-order contract covering planning, design, site investigations and construction-phase support. The contract will have a five-year base period, with a two-year option, and a capacity of up to $100m.
USACE expects to award the design contract in April 2028, alongside an IDaC construction contract following completion of the planning activities.
The Space Campus is being developed to meet an operational requirement of the US Air Force and forms part of the Al-Udeid Air Base 2040 Strategic Master Plan.
It will include a secure administrative headquarters, coalition operations centre, secure warehouse, conference centre, storage facilities, access-control and guardhouse complex, antenna yards, shelters and multiple unit buildings.
The scope also includes secure perimeter fencing, intrusion-detection and closed-circuit television systems, roads, parking, site preparation, utility networks, substations, generators, chilled-water systems, fuelling facilities, and secure and unclassified communications networks.
The project will require hardened and potentially underground structures. Contractors are expected to demonstrate expertise in managing saline groundwater, dewatering, underground waterproofing and Qatar’s geotechnical conditions.
The latest procurement activity comes as Qatar’s Public Works Authority, Ashghal, tenders a contract for roads and associated infrastructure serving Al-Udeid Air Base.
The project in Zone 95 of Al-Wakra Municipality includes a dual-lane carriageway, three roundabouts, electrical substations, drainage, lighting, intelligent transport systems and utility works.
The road will link Al-Majd Road to the east with Street 203 in Zone 95 to the west.
According to GlobalData’s Qatar Defence Market 2026-2031 report, Qatar allocated an estimated $17bn to defence in 2026, representing a compound annual growth rate (CAGR) of 2.5% between 2022 and 2026.
The defence budget is projected to grow at a CAGR of 3.8% over the 2027-31 forecast period, reaching an estimated $20.8bn in 2031.
Defence diplomacy is also a key factor in military procurement, with Doha strengthening bilateral ties through acquisitions from the US, France and Turkiye.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20971169/main.jpg