Water sector braces for likely slowdown
27 December 2024

 Geopolitical tensions, climate change and higher-than-average population growth have exacerbated the water demand and supply gap across the Middle East and North Africa (Mena) region, home to some of the world’s most water-stressed countries.
For example, Jordan, where available water per capita is equivalent to only 12% of the absolute water scarcity level, hosts over 700,000 refugees fleeing wars and conflicts in neighbouring countries.
Most regional governments have developed and started to implement water strategies aimed at narrowing this gap. Subsidies are being phased out, environmental campaigns are being developed and digital solutions are being deployed in order to manage demand and improve efficiency.
Expanding desalination and treatment capacity, increasing treated sewage effluent (TSE) reuse, boosting reservoir capacity and building more efficient transmission and distribution networks are key levers used to improve supply.
Strong spending
These efforts have prompted significant capital spending on more energy-efficient water production, distribution and storage facilities, typically in partnership with private investors, particularly among the more affluent states.
According to data from regional projects tracker MEED Projects, the Mena region awarded $17bn of project contracts across the water desalination, treatment, transmission and distribution, storage and district cooling subsectors in the first nine months of 2024.
This figure represents about 72% of the contracts awarded in 2023 and is slightly above the average value of annual contract awards in the preceding five years.
 With only a few more packages expected to be awarded before the end of the year, 2024 looks set to be one of the best years so far in terms of water project activity, even if it fails to match the record value of contracts awarded in 2023, which reached almost $24bn.
In 2024, Saudi gigaproject developer Neom set the pace in January by awarding a $4.7bn contract to build dams at the Trojena Mountain Resort in Tabuk to Italian contractor WeBuild.
The contract covers the construction of three dams that will form a freshwater lake for the Trojena ski resort. The main dam will have a height of 145 metres and will be 475 metres long at its crest. It will be built using 2.7 million cubic metres of roller compact concrete.
While this project does not necessarily belong to the band of solutions that aim to narrow the water supply and demand gap, the overall development is part of Saudi Arabia’s drive to boost tourism and diversify its economy away from oil.
Meanwhile, 2024 also saw the award by UAE northern emirate utility Sharjah Electricity, Water & Gas Authority of the contract to develop its first independent water project (IWP), the 400,000 cubic-metres-a-day facility in Hamriyah, to Saudi utility developer Acwa Power, the contract’s sole bidder.
In May, Saudi Arabia’s National Water Company announced that it had completed the award of 10 contracts under the first phase of its privatisation programme. Each rehabilitate, operate and transfer contract involves the retrofitting or expansion of existing sewage treatment plants and associated network, and their long-term operation and management. The facilities are expected to deliver water at the TSE level for irrigation reuse.
On the greenfield sewage treatment front, Saudi Water Partnership Company (SWPC) awarded a $400m contract to develop the Al-Haer independent sewage treatment plant (ISTP) project to a team comprising the local Miahona Company and Belgium’s Besix. The facility is the largest and first to be tendered under the third round of the water offtaker’s ISTP procurement programme.
In September, Chennai-headquartered VA Tech Wabag confirmed it had won a $317m contract to build the Ras Al-Khair seawater reverse osmosis (SWRO) facility in Saudi Arabia using an engineering, procurement and construction (EPC) model. The project client is Saudi Water Authority (SWA), formerly Saline Water Conversion Corporation.
In Oman, Nama Water Services awarded two water distribution network packages, worth a combined $600m, catering to Al-Dhahirah Governorate.
Jordan also appointed a team comprising Paris-based Meridiam, Suez and Vinci Construction Grands Projets, along with Egypt’s Orascom Construction, for the contract to develop the Aqaba-Amman water conveyance and desalination scheme. It is the country’s largest infrastructure project to date and the first phase is valued at an estimated $2bn-$3bn.
The project is crucial to addressing Jordan’s severe water shortage problem, piping desalinated water over 445 kilometres from the southern Red Sea coast to the country’s northern regions. The consortium is talking to lenders and aims to reach financial close for the project in 2025.
 Slower momentum
Despite 2024 being a good year for contract awards, it fell short of the expectation built over the past few years, when the region’s largest economies began to execute their long-term water strategies.
For example, in Saudi Arabia, the years-long restructuring of the domestic water sector took a significant turn in 2024, with Water Transmission Company (WTCO), the kingdom’s licensed desalinated water transmission operator, gaining a broader portfolio of projects. As a result, the mandate to procure upcoming water transmission pipelines has been transferred to WTCO from SWPC.
The slower pace of IWP contract awards in Saudi Arabia was somewhat offset by a slew of tenders from SWA. The authority received bids for the EPC contracts to build four SWRO facilities in 2024, although as of November it had only managed to award one.
Earlier in 2024, Saudi gigaproject developer Neom also shelved a project to develop a zero-liquid discharge (ZLD) SWRO plant.
“The year may not have been as strong as 2023, but it is still a good year,” says Robert Bryniak, CEO of Dubai-based Golden Sands Management (Marketing) Consulting. “Some projects have been delayed or cancelled – for instance a few in Saudi Arabia – but all in all [2024 has been] a good year for the water business.”
Bryniak adds that Neom’s ZLD scheme is one of the year’s shelved projects that he would like to see revived in the future.
Beyond the GCC states, Morocco and Egypt are endeavouring to move their planned SWRO projects into the tendering phase.
In Morocco, Office National de L’Electricite et de L’Eue Potable (Onee) extended the review of its second IWP in Nador while waiting for its first IWP in Casablanca to reach financial close.
The first batch of renewable energy- powered desalination plants in Egypt has yet to reach the proposals stage despite the Sovereign Fund of Egypt having completed the bid prequalification process in 2023.

Potential contract awards
According to data from MEED Projects, an estimated $34bn-worth of water projects are in the tendering stage across the Mena region. A further $40bn-worth is in the prequalification stage and $57bn is in the design and study phases.
The $22bn Dubai Strategic Sewerage Tunnels (DSST) scheme stands out among the upcoming projects due to its scale, as well as for the chosen procurement approach.
The project aims to convert Dubai’s existing sewerage network from a pumped system to a gravity system by decommissioning the existing pump stations and providing a sustainable and reliable service that is fit for the future.
In April, Dubai Municipality launched the procurement process for the DSST project, which is to be developed as a public-private partnership (PPP).
While a dose of pessimism persists over the chosen PPP model – in part due to the project’s scale and strong civil works orientation, and Dubai’s dismal track record in procuring PPP schemes outside the utility sector – the project has managed to attract strong interest from EPC contractors, as well as from potential investors and sponsors.
Some of those that have sought to prequalify as investors, such as Begium’s Besix, Beijing-headquartered China Railway Construction Corporation and South Korea’s Samsung C&T, have previously been prequalified as EPC contractors for the DSST project, which suggests that the preferred approach of prequalifying EPCs ahead of investors could offer advantages.
In Saudi Arabia, WTCO, SWA, SWPC and Neom’s utility subsidiary Enowa are each expected to let several contracts in 2025, while Bahrain and Abu Dhabi could award one IWP contract each.
However, a robust overall pipeline does not necessarily guarantee that 2025 will resemble the upward trajectory that the sector has seen in the past two years.
“This year could be a turning point for the water industry throughout Mena,” says Bryniak, alluding to the possibility that, come January, the foreign and climate policies of the new occupant of the White House could affect the trend of water production capacity buildout in the Mena region.
Bryniak says that if US President-elect Donald Trump follows through with his promises, then we may be in store for, among other events, lower energy prices as the US drills more oil; a dampening of world trade as the US places tariffs on imports, especially on Chinese goods and services; less focus on the environment; and, generally, a more isolationist America.
“In my view, much depends on how much oil prices fall,” he continues.
“A significant drop in oil prices could result in cut-backs in a lot of development projects, and this, in turn, will adversely impact water demand and the overall build programme.”
However, the impact will not be uniform across asset types and procurement models, Bryniak notes. He expects water PPP projects to continue to grow, especially if capital availability is reduced by lower oil prices, as this is one way to preserve capital for use in other areas.
“I do not see any reason for tariffs to fall further in 2025. Tariffs, in my view, will remain roughly where they are now or increase slightly,” adds Bryniak.
However, the executive says that EPC contracts will likely have “a higher opportunity cost”, so there might be a reduced focus on this type of procurement model.
He concludes: “To the extent that development projects get trimmed down due to less capital being available as a result of significantly lower oil prices, then water procurers and other developers will likely scale back their projects.”

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Saudi Arabia raises electricity tariffs
26 October 2026
-
 Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
-
 Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
-
 Morocco plans second high-speed rail phase to Agadir
26 October 2026
-
 Riyadh tenders King Salman Stadium works
26 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Saudi Arabia raises electricity tariffs
26 October 2026
Saudi Energy, formerly Saudi Electricity Company, has announced revised electricity tariffs, which will take effect on 1 January 2027.
The revised tariff schedule, published on the company’s official website, covers residential, commercial, industrial, agricultural, charitable and government customers.
The largest percentage increase in consumption rates is 16.7%, for residential customers using up to 6,000 kilowatt-hours (kWh) a month. Residential customers will pay 21 halalas/kWh for monthly consumption of up to 6,000kWh, up from 18 halalas. For consumption above 6,000kWh, the rate will rise from 30 to 33 halalas/kWh, a 10% increase.
The industrial tariff will increase by 15%, from 20 to 23 halalas/kWh. Commercial customers, private healthcare facilities and private educational facilities will pay 25 halalas/kWh, up from 22 halalas, for consumption up to 6,000kWh a month, and 35 halalas/kWh above that level, up from 32 halalas.
Tariffs for charities and government customers will also increase. In addition to consumption-based charges, customers will pay a fixed monthly fee based on the capacity of their electricity meter. This replaces the previous separate charge for meter reading, maintenance and billing, with VAT applied to the revised tariffs.
Electricity investment
The new tariffs coincide with changes to water consumption tariffs announced by the National Water Company, also effective from 1 January 2027.
King Salman Bin Abdulaziz Al-Saud directed support measures following a proposal presented by Crown Prince and Prime Minister Mohammed Bin Salman Bin Abdulaziz Al-Saud.
This includes raising the minimum wage required for Saudi nationals to count as full employees towards private sector localisation quotas under the Nitaqat programme.
The tariff changes come as Saudi Arabia plans substantial investment in its electricity infrastructure. In September 2025, Saudi Energy announced plans to invest SR220bn ($58.7bn) in power infrastructure projects between 2025 and 2030.
A June 2025 report by Fitch Ratings forecast negative free cash flow of about SR16bn a year over the period and rising leverage, reflecting the financial demands of the programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20924301/main.jpg -
Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
Dubai Municipality has confirmed it has awarded four contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom. The works include constructing and extending main stormwater drainage lines with diameters of up to three metres.
The four packages are part of Dubai’s AED30bn Tasreef programme, which aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
The contracts have been awarded to China State Construction Engineering Corporation (CSCEC) and three local firms: Arifco Group, Nael Construction & Contracting (NCC) and Detech Contracting. Dubai Municipality did not state which projects the awards relate to.
According to sources, the contract awards include packages TF-15-C1, TF-15-C2 and TF-13-C1.
The first package, TF-15-C1, involves the construction of 21 kilometres of main and secondary drainage lines along Al-Wasl Road and in surrounding areas. It will cover Za’abeel 2, Al-Wasl, Jumeirah 1 and 2, Al-Bada’a, Al-Satwa and Dubai World Trade Centre. The estimated $100m contract was awarded to Detech in July, as exclusively reported by MEED.
The second package, TF-15-C2, covers the corridor between Sheikh Zayed Road and Al-Khail Road. It includes about 14km of main drainage lines serving Al-Quoz Industrial Areas 1, 3 and 4, and Al-Barsha 1. In July, MEED reported that CSCEC had won the engineering, procurement and construction contract for this project.
The third package, TF-13-C1, covers Al-Marmoom, where 23km of drainage infrastructure will be developed. According to a source, Arifco has been awarded this contract.
The final package covers Jumeirah and Umm Suqeim, where about 42km of main drainage lines will serve Umm Suqeim 1, 2 and 3; Umm Al-Sheif; Jumeirah 3; Al-Safa 1 and 2; and Al-Manara.
In May, MEED reported that NCC had been awarded a contract to build a sewage and stormwater drainage system, DS-204. However, it is unconfirmed whether this relates to the same project.
Earlier, in February, the municipality confirmed it had awarded contracts for five new projects under phase two of the programme to expand and strengthen Dubai’s stormwater drainage network.
These included two contracts awarded to Detech and one to CSCEC for stormwater drainage infrastructure. In addition, two consultancy contracts were awarded for the study and design of drainage systems in selected areas across the emirate.
Cumulatively valued at AED2.5bn, the new projects will serve 30 vital areas, spanning approximately 430 million square metres and supporting an estimated population of three million residents by 2040.
Previously, in April 2025, an earlier package of awards was announced under phase one of the Tasreef programme. The overall masterplan aims to expand Dubai’s rainwater drainage capacity by 700% by 2033.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923924/main4827.jpg -
Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
Dubai-based master developer Nakheel, part of Dubai Holding Real Estate, has awarded local firm Parkway International Contracting a construction contract valued at about AED950m ($259m) for phases two and four of Bay Grove Residences on Dubai Islands.
The package covers 617 residential units across eight buildings, ranging from one to four bedrooms, together with basement structures, infrastructure and community amenities including swimming pools, sports courts and fitness centres.
Phase two comprises 360 homes across four buildings, with main construction scheduled for completion in late 2028.
Phase four includes 257 homes across four buildings, with completion targeted for the second quarter of 2029.
The award follows an earlier contract valued at about AED800m ($218m) awarded to local contractor Metac General Contracting Company for phases one and three, covering 537 homes across seven buildings.
Together, the two contracts total more than AED1.75bn ($476m) and account for all 1,154 planned homes across the 15 buildings of Bay Grove Residences.
Project activity on Dubai Islands has gathered pace in recent months. Earlier this month, Nakheel awarded local firm Mar Marine & Building Contracting a contract for marine and coastal works on Island B. The scope includes constructing breakwaters, removing existing rock revetments and creating a new 320-metre beach near the Bay Villas development, as well as remedial and refurbishment works along approximately 3 kilometres of the island’s western shoreline.
In August 2025, Nakheel awarded Fibrex Contracting a AED2.6bn ($708m) construction contract for the Bay Villas residential project. That followed a AED527m ($143m) contract awarded to Al-Nasr Contracting Company in April 2026 for primary infrastructure and utilities on Island B.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923389/main.jpg -
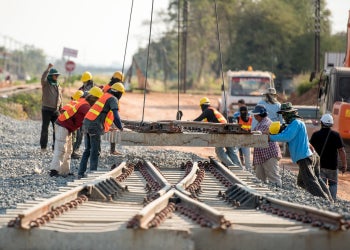
Morocco plans second high-speed rail phase to Agadir
26 October 2026
Morocco has outlined a second rail investment cycle for 2030-35, which includes beginning construction of a high-speed rail extension from Marrakech to Agadir and connecting Essaouira to the national rail network.
The pipeline forms part of the government’s 2026-31 programme, presented to parliament last week.
The Marrakech-Agadir link is estimated to cost close to MD55bn ($5.5bn) and will cover a 240-kilometre (km) route through the High Atlas Mountains via Chichaoua. Civil engineering structures, including tunnels and viaducts, are expected to account for nearly 70% of the alignment.
In September, the government issued a decree declaring the Marrakech-Agadir and Chichaoua-Essaouira rail corridors to be of public utility, paving the way for land acquisition and expropriation procedures.
Under the long-term masterplan Plan Rail Maroc 2040, Essaouira is expected to connect to the network via a separate line branching off at Chichaoua, designed for operating speeds of up to 200km an hour. The mainline to Agadir is designed for speeds of up to 320km/h.
The 2030-35 cycle also includes rehabilitating the Casablanca-Khouribga-Oued Zem line; constructing a new line between Oued Zem and Beni Mellal via Bejaad, with a branch to Fquih Ben Salah; doubling and upgrading the 140km Benguerir-Safi line; expanding capacity on the Fez-Oujda corridor; and building new-generation passenger stations.
The plans follow Morocco’s ongoing MD134bn ($13.4bn) 2024-30 rail investment programme, which focuses on completing the Kenitra-Marrakech high-speed line ahead of the 2030 Fifa World Cup.
The programme also includes developing regional express network services across five regions, electrifying the Fez-Oujda line and completing a freight rail link to the Nador West Med port.
Work on the Kenitra-Marrakech line had reached about 30% by May 2026, with commercial services targeted to begin in September 2029.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20920349/main.jpg -
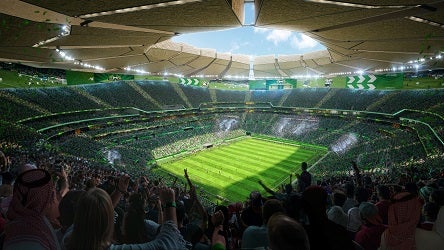
Riyadh tenders King Salman Stadium works
26 October 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Sports Ministry has tendered a contract covering early works at King Salman International Stadium in Riyadh.
The scope includes enabling works, site preparation and initial construction activities.
The tender was issued on 11 October, with a submission deadline of 19 November.
The stadium will cover about 660,000 square metres (sq m) and seat 92,000. Facilities will include a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The wider development will include sports facilities covering more than 360,000 sq m, including two training fields and fan zones; a closed sports hall; an Olympic-sized swimming pool; an athletics track; and outdoor courts for volleyball, basketball and padel.
The stadium is set to host the final of the 2034 Fifa World Cup and will serve as the Saudi national football team’s main base.
US-based architectural firm Populous is the lead architect for the stadium.
Construction of the stadium is expected to be completed by 2029.
The stadium will be located next to King Abdulaziz Park.
Firms submitted prequalification statements for the main design-and-build contract in February.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia planned to build 11 new stadiums and refurbish four facilities for the 2034 Fifa World Cup.
Eight stadiums will be located in Riyadh, four in Jeddah and one each in Al-Khobar, Abha and Neom.
A further 10 cities will host training bases: Al-Baha, Jazan, Taif, Medina, Alula, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah.
There are expected to be 134 training sites in the kingdom, including 61 existing facilities and 73 new venues.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of Fifa member associations at the Fifa Congress on 11 December 2024.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20919233/main.jpg