Power sector awards momentum accelerates
26 December 2024

The Middle East and North Africa (Mena) region’s power sector awarded over $60bn of contracts between January and early November 2024, up 47.5% compared to the value of awarded contracts in the previous full year.
This figure is more than double the average value of annual contract awards recorded between 2014 and 2023, based on data from regional projects tracker MEED Projects.
 It also exceeds by 21% the total combined value of contracts awarded between 2018 and 2020, when some regional governments and utilities began pivoting to renewable energy and freezing the expansion of thermal plant capacities, in line with goals aimed at decarbonising their electricity systems.
In 2020, the Covid-19 pandemic slowed down project activity and temporarily delayed the awarding of some contracts.
The market staged a short-lived comeback in 2021, when Saudi Arabia awarded a string of contracts for solar photovoltaic (PV) independent power projects (IPPs), including a contract to develop the 600MW Shoaiba solar PV scheme, which holds the world record for the lowest unsubsidised solar PV production at $cents1.04 a kilowatt-hour.
A slight contraction occurred the following year due to a spike in raw materials and engineering, procurement and construction (EPC) costs.
Last year saw a stunning recovery, however, helped by the award of new renewable energy projects in Saudi Arabia, the UAE, Egypt and Oman, as well as by a resumption of contract awards for new gas-fired power plants, particularly in Saudi Arabia, Libya and Iraq.
Yet 2024 is set to outshine 2023 in terms of awarded contracts for thermal, renewable energy and nuclear power generation plants, as well as for power transmission and distribution (T&D) infrastructure such as substations and overhead transmission lines.
Major 2024 awards
In 2023, power generation projects accounted for an estimated 79% of total contract awards, with T&D projects accounting for the rest.
A different picture is emerging in 2024, with data in the first nine months of the year suggesting that generation contract awards are retreating to about 64% of the total. This is due to increased T&D capital spending that has so far driven a 150% increase in award value compared to full-year 2023.
This is a clear indicator of T&D capacity buildout catching up with the generation capacity expansion, especially as larger economies such as Saudi Arabia strive to set up stronger and more efficient electricity links domestically, and as the energy-rich GCC states seek to establish stronger electricity links with one another and with their neighbours, including Egypt, Iraq and Jordan.
Saudi Arabia has dominated the overall Mena power contracts landscape. Its share of 29% in 2022 soared to 61% in 2023 and 67% in the first 10-11 months of 2024.
In May, principal buyer Saudi Power Procurement Company (SPPC) signed two power-purchase agreements with Japan’s Marubeni Corporation for contracts to develop two wind IPPs under the fourth round of the National Renewable Energy Programme (NREP). The Al-Ghat and Waad Al-Shamal wind IPPs have a total combined capacity of 1,100MW.
The contract for a third wind IPP, tendered as part of round four of the NREP, is also expected to be awarded soon.
In June, Saudi sovereign wealth vehicle the Public Investment Fund (PIF) let the fourth batch of solar PV schemes, which it is implementing bilaterally through the Price Discovery Scheme.
A team comprising Acwa Power, PIF-backed Water & Electricity Holding Company (Badeel) and Saudi Aramco Power Company (Sapco), a subsidiary of the state majority-owned oil giant Saudi Aramco, will develop the three solar projects, which will have a total combined capacity of 5,500MW and will require an investment of about $3.3bn.
The Haden solar PV and Muwayh solar power plants, which will each have a capacity of 2,000MW, will be located in Saudi Arabia’s Mecca region. The third project, the 1,500MW Al-Khushaybi solar PV plant, will be located in the Qassim region. The three new solar PV facilities are expected to become operational in the first half of 2027.
In early November, SPPC also announced the winning bidders for the contracts to develop four combined-cycle gas turbine plants comprising the second batch of thermal capacity that it has tendered since 2023. The four plants, located in Riyadh and the Eastern Province, will each have a capacity of 1,800MW and will require an investment of about $2bn each.
A developer consortium comprising the UAE-based Abu Dhabi National Energy Company (Taqa), Japan’s Jera Company and the local Albawani Company successfully bid for the contracts to develop and operate the Rumah 2 and Nairiyah 2 IPPs. Meanwhile, Saudi Electricity Company (SEC), Riyadh-based utility developer Acwa Power and South Korea’s Korea Electric Power Corporation (Kepco) won the contracts to develop and operate the similarly configured Rumah 1 and Nairiyah 1 IPPs.
State utility SEC is also understood to have issued the limited notices to proceed for six greenfield thermal power plants with a total combined capacity of over 16,000MW.
Power generation projects for which final contracts are expected to be awarded before the end of 2024 include:
- Hajr: 3,600MW
- Marjan: 1,800MW
- Riyadh PP12: 1,800MW
- Qurayyah: 3,600MW
- Ghazlan 1: 2,400MW
- Ghazlan 2: 2,900MW
The $5.3bn high-voltage direct current network project connecting the central, western and southern regions of Saudi Arabia was the single largest power contract awarded in Saudi Arabia in 2024.
The UAE, meanwhile, has awarded three key power contracts this year, including for the Al-Ajban solar IPP, which was won by a team of France’s EDF and South Korea’s Korea Western Power Company (Kowepo), and for the Dhafra waste-to-energy project, which a team of Japan’s Marubeni Corporation, Japan Overseas Infrastructure Investment Corporation and Zurich-headquartered Hitachi Zosen Inova is developing.
Dubai Electricity & Water Authority (Dewa) is also understood to have awarded the contract to complete the Jebel Ali K-Station to Egypt-based Power Generation Engineering & Services Company.
 2025 outlook
The Mena power projects pipeline remains robust, with over $45bn-worth of contracts under bid evaluation and another $50bn in the prequalification stage as of late 2024, according to MEED Projects.
Saudi Arabia is likely to remain dominant, particularly if SPPC and the PIF activate a plan by the Energy Ministry to procure 20,000MW of renewable energy capacity annually until it reaches its target for renewables to account for half of its energy production mix by 2030.
Morocco has the second-largest power projects pipeline thanks to several planned schemes to export clean energy and green hydrogen to Europe. Notably, the tender is under way for the country’s first two solar PV plus battery energy storage system (bess) projects, Noor Midelt 2 and 3.
Abu Dhabi also maintains a substantial renewables and gas-fired generation project pipeline. It has several upcoming IPPs with a total combined capacity of over 7,000MW, of which more than 6,000MW is in the tendering stage.
While the procurement process for Saudi Arabia’s first nuclear power plant in Duwaiheen has been delayed, the UAE has plans to procure the next phase of its nuclear power plant project in Barakah.
Green industrial development in steel and aluminium, as is being undertaken in the UAE, is a driver for ongoing clean energy capacity buildout, notes Karen Young, senior research scholar at Columbia University’s Centre on Global Energy Policy.
Egypt, Iran, Kuwait and Iraq have the next largest power projects pipelines. The key drivers in each state vary, with populous countries Egypt and Iran seeking to develop integrated green hydrogen hubs and nuclear power capacity, respectively, while Kuwait remains a promising market with extended plans to procure both conventional and renewable energy capacity to address peak demand.
There are indications that Iraq’s first utility-scale solar PV scheme – a 1GW project being developed by France’s TotalEnergies – will head into the construction stage in the coming months, along with other similar projects for which preliminary agreements were signed by Iraqi authorities in 2021-22.
Oman is actively pursuing renewable energy capacity, with the state offtaker having tendered the contracts for two wind IPPs in September 2024.
In Oman and Qatar, the main downstream companies, Petroleum Development Oman and QatarEnergy, are developing renewable energy capacity as a means of mitigating their greenhouse gas emissions, as well as to support their respective government’s net-zero targets.
In November, Bahrain started the procurement process for its fourth independent water and power project (IWPP) in Sitra, which replaced the previously planned Al-Dur IWPP 3 scheme.

Other trends
SEC affiliate National Grid Saudi Arabia has awarded EPC contracts for several bess packages to local firm Algihaz this year. In August, it tendered a contract for the construction of a further 2,500MW of energy storage capacity.
In parallel, the procurement process is under way for the first independent bess packages in Saudi Arabia and Abu Dhabi, with other utilities expected to follow suit in procuring bess using an IPP model. Bess will boost grid flexibility and spinning reserves in the face of increased renewable energy capacity and demand.
In addition to bess and several gigawatts of solar and wind capacity, Saudi Arabia gigaproject developer Neom, which plans to be powered 100% by renewable energy by the end of the decade, is also considering a network of large-scale pumped hydropower storage plants.
However, despite the ongoing capacity buildout across the Mena states, some end-users – particularly in fossil fuel-
scarce jurisdictions such as Morocco – continue to struggle with supply.
“I’ve been part of a research project in Morocco looking at the renewable power landscape and green economy more broadly. In that case, we do see massive buildout, but it is tailored for offtake to state-related industrials,” says Columbia University’s Young.
She adds that a telephone survey of 1,000 small and medium-sized businesses in Morocco about their perception of the accessibility and affordability of renewable energy yielded surprising results.
“They strongly suggested a lack of support, given that smaller enterprises continue to see power outages and this has in many cases caused damage to their equipment and abilities to stay open and service customers.
“The disconnect between power buildout and industrial advances in a green supply chain and how small and medium firms see power accessibility and reliability is very stark. In a Mena-wide sense, we might start to question how the delivery and transmission of power in an equitable way affects economic growth opportunities overall.”

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Aldar and Mubadala acquire Masdar City Square
17 September 2026
-
 Dubai announces new 80km highway corridor
16 September 2026
-
 Engineering progresses on Ras Laffan LNG terminal berths
16 September 2026
-
 Design completed for Libyan oil field development
16 September 2026
-
 Chinese contractor wins Qiddiya e-games arena
16 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Aldar and Mubadala acquire Masdar City Square
17 September 2026
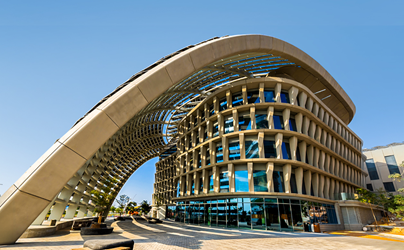
Abu Dhabi-based sovereign wealth fund Mubadala Investment Company and local developer Aldar have completed the acquisition of Masdar City Square at Masdar City, in a transaction valued at AED918m ($250m).
The deal was executed through their joint venture established in 2024.
Masdar City Square comprises more than 47,000 square metres (sq m) of net leasable area across seven office buildings.
Completed in Q1 2026, the development is 99% occupied. Tenants include Taqa, the Department of Energy, Emirates College and the Mohamed Bin Zayed University of Artificial Intelligence.
The transaction expands the joint venture’s real estate portfolio in Masdar City, which is now valued at AED4.7bn ($1.3bn).
Masdar City is one of the region’s leading hubs for clean energy, artificial intelligence, advanced research and sustainable urban development.
The joint venture acquired The Link project at Masdar City for AED654m ($178m) in April.
Comprising about 32,000 sq m of net leasable area across five buildings, The Link is fully leased to a portfolio of major tenants, including Abu Dhabi Future Energy Company (Masdar) and the Mohamed Bin Zayed University of Artificial Intelligence.
The asset includes Grade A, Leed Platinum office space, a net-zero-energy headquarters building, a multi-use hall and residential accommodation, supporting its position as a high-performing, integrated component of Masdar City.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19748241/main5814.png -
Dubai announces new 80km highway corridor
16 September 2026
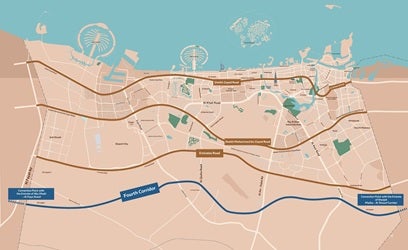
Dubai has approved the construction of the new fourth corridor, a major highway programme aimed at boosting inter-emirate connectivity, increasing road capacity and easing congestion.
The corridor will extend 80 kilometres, from Al-Faya Road in Abu Dhabi to Al-Shanouf Road in Sharjah.
It will include 12 lanes, 72 bridges and 17 tunnels.
The project is expected to reduce travel times by up to 60% and serve more than 3.1 million people, while providing links to Al-Maktoum International airport and Etihad Rail.
It will have the capacity to accommodate 24,000 vehicles per hour in each direction.
The project will be delivered in two phases. The first phase, running from Al-Shanouf Road to Dubai-Al Ain Road, will be delivered at a cost of AED3.5bn ($953m).
The second phase will stretch from Dubai-Al Ain Road to Al-Faya Road in Abu Dhabi.
Hamdan bin Mohammed: In line with the directives of His Highness Sheikh Mohammed bin Rashid Al Maktoum to boost investment in infrastructure, I approved the New Fourth Corridor to strengthen Dubai’s road network and enhance connectivity with the UAE’s federal road network.… pic.twitter.com/zlIyY2yKBN
— Dubai Media Office (@DXBMediaOffice) September 16, 2026
The scheme adds a fourth spine to a network that has long relied on three main corridors: the E11 (Sheikh Zayed Road/Al-Ittihad Road); the E311 (Sheikh Mohamed Bin Zayed Road) and the E611 (Emirates Road), which together carry more than 850,000 vehicles commuting between Dubai and the northern emirates daily.
That concentration has made the route one of the country’s most congested, with peak-hour bottlenecks a persistent problem for residents. The new corridor is designed to divert a significant share of that traffic onto a higher-capacity route, rather than add pressure to the existing network.
The project also aligns with the Dubai 2040 Urban Master Plan, which anticipates population growth to 5.8 million by 2040 and calls for the expansion of roads, railways, airports and ports to support that growth and reinforce Dubai’s position as a global trading hub. This is reflected in the corridor’s direct links to Al-Maktoum International airport and Etihad Rail.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19725878/main.jpeg -
Engineering progresses on Ras Laffan LNG terminal berths
16 September 2026
Register for MEED’s 14-day trial access
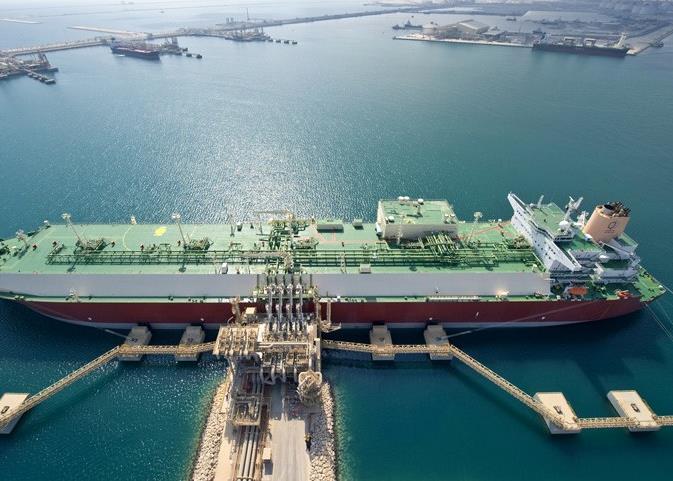
Front-end engineering and design (feed) works are progressing on a QatarEnergy LNG project to build 13 liquefied natural gas (LNG) loading berths at the south export terminal in Qatar’s Ras Laffan Industrial City.
Ras Laffan Industrial City, which lies about 90 kilometres north of Doha, is the world's largest integrated LNG production and export complex, comprising 15 processing trains with a total capacity of 77.5 million tonnes a year (t/y). QatarEnergy began LNG operations at the facility, which houses all its processing trains and export infrastructure, in 1984.
According to sources, QatarEnergy LNG, a subsidiary of state enterprise QatarEnergy, awarded the feed contract for the project to build 13 LNG berths at the south export terminal at Ras Laffan to Australia-headquartered Worley.
The contract was awarded to Worley in the second quarter of this year. Its duration is estimated to be 200,000-250,000 man hours, sources told MEED.
Ras Laffan’s LNG processing and export capabilities will increase by up to about 63% when the three phases of QatarEnergy’s estimated $40bn North Field LNG expansion project come into operation by the end of this decade. Engineering, procurement and construction (EPC) works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million t/y to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the engineering, procurement, construction and installation of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on the third phase, North Field West (NFW), this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the feed work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19715235/main5946.jpg -
Design completed for Libyan oil field development
16 September 2026
Register for MEED’s 14-day trial access
Design work has been completed for a project to develop Libya’s I/R oil field, according to industry sources.
The front-end engineering and design work was completed by a team in the London offices of Italy’s EniProgetti and paves the way for the main engineering, procurement and construction contract to be tendered.
One source said: “At the moment, there is no fixed date for when the invitation to bid for the main contract will be issued, but the project has a lot of momentum and is progressing towards tendering.”
The I/R oil field is located in Murzuq Basin in southwestern Libya.
In June this year, Libya's National Oil Corporation (NOC) signed a unified operating agreement for the field.
The I/R field is operated by Akakus Oil Operations, which is a joint venture of NOC in partnership with Spain’s Repsol, France’s TotalEnergies Repsol, Austria’s OMV and Norway’s Equinor.
The agreement in June was signed by NOC as well as its concession partners.
NOC said the agreement would unify operational and administrative procedures related to field management, optimise resource utilisation and support production sustainability.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19711588/main.jpg -
Chinese contractor wins Qiddiya e-games arena
16 September 2026
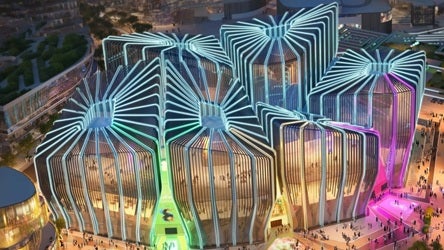
Saudi gigaproject developer Qiddiya Investment Company (QIC) has awarded an estimated $500m-$600m contract to build an e-games arena, also known as the Fortress Arena, at its Qiddiya Entertainment City development outside Riyadh.
The contract was awarded to Beijing-headquartered Metallurgical Corporation of China.
The scope of work covers the construction of an auditorium with a capacity of about 5,100 seats, as well as commercial areas, hospitality facilities and other associated infrastructure.
The e-games arena will provide space for local, national and international competitions.
MEED understands that QIC tendered the contract in January, with bids submitted in March.
Completion is expected by April 2029.
US-based architectural firm Populous designed the project, supported by New York-based Thornton Tomasetti.
The project is located in District 18, Upper Plateau, in Qiddiya City.
The Fortress Arena is one of several major projects within the wider Qiddiya development.
Other projects include the Dragon Ball theme park, Prince Mohammed Bin Salman Stadium, a horse racing venue, a performing arts centre, the Speed Park, the National Tennis Centre and the Six Flags theme parks and Aquarabia waterpark.
The project is a key part of Riyadh’s strategy to boost leisure tourism in the kingdom. According to UK analytics firm GlobalData, leisure tourism in Saudi Arabia has grown significantly in recent years.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19661939/main.jpg