Mena power rides high into 2024
29 December 2023

The Middle East and North Africa (Mena) region’s power generation and transmission sector awarded an estimated $25.3bn-worth of contracts between January and November 2023.
While this pales in comparison to the record high of $37.7bn awarded in 2015, it is up 38 per cent on the previous full year 2022, according to MEED Projects.
Year-on-year, the value of awarded power generation contracts increased by 40 per cent to reach $19bn, outperforming the transmission sub-sector growth by nine percentage points.
Saudi Arabia accounted for 60 per cent of the awarded power contracts in 2023. These include the contracts to develop four independent power projects (IPPs) that use combined-cycle gas turbines (CCGT), the first to be procured since the kingdom awarded the contract to develop the 1,500MW Al-Fadhili IPP to France’s Engie in 2016.
The Taiba 1 and 2 and Qassim 1 and 2 IPP projects each have a generation capacity of 1,800MW and require a combined investment of $7.8bn, of which roughly 80 per cent is accounted for by engineering, procurement and construction (EPC) costs.
The kingdom also awarded an EPC contract for the 1,200MW expansion of a power plant complex in Jubail during the year.
On the renewable energy front, the principal buyer, Saudi Power Procurement Company (SPPC), and the Public Investment Fund awarded some 6.7GW of solar photovoltaic (PV) IPP projects.
The uptick in awards marks a major improvement after a year of tepid renewables project activity in 2022, barring the solar and wind farm projects being developed as part of the large-scale green hydrogen and ammonia project in Neom.
The transmission and distribution sub-sector contributed to Saudi Arabia’s sterling market performance this year, delivering contracts worth over $3.5bn.
 The kingdom’s electricity grid is expected to continue to be upgraded to accommodate growing renewable energy capacity and the rise in electricity demand as Vision 2030-related projects enter the execution phase.
The plan to accelerate electricity trade with its GCC neighbours and other countries in the region, such as Egypt and Iraq, is also anticipated to encourage future grid investments.
The award of the $2bn multi-utilities package for the Amaala development project also stood out, not least due to the inclusion of a 700 megawatt-hour battery energy storage system to enable the hotels within the development to be completely off-grid.
Unlike in the previous two years, Kuwait, the UAE and Oman also tendered or awarded substantial power generation contracts in 2023.
Nama Power & Water Procurement Company awarded the contracts to develop the second and third utility-scale solar PV schemes in the sultanate, Manah 1 and 2, each with a capacity of 500MW, in the first half of the year.
In September, Dubai Electricity & Water Authority awarded the contract to develop the sixth phase of the Mohammed bin Rashid solar complex.
Looking forward
The Mena power sector is expected to maintain its momentum into 2024, if the final quarter of 2023 is anything to go by.
Saudi Arabia is likely to continue dominating power project activities, with other states such as the UAE, Oman, Morocco, Egypt, Kuwait and Qatar offering significant opportunities for developers and EPC contractors.
Saudi Arabia’s SPPC has held a market-sounding event for the four solar IPPs under the fifth round of the kingdom’s National Renewable Energy Programme (NREP), while bid evaluation is still under way for the three wind IPPs under the NREP’s round four.
The tender documents are also being prepared for two CCGT projects in Riyadh, PP15 and Al-Khafji, with each expected to have a capacity of 3.6GW.
Qatar and Kuwait are advancing the procurement process for independent water and power producer (IWPP) projects that were held back over the past few years.
Abu Dhabi has initiated the procurement process for its fourth solar PV IPP and first twin battery energy storage facilities.
It will also almost certainly kick off the procurement process for one or two thermal power plants in the months ahead in anticipation of the need to replace expiring gas-fired capacity.
North Africa
The procurement of renewable energy plants, particularly in the North African states, led by Egypt and Morocco, is also expected to ramp up, in part due to their goals to develop green hydrogen hubs and export clean energy to Europe.
“Morocco is definitely going to be a major market from 2024 and onwards, with several IPPs in the planning and study stage,” says a senior partner with a transaction advisory firm.
Expectations also continue to thrive for many thermal projects planned in Libya and solar PV IPPs in Iraq, despite political uncertainties.
For Iraq in particular, the external pressure to rely less on Iranian electricity imports will provide impetus to its solar and CCGT capacity programmes.
The future trend for levelised costs of electricity is likely to remain mixed over the coming months
LCOE trend
The future trend for levelised costs of electricity (LCOEs) – or the pre-agreed, long-term tariffs an offtaker pays utility developers for their plants’ electricity output – is likely to remain mixed over the coming months, according to a region-based expert.
“The LCOEs for CCGTs are likely to remain stable next year, while solar LCOEs could slightly decline, compared with those seen in 2023,” the source tells MEED.
Supply chain constraints for gas turbines remain a concern for future CCGT power plants, given what is understood to be a long lead time for delivery and the production capacity constraints in the EU plants of the leading suppliers such as Germany’s Siemens Energy and the US’ GE.
While this opens opportunities for gas turbine manufacturers based in China, it is foreseeable that there remains a dominant preference for EU-made products across the Mena region, particularly in the GCC states.
The same expert argues, however, that the massive increase in gas turbine demand may be temporary, with demand likely to start petering off sometime after 2024, when clients and utility developers alike will have to consider the impact of these assets, whose concession agreements extend between 25 and 30 years, to their net-zero commitments.
As previously cited, Saudi Arabia will continue to dominate the region’s power sector project activities in the foreseeable future. Its ambition for renewable energy sources to account for half its capacity by 2030 and the Vision 2030-related plans to build off-grid developments such as Neom, the Red Sea and Amaala, as well as its multibillion-dollar industrialisation programme, will drive this.
According to MEED Projects data, Iran, Algeria, Kuwait, the UAE and Qatar are the other key markets for projects in the bidding stage. Morocco, Egypt, Kuwait and the UAE are the most promising markets for projects outside Saudi Arabia in the study, design or prequalification stage.
Overall, the net-zero commitments made by key states such as Saudi Arabia and the UAE, and plans to build green hydrogen valleys from Abu Dhabi to Morocco, in addition to an endemic rise in electricity demand as populations and economies grow, will likely keep the overall power sector buoyant over the coming years, barring any major events, like the Covid-19 pandemic in 2020 or the Russia-Ukraine war in 2022.
 Sustainability drives water investments

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Kuwait halves drilling contractor pool
22 September 2026
-
 Abu Dhabi expects 45% emissions cut as electricity demand rises
21 September 2026
-
 Seven bid for Bahrain highway upgrade
21 September 2026
-
 Teams prepare bids for Oman PPP wastewater project
21 September 2026
-
 Oman reveals Sohar airport and Salalah Thumrait Road plans
21 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
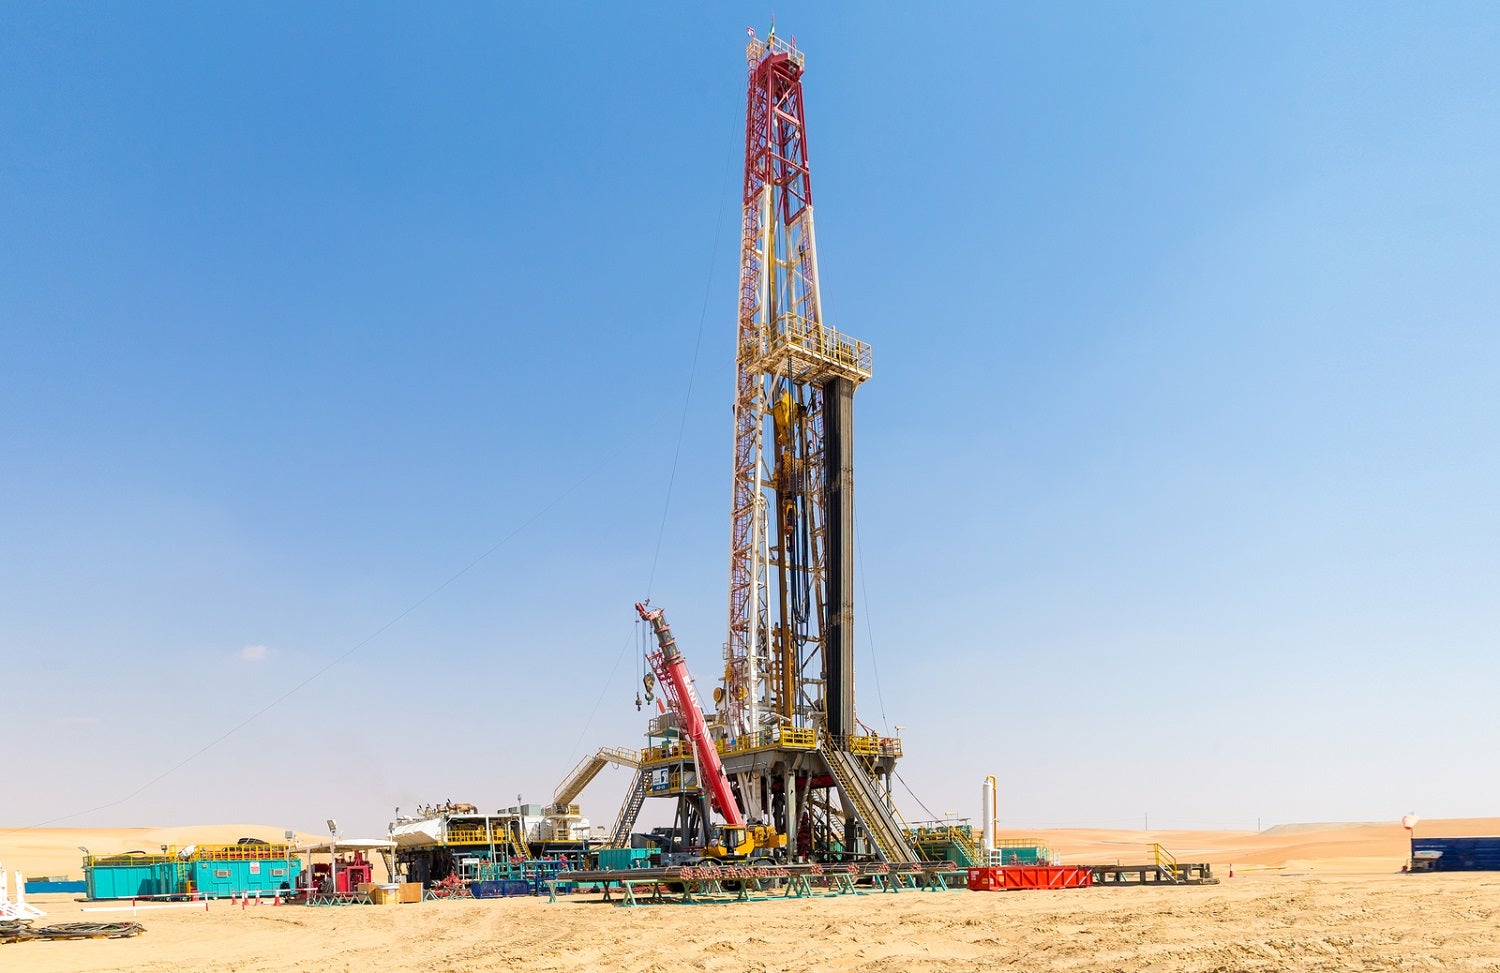
Kuwait halves drilling contractor pool
22 September 2026
State-owned upstream operator Kuwait Oil Company (KOC) has reduced the number of approved contractors for onshore drilling and shallow-well maintenance from 51 to 24.
Firms that are no longer qualified include major contractors such as Italy’s Saipem, Oklahoma-based Helmerich & Payne and Houston-based Patterson-UTI Energy.
The latest list still includes a wide range of Kuwaiti, regional and international companies, according to the latest update on its electronic system, published on 21 September 2026.
The full list of contractors that are now qualified to participate in tenders is:
- Burgan Company for Well Drilling, Trading & Maintenance (Kuwait)
- Kuwait Drilling Company (Kuwait)
- Sun Drilling Kuwait (Kuwait)
- TDL Kuwait for Oil Rigs & Natural Gas Extraction Activities, Services and Facilities (Kuwait)
- United Precision Drilling (Kuwait)
- Abraj Energy Services (Oman)
- Adnoc Drilling Company (UAE)
- Arabian Drilling Company (Saudi Arabia)
- Anton Oilfield Services (China)
- China Oilfield Services (China)
- Egyptian Drilling Company (Egypt)
- CNPC Bohai Drilling Engineering Company (China)
- Great Wall Drilling Company (China)
- John Energy (India)
- Kerui Oilfield Service (China)
- KCA Deutag Drilling (Germany)
- Mohammed Al-Barwani Petroleum Services (Oman)
- Nabors Drilling International (US)
- National Drilling & Services Company (Oman)
- Sea & Land Drilling Contractors (Oman)
- Sinopec International Petroleum Service Corporation (China)
- Karamay Jianye Energy (China)
- Modern Drilling Company (Egypt)
- Grey Wolf Drilling International (US)
An earlier list, which was published on 11 February, included 51 qualified companies.
The reduction in qualified drilling contractors follows KOC’s notice on 27 April this year, informing existing qualified contractors that they would need to reapply.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19863744/main3435.jpg -
Abu Dhabi expects 45% emissions cut as electricity demand rises
21 September 2026
Register for MEED’s 14-day trial access
Abu Dhabi-based Emirates Water & Electricity Company (Ewec) expects carbon emissions from power and water production to fall by more than 45% by 2035 as the UAE expands renewable energy and reverse osmosis (RO) desalination.
The state offtaker's latest long-term system planning forecasts emissions will decline from about 42 million tonnes in 2019 to approximately 23 million tonnes in 2035.
The reduction is expected despite annual electricity demand that is forecast to rise by about 70% in 2026-33.
Ewec said the expansion of renewable energy and the shift towards RO desalination will be the principal drivers of the reduction.
The company plans to increase Abu Dhabi's solar capacity to 14GW by 2030 and more than 35GW by 2035. This will be supported by up to 15GW of battery storage capacity.
According to regional project tracker MEED Projects, Ewec has over $16bn-worth of power and water projects in the execution stage as part of its long-term procurement programme to increase renewable energy and low-carbon water production capacity.
This includes a 5.2GW Abu Dhabi solar and battery energy storage system (bess) round-the-clock renewable energy project, as well as three 1.5GW solar photovoltaic independent power projects (IPP): Al-Ajban, Al-Khazna and Al-Zarraf.
It also comprises the 1GW Al-Dhafra open-cycle gas turbine power plant, the 2.5GW Taweelah C combined-cycle gas turbine (CCGT) plant and a separate 400MW bess IPP.
As previously reported, it is expected that the developer's agreement for the 3.3GW Al-Nouf 1 CCGT IPP will be signed by the end of the year, while contractors are preparing to submit bids for a separate 2.6GW power plant project in Ajman.
The expansion of solar and battery storage is expected to reduce the system's reliance on gas-fired generation. However, gas-fired generation will continue to provide flexibility to support the system and balance intermittent renewable power output, according to Ewec.
The offtaker also expects RO desalination to account for more than 95% of total water production by 2035, with the procurement programme supporting the Abu Dhabi Department of Energy's Clean Energy Strategic Target 2035 for electricity production and the UAE Net Zero by 2050 Strategy.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19849749/main.jpg -
Seven bid for Bahrain highway upgrade
21 September 2026
Register for MEED’s 14-day trial access
Seven contractors have submitted bids for the next phase of the Sheikh Jaber Al-Ahmed Al-Sabah Highway upgrade project.
According to results published by the Bahrain Tender Board, the firms that have submitted bids include:
- Nass Contracting Company
- Haji Hassan Group
- Almoayyed Contracting Group
- Mohammed Abdulmohsen Al-Kharafi & Sons
- Eastern Asphalt & Concrete Production
- Cebarco Bahrain
- Kingdom Asphalt
The contract scope includes expansion works on 2 kilometres of the highway. It consists of a four-lane dual carriageway with service roads on both sides.
The scope of works also includes excavation and backfill work, construction of stormwater drainage networks, a pumping station, installation of ducts for future utilities, upgraded street lighting, traffic signs and directional signage.
The project aims to improve traffic capacity, reduce congestion and enhance safety along the transport corridor linking Manama with industrial zones.
In April, MEED reported that Bahrain had approved a financing agreement framework to fund the construction of the next phase of the Sheikh Jaber Al-Ahmed Al-Sabah Highway upgrade.
In March last year, the Kuwait Fund for Arab Economic Development and the Bahraini government signed a KD10m ($32.4m) loan agreement to fund the second phase of the project, which is expected to cost about $404m.
This was followed in September 2025 by the appointment of US-based Parsons Corporation on a $1.5m contract to provide pre-contract engineering consultancy services for the project.
According to data from regional project tracker MEED Projects, construction of the first phase was completed in 2020.
A joint venture of local firm Nass Contracting and Kuwait’s KCC Engineering & Contracting undertook the main construction works.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19847073/main.png -
Teams prepare bids for Oman PPP wastewater project
21 September 2026
At least three consortiums are preparing bids for a contract to develop and operate two major sewage treatment plants (STPs) in Oman.
The public-private partnership (PPP) project covers expanding two Muscat-based plants: the Al-Ansab STP (phase three) and the Al-Amerat STP (phase two). It will be delivered under a build-own-operate-transfer model.
At Al-Ansab, capacity will increase from 125,000 cubic metres a day (cm/d) to 207,000 cm/d. At Al-Amerat, capacity will rise from 18,000 cm/d to 54,000 cm/d.
According to sources, the bidders for the project include:
- Etihad Water & Electricity (UAE) / Metito (UAE)
- Lamar Holding (Bahrain) / Tawzea (Saudi Arabia)
- Civil Works Company (CWC, Saudi Arabia) / Suez (France)
The bid submission deadline is 5 January 2027.
State-owned Nama Water Services (NWS) issued a request for proposals for the project in July, as exclusively reported by MEED.
It is understood that Veolia (France), Miahona (Saudi Arabia) and Samsung E&A (South Korea) are also among the firms that prequalified for the project after the request for qualifications was issued last November.
The project scope includes the design, financing, construction, operation and maintenance of the new facilities, alongside the long-term operation of the existing facilities.
It has been over a decade since the Al-Ansab STP first entered full operation at a capacity of about 54,000 cm/d. In 2015, South Korea’s Doosan Ennerbility, formerly Doosan Heavy Industries, was awarded the main engineering, procurement, and construction contract for the phase two expansion, which increased the facility’s maximum flow capacity to 125,000 cm/d. This phase was completed in 2017.
Phase one of the Al-Amerat STP was awarded to a joint venture of France’s Degremont (Suez) and local contractor Al-Ansari Trading Enterprise under a design, build and short-term operation contract valued at about €50m ($58.1m). The plant was developed for Haya Water and commissioned in 2019 as part of the Muscat wastewater scheme.
Haya Water, the former wastewater utility, was later incorporated into NWS following a government restructuring programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/19794912/main.jpg -
Oman reveals Sohar airport and Salalah Thumrait Road plans
21 September 2026
Oman is planning a new passenger terminal at Sohar Airport to expand regional air connectivity and strengthen the airport’s role in the national aviation network.
According to Said Bin Hamoud Al-Maawali, Oman’s minister of transport, communications and information technology, new routes are expected to be announced before the end of the year. Potential destinations include Dammam in Saudi Arabia, Gwadar in Pakistan, and southern Iran.
The planned terminal and additional routes will give residents of northern Oman more travel options.
Al-Maawali also provided an update on the long-delayed Salalah-Thumrait truck road, saying the project will be procured through a conventional tendering model rather than a public-private partnership (PPP).
In August 2023, Oman shortlisted five of eight prequalified teams to compete for the Salalah-Thumrait truck road project, which was set to be the sultanate’s first PPP road project.
The 67-kilometre road project is specially designed for heavy vehicles.
The road is a key link in Dhofar’s transport network, connecting Thumrait with Salalah and supporting movement between the interior and the governorate’s main urban and economic centre.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19794881/main.jpg