Mena clean energy pipeline climbs to 246GW
14 February 2025

Some 47.4GW of clean and renewable energy power generation plants are under construction across 15 countries in the Middle East and North Africa (Mena) region.
Based on the latest available data from MEED and MEED Projects, a further 199GW are in the study, design, prequalification and bid stages.
The total pipeline of 246GW is close to half of renewable energy capacity additions globally, which stood at 510GW in 2023.
Saudi Arabia leads with some 17.7GW of renewable energy capacity under construction, mainly comprising an estimated 16.5GW of capacity from solar power plants, which were procured under a public tendering process as well as direct negotiations. Wind power accounts for the rest.
Egypt is the second-largest market, with under-construction projects including the first two units of the El-Dabaa nuclear power plant in Matrouh and some 3GW of solar and 3.8GW of wind power plants.
Iran has the third-largest clean energy capacity under construction, including over 3.4GW of hydropower and 2.4GW of nuclear power.
The UAE ranks fourth, with a total of 3.7GW of capacity under execution. These projects include the 1.5GW Al-Ajban solar photovoltaic (PV) plant in Abu Dhabi, the 1.8GW phase 6 of Dubai’s Mohammed Bin Rashid Al-Maktoum Solar Park project, the 250MW hydropower plant in Dubai and a waste-to-energy project in Abu Dhabi.
Morocco’s capacity under construction is estimated at around 3.6GW, dominated by solar power plants, which have a cumulative capacity of roughly 2.8GW.
Overall, solar PV projects – some in combination with battery energy storage system plants – account for 32GW or close to 68% of the capacity under construction across the Mena region.
Wind and nuclear account for 14% and 10% of the total, respectively, with hydropower plants accounting for 8.4%.
An estimated 9.4GW of the projects under execution, mostly solar, are due to be completed this year. A further 11.9GW are set to be delivered in 2026, and 23GW by 2027. The rest, including the first reactors of the El-Dabaa nuclear power plant in Egypt, are expected to be completed in 2028 or beyond.
This implies that electricity from clean and renewable power sources is set to become a substantial part of the region’s energy mix, particularly in the states that have been cited.
The known solar PV installed capacity in the Middle East, for instance, is estimated to be around merely 18GW as of 2023.
It could also imply that the targets for clean and renewable sources to account for 50% or more of the electricity production mix in certain Mena countries may be achievable, with the region’s largest economy, Saudi Arabia, aiming to procure 20GW of renewable energy annually until it reaches the new target of up to 130GW by 2030 “subject to demand growth”.
Pre-execution
The pipeline of pre-execution projects is equally impressive, potentially yielding an electricity production capacity of close to 200GW, if all these planned projects are implemented.
Most of these projects are envisaged to be grid-connected and exclude captive renewable energy plants catering to industries or enterprises, or those announced as part of integrated green hydrogen and ammonia production facilities.
Saudi Arabia has the largest pre-execution pipeline of over 83GW. This includes around 55GW of capacity in the conceptual stage, catering to the Neom gigaproject, the $500bn masterplan northwest of the kingdom that aims to be powered 100% by renewable energy.
Saudi Arabia’s clean and renewable energy pipeline, inclusive of the Duwaiheen nuclear plant project, is larger than the planned capacity across the next four largest markets: Egypt, Morocco, the UAE and Iraq.
Notably, roughly a quarter of the pre-execution projects in Saudi Arabia are in the prequalification and bidding stages, whereas a mere 3.2% of the planned projects in Egypt have so far reached these stages.
In Morocco, a project called Xlinks, which aims to deliver clean energy to the UK, accounts for about half of the renewable energy capacity being planned.
In the UAE, some 19% of the $16.4bn pre-execution projects are in the prequalification and bid stages. The bulk of capacity in the design stage includes the next phase of the Barakah nuclear power plant as well as the round-the-clock solar PV and battery energy storage system (bess) plant facility in Abu Dhabi.
The 5.2GW solar /19GWh bess project in Abu Dhabi, estimated to require an investment of $6bn, is expected to reach financial close in Q2, which means it will rapidly move from design to execution. Abu Dhabi Future Energy Company (Masdar), the project’s main developer, has already selected the engineering, procurement and construction and other sub-contractors for the project.
Risks and opportunities
The massive renewable capacity buildout across the major Mena region is expediting the procurement of bess plants, whether independently by the transmission and distribution (T&D) entities – as exemplified by recent projects in Saudi Arabia – or in combination with a solar PV project, such as the UAE’s 1GW round-the-clock solar project.
Batteries will help boost the flexibility of the electricity grids as more intermittent renewable power is added and overall demand increases.
The rapid decline in battery unit prices has helped bring several bess projects with substantial capacities to the market over the past 12 to 18 months, and this pace is expected to further accelerate in the future.
Yet, batteries alone will not be sufficient to address the peak electricity demand, particularly across the GCC states, which some experts say falls between 6:00 pm and 6:00 am, especially in the summer months, coinciding with a period when solar PV plants do not produce power and where only a very limited wind capacity may be available.
“There is no doubt batteries can help address that gap, but maybe not to the extent some may envisage,” notes a Dubai-based industry source.
“The issue is not the unit price of batteries, but the volume that you need to address that gap and how much it would cost. Depending on the configuration and the volume of batteries installed, you have bess systems that can provide five to six hours of storage today,” he explains. “The big question is how will the grid cope with the surge in electricity demand at 6 am?”
Given that the cost of lithium-ion batteries was considered highly prohibitive as recently as a year ago, the expectation is that the scale of new projects and demand will continue to drive rapid innovations to enable more flexible grids during the energy transition.
 READ THE FEBRUARY MEED BUSINESS REVIEW
Trump unleashes tech opportunities; Doha achieves diplomatic prowess and economic resilience; GCC water developers eye uptick in award activity in 2025.
Published on 1 February 2025 and distributed to senior decision-makers in the region and around the world, the February MEED Business Review includes:
|
> AGENDA 1: Trump 2.0 targets technology
> AGENDA 2: Trump’s new trial in the Middle East
> AGENDA 3: Unlocking AI’s carbon conundrum
> GAZA: Gaza ceasefire goes into effect
> LEBANON: New Lebanese PM raises political hopes
> WATER DEVELOPERS: Acwa Power improves lead as IWP contract awards slow
> WATER & WASTEWATER: Water projects require innovation
> INTERVIEW: Omran’s tourism strategies help deliver Oman 2040
> PROJECTS RECORD: 2024 breaks all project records
> REAL ESTATE: Ras Al-Khaimah’s robust real estate boom continues
> QATAR: Doha works to reclaim spotlight
> GULF PROJECTS INDEX: Gulf projects market enters 2025 in state of growth
> CONTRACT AWARDS: Monthly haul cements record-breaking total for 2024
> ECONOMIC DATA: Data drives regional projects
> OPINION: Between the extremes as spring approaches
|

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Saudi Arabia raises electricity tariffs
26 October 2026
-
 Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
-
 Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
-
 Morocco plans second high-speed rail phase to Agadir
26 October 2026
-
 Riyadh tenders King Salman Stadium works
26 October 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Saudi Arabia raises electricity tariffs
26 October 2026
Saudi Energy, formerly Saudi Electricity Company, has announced revised electricity tariffs, which will take effect on 1 January 2027.
The revised tariff schedule, published on the company’s official website, covers residential, commercial, industrial, agricultural, charitable and government customers.
The largest percentage increase in consumption rates is 16.7%, for residential customers using up to 6,000 kilowatt-hours (kWh) a month. Residential customers will pay 21 halalas/kWh for monthly consumption of up to 6,000kWh, up from 18 halalas. For consumption above 6,000kWh, the rate will rise from 30 to 33 halalas/kWh, a 10% increase.
The industrial tariff will increase by 15%, from 20 to 23 halalas/kWh. Commercial customers, private healthcare facilities and private educational facilities will pay 25 halalas/kWh, up from 22 halalas, for consumption up to 6,000kWh a month, and 35 halalas/kWh above that level, up from 32 halalas.
Tariffs for charities and government customers will also increase. In addition to consumption-based charges, customers will pay a fixed monthly fee based on the capacity of their electricity meter. This replaces the previous separate charge for meter reading, maintenance and billing, with VAT applied to the revised tariffs.
Electricity investment
The new tariffs coincide with changes to water consumption tariffs announced by the National Water Company, also effective from 1 January 2027.
King Salman Bin Abdulaziz Al-Saud directed support measures following a proposal presented by Crown Prince and Prime Minister Mohammed Bin Salman Bin Abdulaziz Al-Saud.
This includes raising the minimum wage required for Saudi nationals to count as full employees towards private sector localisation quotas under the Nitaqat programme.
The tariff changes come as Saudi Arabia plans substantial investment in its electricity infrastructure. In September 2025, Saudi Energy announced plans to invest SR220bn ($58.7bn) in power infrastructure projects between 2025 and 2030.
A June 2025 report by Fitch Ratings forecast negative free cash flow of about SR16bn a year over the period and rising leverage, reflecting the financial demands of the programme.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20924301/main.jpg -
Dubai Municipality confirms AED3bn Tasreef drainage awards
26 October 2026
Dubai Municipality has confirmed it has awarded four contracts worth AED3bn ($817m) to expand the emirate’s stormwater drainage network by about 100 square kilometres under phase three of the Tasreef programme.
The projects will cover Jumeirah, Umm Suqeim, Al-Quoz, Al-Barsha, Al-Wasl and Al-Marmoom. The works include constructing and extending main stormwater drainage lines with diameters of up to three metres.
The four packages are part of Dubai’s AED30bn Tasreef programme, which aims to increase the emirate’s stormwater drainage capacity by 700% and reduce costs associated with pumping stations, network operations and maintenance by 20%.
The contracts have been awarded to China State Construction Engineering Corporation (CSCEC) and three local firms: Arifco Group, Nael Construction & Contracting (NCC) and Detech Contracting. Dubai Municipality did not state which projects the awards relate to.
According to sources, the contract awards include packages TF-15-C1, TF-15-C2 and TF-13-C1.
The first package, TF-15-C1, involves the construction of 21 kilometres of main and secondary drainage lines along Al-Wasl Road and in surrounding areas. It will cover Za’abeel 2, Al-Wasl, Jumeirah 1 and 2, Al-Bada’a, Al-Satwa and Dubai World Trade Centre. The estimated $100m contract was awarded to Detech in July, as exclusively reported by MEED.
The second package, TF-15-C2, covers the corridor between Sheikh Zayed Road and Al-Khail Road. It includes about 14km of main drainage lines serving Al-Quoz Industrial Areas 1, 3 and 4, and Al-Barsha 1. In July, MEED reported that CSCEC had won the engineering, procurement and construction contract for this project.
The third package, TF-13-C1, covers Al-Marmoom, where 23km of drainage infrastructure will be developed. According to a source, Arifco has been awarded this contract.
The final package covers Jumeirah and Umm Suqeim, where about 42km of main drainage lines will serve Umm Suqeim 1, 2 and 3; Umm Al-Sheif; Jumeirah 3; Al-Safa 1 and 2; and Al-Manara.
In May, MEED reported that NCC had been awarded a contract to build a sewage and stormwater drainage system, DS-204. However, it is unconfirmed whether this relates to the same project.
Earlier, in February, the municipality confirmed it had awarded contracts for five new projects under phase two of the programme to expand and strengthen Dubai’s stormwater drainage network.
These included two contracts awarded to Detech and one to CSCEC for stormwater drainage infrastructure. In addition, two consultancy contracts were awarded for the study and design of drainage systems in selected areas across the emirate.
Cumulatively valued at AED2.5bn, the new projects will serve 30 vital areas, spanning approximately 430 million square metres and supporting an estimated population of three million residents by 2040.
Previously, in April 2025, an earlier package of awards was announced under phase one of the Tasreef programme. The overall masterplan aims to expand Dubai’s rainwater drainage capacity by 700% by 2033.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923924/main4827.jpg -
Nakheel awards $259m Dubai Islands buildings contract
26 October 2026
Dubai-based master developer Nakheel, part of Dubai Holding Real Estate, has awarded local firm Parkway International Contracting a construction contract valued at about AED950m ($259m) for phases two and four of Bay Grove Residences on Dubai Islands.
The package covers 617 residential units across eight buildings, ranging from one to four bedrooms, together with basement structures, infrastructure and community amenities including swimming pools, sports courts and fitness centres.
Phase two comprises 360 homes across four buildings, with main construction scheduled for completion in late 2028.
Phase four includes 257 homes across four buildings, with completion targeted for the second quarter of 2029.
The award follows an earlier contract valued at about AED800m ($218m) awarded to local contractor Metac General Contracting Company for phases one and three, covering 537 homes across seven buildings.
Together, the two contracts total more than AED1.75bn ($476m) and account for all 1,154 planned homes across the 15 buildings of Bay Grove Residences.
Project activity on Dubai Islands has gathered pace in recent months. Earlier this month, Nakheel awarded local firm Mar Marine & Building Contracting a contract for marine and coastal works on Island B. The scope includes constructing breakwaters, removing existing rock revetments and creating a new 320-metre beach near the Bay Villas development, as well as remedial and refurbishment works along approximately 3 kilometres of the island’s western shoreline.
In August 2025, Nakheel awarded Fibrex Contracting a AED2.6bn ($708m) construction contract for the Bay Villas residential project. That followed a AED527m ($143m) contract awarded to Al-Nasr Contracting Company in April 2026 for primary infrastructure and utilities on Island B.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20923389/main.jpg -
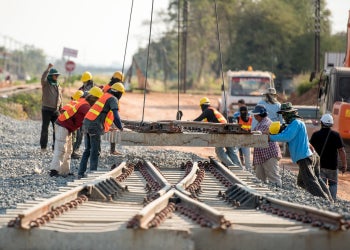
Morocco plans second high-speed rail phase to Agadir
26 October 2026
Morocco has outlined a second rail investment cycle for 2030-35, which includes beginning construction of a high-speed rail extension from Marrakech to Agadir and connecting Essaouira to the national rail network.
The pipeline forms part of the government’s 2026-31 programme, presented to parliament last week.
The Marrakech-Agadir link is estimated to cost close to MD55bn ($5.5bn) and will cover a 240-kilometre (km) route through the High Atlas Mountains via Chichaoua. Civil engineering structures, including tunnels and viaducts, are expected to account for nearly 70% of the alignment.
In September, the government issued a decree declaring the Marrakech-Agadir and Chichaoua-Essaouira rail corridors to be of public utility, paving the way for land acquisition and expropriation procedures.
Under the long-term masterplan Plan Rail Maroc 2040, Essaouira is expected to connect to the network via a separate line branching off at Chichaoua, designed for operating speeds of up to 200km an hour. The mainline to Agadir is designed for speeds of up to 320km/h.
The 2030-35 cycle also includes rehabilitating the Casablanca-Khouribga-Oued Zem line; constructing a new line between Oued Zem and Beni Mellal via Bejaad, with a branch to Fquih Ben Salah; doubling and upgrading the 140km Benguerir-Safi line; expanding capacity on the Fez-Oujda corridor; and building new-generation passenger stations.
The plans follow Morocco’s ongoing MD134bn ($13.4bn) 2024-30 rail investment programme, which focuses on completing the Kenitra-Marrakech high-speed line ahead of the 2030 Fifa World Cup.
The programme also includes developing regional express network services across five regions, electrifying the Fez-Oujda line and completing a freight rail link to the Nador West Med port.
Work on the Kenitra-Marrakech line had reached about 30% by May 2026, with commercial services targeted to begin in September 2029.
https://image.digitalinsightresearch.in/uploads/NewsArticle/20920349/main.jpg -
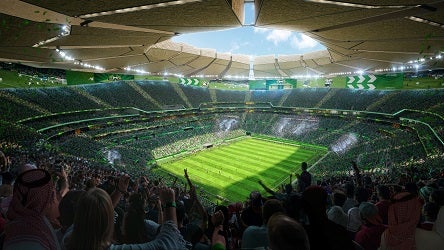
Riyadh tenders King Salman Stadium works
26 October 2026
Register for MEED’s 14-day trial access
Saudi Arabia’s Sports Ministry has tendered a contract covering early works at King Salman International Stadium in Riyadh.
The scope includes enabling works, site preparation and initial construction activities.
The tender was issued on 11 October, with a submission deadline of 19 November.
The stadium will cover about 660,000 square metres (sq m) and seat 92,000. Facilities will include a 150-seat royal suite, 120 hospitality suites, 300 VIP seats and 2,200 dignitary seats.
The wider development will include sports facilities covering more than 360,000 sq m, including two training fields and fan zones; a closed sports hall; an Olympic-sized swimming pool; an athletics track; and outdoor courts for volleyball, basketball and padel.
The stadium is set to host the final of the 2034 Fifa World Cup and will serve as the Saudi national football team’s main base.
US-based architectural firm Populous is the lead architect for the stadium.
Construction of the stadium is expected to be completed by 2029.
The stadium will be located next to King Abdulaziz Park.
Firms submitted prequalification statements for the main design-and-build contract in February.
Saudi stadium plans
In August 2024, MEED reported that Saudi Arabia planned to build 11 new stadiums and refurbish four facilities for the 2034 Fifa World Cup.
Eight stadiums will be located in Riyadh, four in Jeddah and one each in Al-Khobar, Abha and Neom.
A further 10 cities will host training bases: Al-Baha, Jazan, Taif, Medina, Alula, Umluj, Tabuk, Hail, Al-Ahsa and Buraidah.
There are expected to be 134 training sites in the kingdom, including 61 existing facilities and 73 new venues.
Saudi Arabia was officially selected to host the 2034 Fifa World Cup during an online convention of Fifa member associations at the Fifa Congress on 11 December 2024.
 READ THE OCTOBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Industry and logistics drive development at Neom; Saudi Arabia’s investment priorities realign amid conflict; MEED’s 2026 power developer ranking.
Distributed to senior decision-makers in the region and around the world, the October 2026 edition of MEED Business Review includes:
> AGENDA: Oxagon takes centre stage at Neom> MARKET FOCUS: Saudi projects hold steady> INDUSTRY REPORT: MEED’s 2026 GCC power developer ranking> LEADERSHIP: The future city does not need to hang above the groundTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/20919233/main.jpg