Saudi leads MEED’s latest economic activity index
31 January 2023

Saudi Arabia has continued to sit atop the MEED Economic Activity Index with the close of 2022, as its repeat of another bumper year of project contract awards set it well clear of the next most competitive regional projects market.
The index has generally seen the division between energy exporters and importers sharpen, with the former enjoying current account and, for the most part, fiscal surpluses, and the latter invariably facing trade deficits and persisting fiscal deficits.
High inflation, compounded by rising interest rates and high fuel prices, continues to erode economic prospects in the region. It has also pressured the finances of countries with artificially high currency pegs. Egypt has been forced to drop its currency peg three times in the past year, leaving it increasingly at the mercy of inflation.
Saudi Arabia stands largely apart from these pressures as the region’s largest oil producer. Its inflation rate in 2023 is projected by the IMF to be a minimal 2.2 per cent. While its rate of real GDP growth is expected to come down from 7.6 per cent in 2022 to 3.7 per cent in 2023, this remains high amid the glum projections that up to a third of the global economy could enter recession this year.
Together with the UAE, Qatar, Kuwait and surprisingly Iraq, Saudi Arabia is expected to maintain a double-digit current account surplus in 2023, as well as a fiscal surplus, despite the kingdom’s rising project spending.
There is a further $95bn-worth of project value in the bidding stage [in Saudi Arabia], boding well for the potential of 2023 to be another bumper – if not record – year for the Saudi contracting sector
Project potential
Saudi Arabia’s project market maintained its momentum in 2022, seeing the award of 53bn-worth of project value, 1.3 per cent more than in 2021 and 46 per cent higher than the annual average over the preceding five years.
The award figure also exceeded the value of projects coming to completion over the course of the year by $21bn – a strong net positive result for the market.
There is a further $95bn-worth of project value in the bidding stage, boding well for the potential of 2023 to be another bumper – if not record – year for the Saudi contracting sector.
Mixed performances
The UAE, while retaining the second position in the index, has seen its score slip. Despite having strong real GDP growth and fiscal projections for 2023, the country remains well down from historic highs – the $18.7bn-worth of project awards in 2022 was just 53 per cent of the $35.1bn average in 2017-21. The market also shed $20bn in value as completions outstripped awards.
The $56.4bn of projects in bidding and due for award in 2023 makes the prospect of a turnround a possibility, but there is no guarantee given the global uncertainty.
Qatar has meanwhile risen strongly in the index since the third quarter of 2022, despite a real GDP growth projection by the IMF of just 2.4 per cent in 2023 – as the boost to non-oil GDP from the Fifa World Cup wears off.
Qatar’s project awards also fell in 2022 following a spike in 2021. The $14bn of awards in 2022 nevertheless remained almost level with the five-year average.
Kuwait also has a slightly lower real GDP projection in 2023, but strong overall fundamentals. Project activity also continues to tick over in the country, albeit at a slower than usual pace. The country has $27.6bn-worth of projects in the bid stage – a figure nearly 10 times the $2.8bn-worth of awards in 2022, which fell well below the $5.6bn average for the preceding five years.
The remaining GCC nations, Oman and Bahrain, and another Gulf energy exporter, Iraq, all also boast healthy current account surpluses. From there however, the countries diverge.
Oman is in a much better position heading into 2023, having stabilised its fiscal situation and eliminated its deficit. The country also has the lowest forecast consumer price inflation rate in the region heading into 2023, at just 1.9 per cent. Furthermore, the country has a burgeoning $19.7bn-worth of projects in the bid stage that could soon bolster its projects market.
Bahrain continues to struggle with both a persisting fiscal deficit and a debt burden – equivalent to about 120 per cent of its GDP. The country’s projects market slumped in 2022, with the less than $1bn of contract awards compared to $2.6bn in completions.
Iraq remarkably sits just below the GCC countries in the index thanks to its oil-fuelled GDP growth and twin double-digit current account and fiscal surpluses. Iraq’s project activity nevertheless fell away in 2022, which saw just $5bn-worth of awards – compared to $17bn the previous year and a $12bn five-year average. The $28bn-worth of projects in the bidding stage could nevertheless make for better things to come.
Egypt’s projects market has recently been in the ascendant, but its broader economic fortunes are now in sharp decline. The full impact of the country’s currency crisis has yet to be revealed, but Cairo already has twin current account and fiscal deficits.
Iraq remarkably sits just below the GCC countries in the index thanks to its oil-fuelled GDP growth and twin double-digit current account and fiscal surpluses
Facing challenges
Algeria, Morocco, Jordan and Tunisia are all struggling to break even in the current economic climate and have double-digit unemployment. This is ironic in the case of Algeria, which is an energy exporter with a current account surplus and yet double-
digit fiscal deficit.
Below this, Iran continues to be hampered by sanctions, creeping economic malaise and an estimated 40 per cent consumer price inflation rate amid a steadily collapsing import subsidies regime.
Libya, despite resurgent oil growth, has nearly 20 per cent unemployment and 50 per cent youth unemployment due to the civil war. Reconstruction efforts in the country also showed signs of stalling in 2022 as the project award value dropped off, with many projects stuck in the bid stage.
Yemen and Lebanon close out the index with dismal economic performances due to their respective ongoing conflict and economic crisis. Remarkably, with almost one-in-three out of work and unchecked inflation, Lebanon is managing to underperform even Yemen.
About the indexMEED’s Economic Activity Index, first published in June 2020, combines macroeconomic, fiscal, social and risk factors, alongside data from regional projects tracker MEED Projects on the project landscape, to provide an indication of the near-term economic potential of Middle East and North African markets. |


Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Dubai approves metro extension to Al-Maktoum airport
10 November 2026
-
 Egypt seeks to accelerate gas pipeline project with Libya
10 November 2026
-
 Omani company signs Kuwait drilling contract
10 November 2026
-
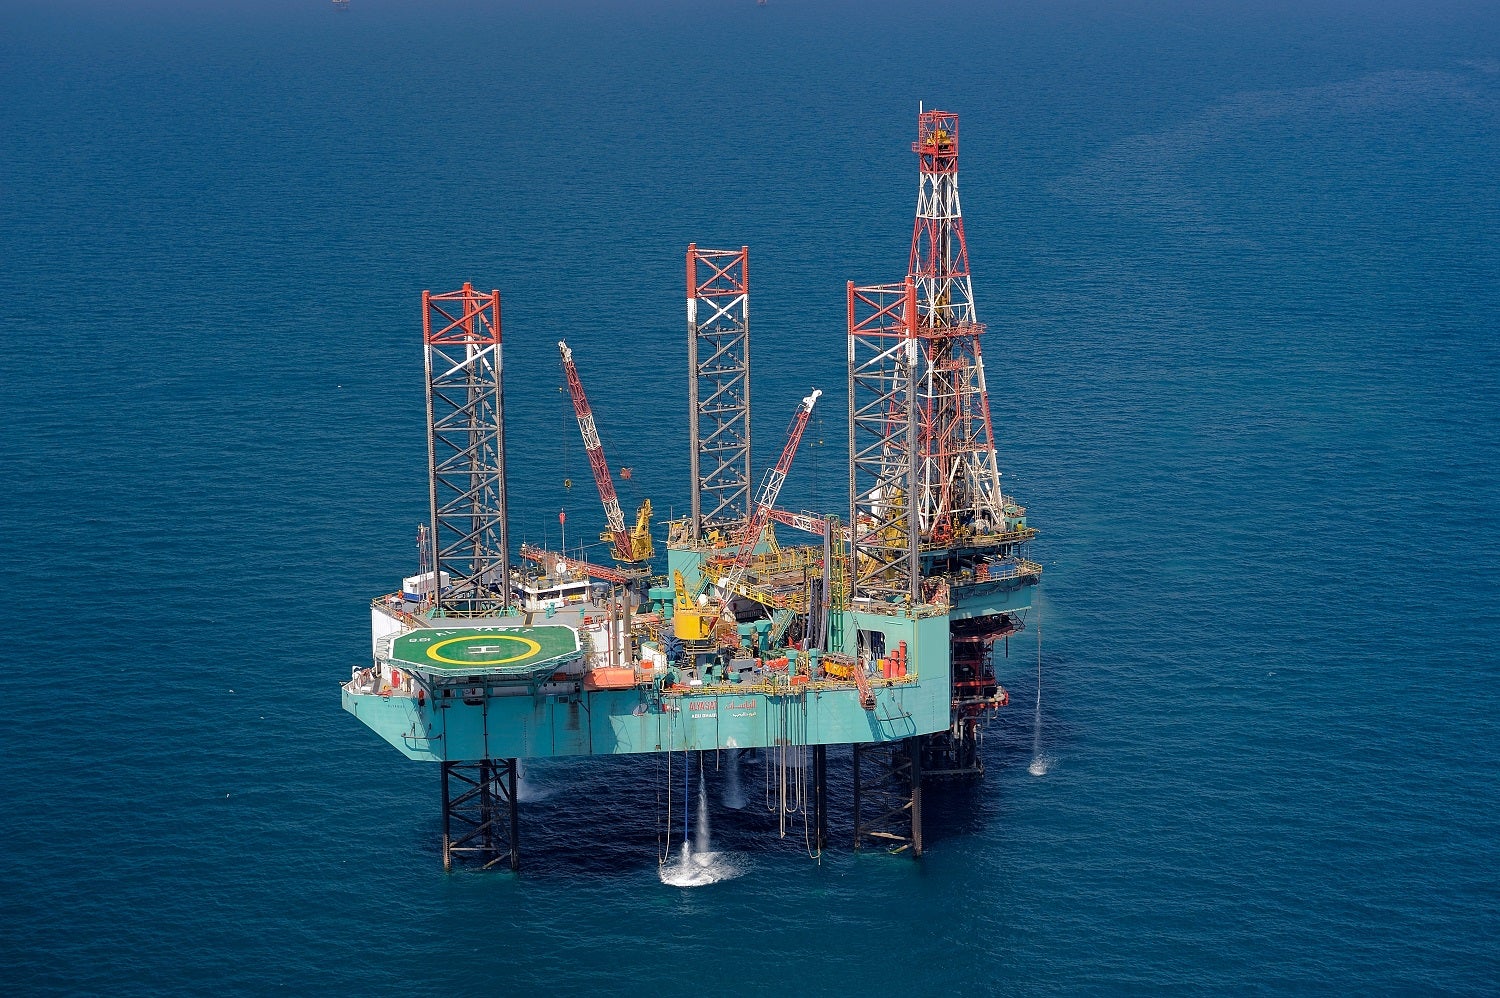 Adnoc Drilling wins $315m Kuwait offshore rig deals
10 November 2026
-
 Aramco-backed firm tenders logistics hub expansion
9 November 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Dubai approves metro extension to Al-Maktoum airport
10 November 2026
Dubai’s Executive Council has approved a project to extend the Dubai Metro’s Route 2020 to Al-Maktoum International Airport City, with passenger services scheduled to begin operations in 2031.
Sheikh Hamdan bin Mohammed bin Rashid Al-Maktoum, Crown Prince of Dubai, announced the decision following a council meeting held during the UAE Government Annual Meetings 2026.
The rail project forms part of a package of strategic schemes worth over AED11bn ($3bn) approved by the council.
The wider approvals include a comprehensive framework to upgrade community facilities and public services by 2040, with priority given to residential communities for UAE citizens.
حمدان بن محمد يترأس اجتماع المجلس التنفيذي لإمارة دبي ضمن الاجتماعات السنوية لحكومة دولة الإمارات، ويعتمد خلاله موازنة بقيمة أكثر من 11 مليار درهم لمشاريع استراتيجية جديدة في دبي، وخطة شاملة لتطوير الخدمات والمرافق المجتمعية، ومشروع امتداد مترو دبي إلى مطار آل مكتوم الدولي، كما أعتمد سموه خلال الاجتماع نتائج دراسة مستقبل السوق العقاري في دبي.
— Dubai Media Office (@DXBMediaOffice) November 10, 2026
The project approval follows the procurement of detailed design work for the rail link. MEED exclusively reported in September that Dubai’s Roads & Transport Authority (RTA) had awarded US-based engineering consultancy Aecom the design contract for the Route 2020 extension.
The planned extension will run for about 3 kilometres from the existing Expo 2020 terminus station to connect directly with the West Terminal of Al-Maktoum International airport. The scheme will add two new stations to the network.
The existing Route 2020 corridor is a 15km spur that branches off the Dubai Metro Red Line at Jebel Ali station. It comprises 11.8km of elevated viaduct and 3.2km of underground track, serving five elevated and two underground stations.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21301168/main.png -
Egypt seeks to accelerate gas pipeline project with Libya
10 November 2026
Egypt aims to accelerate a range of energy projects with Libya, including gas pipeline links, according to a statement from the Egyptian Foreign Minister Badr Abdelatty.
Other projects include a scheme to refine Libyan crude in Egypt and an electricity interconnection.
Abdelatty’s comments came in a ministry statement after a meeting with Libya’s acting oil and gas minister, Khalifa Abdulsadek, in the Libyan capital of Tripoli.
Egypt is currently trying to address an energy squeeze that has escalated due to elevated global liquefied natural gas (LNG) prices since the start of the US-Israeli war on Iran in February of this year.
In his statement, Abdelatty called for cooperation on petroleum products and the completion of projects to refine Libyan oil in Egypt and re-export it.
He also said that Abdulsadek would visit Cairo soon to continue technical talks with Egypt’s petroleum and electricity ministers.
The statement did not provide details on costs or the status of the projects.
Plans for new gas pipeline links with Libya are just one of several ambitious gas pipeline plans Egypt is pursuing.
In October, the Italian oil and gas company Eni signed the main engineering, procurement, construction and drilling contracts for a project to export gas from reserves in Cyprus using a major pipeline to Egypt.
The project includes contracts with several companies that will develop infrastructure in both Egypt and Cyprus.
The awards included a $170m contract won by Egypt’s Petrojet for a new onshore gas pipeline in Egypt that will help transport gas to Egypt’s Damietta LNG facility.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273777/main.jpg -
Omani company signs Kuwait drilling contract
10 November 2026
Oman’s MBPS has signed a drilling rig contract worth $127.3m with state-owned upstream operator Kuwait Oil Company (KOC).
Under the terms of the deal, MBPS will supply and operate three newly built 1,000-horsepower land rigs for drilling and workover operations, according to a company statement.
The UAE-based oil field services company Adnoc Drilling is a majority shareholder in MBPS.
The chief executive of MBPS, Salim Al-Harthy, said: “This is another important milestone for MBPS and a strong reflection of KOC’s confidence in our capabilities.
“It further strengthens our presence in Kuwait and our commitment to delivering safe, reliable and efficient drilling and workover services across the region.”
He : “My sincere appreciation to KOC for their continued trust, and to our MBPS team for their hard work and dedication in making this possible.”
In October last year, KOC said it planned to spend KD1.2bn ($3.92bn) on its exploration drilling programme through 2030.
The spending was part of a KD9.8bn budget, the company’s biggest ever, allocated for drilling and maintenance of up to 6,193 wells by the end of this decade.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273731/main.png -
Adnoc Drilling wins $315m Kuwait offshore rig deals
10 November 2026
Register for MEED’s 14-day trial access
Abu Dhabi National Oil Company (Adnoc Group) subsidiary, Adnoc Drilling, has been selected for two offshore drilling rig contracts in Kuwait with a combined maximum value of KD96.55m ($315m), according to documents published by Kuwait’s Official Gazette.
The Higher Purchasing Committee of state-owned Kuwait Petroleum Corporation (KPC) has given approval for its subsidiary Kuwait Oil Company (KOC) to award the contracts to the Abu Dhabi-listed drilling contractor after Adnoc Drilling submitted the lowest compliant bids.
While the maximum combined contract value has been confirmed as KD96.55m ($315m), the individual contract values, rig identities, durations and expected commencement dates have not been disclosed.
The approval comes as Kuwait moves to expand offshore exploration and development following a series of discoveries in its territorial waters.
It is currently unclear how Kuwait will provide security for its planned offshore oil and gas projects in the Gulf, adding uncertainty to the outlook for these plans.
On 5 October, KPC chief executive Shaikh Nawaf Al-Sabah reiterated the company’s commitment to developing three major offshore oil discoveries in the region.
KPC initially launched the Al-Seef project to develop the three fields in February, just weeks before the US and Israel attacked Iran, triggering a regional war that has sparked a crisis in Kuwait’s oil and gas sector.
The regional conflict has seriously disrupted shipping through the Strait of Hormuz, a key export route for Kuwaiti oil.
The war has also led to dozens of attacks on Kuwaiti oil and gas infrastructure, with at least one causing damage to a Kuwaiti offshore platform.
This attack took place on 12 July, when a drone struck a KOC offshore drilling platform in Kuwaiti territorial waters, causing damage to the platform and injuring one worker.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21273678/main2430.jpg -
Aramco-backed firm tenders logistics hub expansion
9 November 2026
Asmo, the logistics joint venture of Saudi Aramco and DHL Supply Chain, has set a 15 November deadline for a contract to expand the logistics complex at King Salman Energy Park (Spark) in Saudi Arabia’s Eastern Province.
The logistics hub will add over 124,000 square metres (sq m) at Spark.
Al-Khobar-based engineering firm House of Consulting Office is the project consultant.
The tender for the expansion works comes shortly after Asmo awarded an estimated SR820m ($218m) contract to build the logistics complex’s first phase in May this year.
The overall project will feature a 43,000 sq m, temperature-controlled Grade A warehouse; more than 3,000 sq m of offices and staff amenities; 5,300 sq m dedicated to chemicals storage; and an open yard covering about 1.2 million sq m.
Asmo signed an agreement with Bahrain‑headquartered Arcapita Group Holdings in February to deliver the project at Spark.
Planned for large-scale industrial use, the site is expected to incorporate advanced warehouse and building management systems, end-to-end digital connectivity, automation and robotics.
It will also be developed in line with internationally recognised sustainability standards, featuring solar photovoltaic readiness, electric-vehicle charging infrastructure and a target of Leed Gold certification.
The development aims to support the next stage of Saudi Arabia’s logistics and supply chain expansion.
Under the deal structure, Arcapita will provide funding and retain ownership of the asset, while Asmo will develop the facility and then lease and operate it under a 22-year occupational lease.
According to a statement, “the scheme will be executed via a forward-funding model, underscoring a long-term commitment to national infrastructure”.
Asmo added that this will be its first purpose-built logistics centre and one of four strategic locations planned to anchor its nationwide logistics network, aligned with the National Transport and Logistics Strategy under Saudi Vision 2030.
https://image.digitalinsightresearch.in/uploads/NewsArticle/21267403/main.gif