Acwa Power widens equity gap in power developer league
2 October 2023

The equity gap between Saudi utility developer Acwa Power and the other private utility developers in the GCC region has continued to widen, according to MEED’s annual GCC power developer ranking.
Acwa Power’s net capacity reached 13,340MW. This has doubled its lead to 67 per cent over France’s Engie, whose net capacity of 7,987MW has remained unchanged.
Over the past 12 months, power-purchase agreements were signed for six solar independent power producer (IPP) projects, as well as for a multi-utility public-private partnership contract and a cogeneration plant.
The seven contracts have a total combined power generation capacity of more than 8,000MW.
Acwa Power gained more than 2,900MW in net capacity over this period. This was due in large part to a 35 per cent equity share in the 2,060MW Shuaibah 2 solar power project and a 50 per cent shareholding in each of the Saad 2, Ar-Rass 2 and Kahfah solar photovoltaic (PV) projects.
These contracts were procured by the kingdom's Public Investment Fund (PIF) through the Saudi renewable energy price discovery scheme.
Notably, the 600MW Shuaibah 1 solar IPP scheme, which was publicly tendered and awarded to an Acwa Power-led consortium under the second round of the National Renewable Energy Programme (NREP) in 2021, has been combined with the PIF’s Shuaibah 2.
Under the final scheme, which reached financial close this year, Acwa Power’s shares in Shuaibah 1 decreased from 50 per cent to 35 per cent. The shares of its partners Gulf Investment Corporation and Al-Babtain, which originally maintained 30 per cent and 20 per cent, respectively, have been bought by PIF subsidiary the Water & Electricity Holding Company (Badeel) and Saudi Aramco Power Company (Sapco).
As with Engie, the net and gross capacities of Japanese firms Marubeni, Mitsui, Sumitomo and Jera also remained unchanged, with no new contract wins in the period.
Ranked 10th in the previous year’s listing, France’s EDF rose three spots this year to claim seventh place, which was previously held by Korea Electric Power Corporation (Kepco).
EDF’s rise came as a result of winning contracts for two major schemes. It was selected together with South Korea’s Korea Western Power Company (Kowepo) to develop Oman’s 500MW Manah 1 solar IPP project, and was also awarded a multi-utility contract with the UAE’s Abu Dhabi Future Energy Company (Masdar) for the Amaala development in Saudi Arabia, which includes a 250MW solar power farm.
EDF overtook Kepco despite the South Korean firm’s successful bid for the Jafurah cogeneration plant, where it maintains a 60 per cent equity. The scheme’s power generation plant has a capacity of 320MW.
Singapore’s Sembcorp and China’s Jinko Power, which comprise the team that won the Manah 2 solar IPP contract in Oman, occupy the ninth and 10th spots, respectively.
Saudi utility developer Aljomaih Energy & Water Company relinquished its 10th spot last year.
 Power tariffs have scope to improve
A different view
Saudi Arabia’s renewable energy price discovery tool is becoming a potential game-changer for the competitive landscape of GCC power developers.
It allows Acwa Power to submit a proposal to match the most recent prices obtained through each round of the NREP public tendering process, which is overseen by the state-backed principal buyer, Saudi Power Procurement Company (SPPC).
Under the price discovery scheme, the PIF will only invite other developers to bid for a contract if Acwa Power fails to match prices achieved through the public tenders.
Acwa Power has so far won all five of these contracts, which have a total combined capacity of 8,110MW.
Since the PIF is tasked with procuring 70 per cent of Saudi Arabia’s 58,700MW renewable energy capacity target by 2030, the Saudi sovereign wealth vehicle is expected to procure a further 32,000MW of renewable capacity over the coming years using the price discovery scheme.
Given the scale of the PIF’s programme, and the extent to which it has expanded Acwa Power’s renewables portfolio this year, a separate league table that includes only IPPs and independent water and power producer (IWPP) projects that have been publicly tendered, or simultaneously tendered to a pool of qualified private utility developers, offers interesting insights.
Excluding the PIF contracts reveals that the ranking of the private utility developers based on their net capacity – or the capacity commensurate to a developer’s equity shareholding in each power generation asset – is unchanged. Acwa Power remains at the top, with a total equity capacity of more than 9,800MW, compared to Engie’s nearly 8,000MW.
However, their gross capacity rankings reverse when the PIF contracts are excluded. Engie leads by 4 per cent in terms of gross capacity, or the total capacity of power plants that they are developing alone or with consortium partners.
Gas revival
No new gas-fired IPP or IWPP projects have been let in the GCC since 2021, when most principal buyers and utilities began to focus on increasing their renewable energy capacity in line with their countries’ decarbonisation agendas.
With the exception of the UAE's Fujairah F3 and Saudi Aramco’s Tanajib and Jafurah cogeneration plants, solar and wind power plants have accounted for the majority of private power generation capacity that has been procured since 2020.
This is set to change in the next 12-24 months as renewed demand for combined-cycle gas turbine (CCGT) plants is driven by the need to decommission old fleets that burn liquid fuel, or to replace expiring baseload capacity.
As of September this year, gas-fired power plants account for approximately 60 per cent of the GCC region's planned power generation plants that are likely to be awarded in the next 24 months, according to MEED research.
The bid evaluation process is under way for four gas-fired IPPs in Saudi Arabia with a total combined capacity of 7,200MW. These are the first gas-fired IPP schemes to be procured by the kingdom since 2016.
A further three IWPP schemes – Kuwait's Al-Zour North 2 & 3 and Al-Khiran 1 and Qatar’s Facility E – are in the procurement stage. These schemes have a total combined power generation capacity of 6,800MW.
Next year, SPPC is expected to begin the procurement process for two gas-fired IPPs: the PP15 in Riyadh and another in Al-Khafji. Each is expected to have power generation capacity of 3,600MW.
Abu Dhabi’s Emirates Water & Electricity Company (Ewec) is also expected to initiate the procurement process for two CCGT plants with a total combined capacity of 2,500MW before the end of 2023.
Renewable arena
The revival of gas-fired schemes will not necessarily come at the expense of renewables, however.
The region’s largest market has ramped up its issuance of solar and wind tenders over the past 12 months and is expected to sustain or even accelerate the pace of its renewables procurement.
Saudi Arabia needs to procure at least 43,000MW of renewable energy capacity through public tenders and direct negotiations over the next six years to meet its 2030 target. This equates to about 7,200MW a year – twice its current average.
Overall, the future strength of the market for private utility developers is ensured by a growing clientele in Saudi Arabia that includes Neom and its subsidiary Enowa, in addition to the utilities in the other five GCC states, and the large conglomerates and organisations that aim to build captive power plants.
A case in point is the 35,000MW of solar and wind energy projects are in the pre-development stage for Neom, which aims to be powered 100 per cent by renewable energy by 2030.
Abu Dhabi also plans to procure at least 1,500MW of solar PV capacity annually over the next 10 years, in line with its goals for decarbonising its electricity system.
Developers’ dilemma
A Dubai-based executive with one of the international developers active in the region says: “It has been a very busy year for us. If all of these plans come through in the next 12-24 months, it will be even busier.”
The executive is unsure whether all the planned gas-fired projects will materialise, however. “We have been here before, and some of these projects have experienced major delays in the past for reasons that are not even related to decarbonisation or net-zero targets.”
Given the GCC states' carbon emissions reduction targets and the recent easing of supply chain constraints, solar and wind IPPs appear to offer greater certainty for utility developers, many of which are also beholden to internal decarbonisation targets that include a reduction of their existing thermal fleets.
The contracts for five solar and three wind IPPs in the region are expected to be awarded soon.
Masdar has outpriced Acwa Power for the 1,800MW sixth phase of Dubai’s Mohammed bin Rashid al-Maktoum Solar Park project. A team of EDF and Kowepo has also submitted the lowest bid for the 1,500MW Al-Ajban solar PV IPP in Abu Dhabi.
In addition, SPPC has shortlisted bidders for two solar PV IPPs with a total combined capacity of 1,500MW under the NREP fourth round. It also expects to receive bids soon for three wind IPPs with a total combined capacity of 1,800MW.
Tenders for the NREP’s fifth round and Abu Dhabi’s fourth utility-scale solar PV farm are also expected imminently.

Register for MEED's guest program now to access this article.
Exclusive from Meed
-
 Engineering progresses on Ras Laffan LNG terminal berths
16 September 2026
-
 Design completed for Libyan oil field development
16 September 2026
-
 QatarEnergy selects contractors for offshore oil field expansion
16 September 2026
-
 Contractors prequalify for Bahrain sports stadium
15 September 2026
-
 Riyadh Expo signs private real estate development deal
15 September 2026
All of this is only 1% of what MEED.com has to offer
Subscribe now and unlock all the 153,671 articles on MEED.com
- All the latest news, data, and market intelligence across MENA at your fingerprints
- First-hand updates and inside information on projects, clients and competitors that matter to you
- 20 years' archive of information, data, and news for you to access at your convenience
- Strategize to succeed and minimise risks with timely analysis of current and future market trends
Related Articles
-
Engineering progresses on Ras Laffan LNG terminal berths
16 September 2026
Register for MEED’s 14-day trial access
Front-end engineering and design (feed) works are progressing on a QatarEnergy LNG project to build 13 liquefied natural gas (LNG) loading berths at the south export terminal in Qatar’s Ras Laffan Industrial City.
Ras Laffan Industrial City, which lies about 90 kilometres north of Doha, is the world's largest integrated LNG production and export complex, comprising 15 processing trains with a total capacity of 77.5 million tonnes a year (t/y). QatarEnergy began LNG operations at the facility, which houses all its processing trains and export infrastructure, in 1984.
According to sources, QatarEnergy LNG, a subsidiary of state enterprise QatarEnergy, awarded the feed contract for the project to build 13 LNG berths at the south export terminal at Ras Laffan to Australia-headquartered Worley.
The contract was awarded to Worley in the second quarter of this year. Its duration is estimated to be 200,000-250,000 man hours, sources told MEED.
Ras Laffan’s LNG processing and export capabilities will increase by up to about 63% when the three phases of QatarEnergy’s estimated $40bn North Field LNG expansion project come into operation by the end of this decade. Engineering, procurement and construction (EPC) works on all three projects are progressing.
QatarEnergy is understood to have committed nearly $30bn to the first two phases – North Field East (NFE) and North Field South (NFS) – which will lift Qatar’s LNG production capacity from 77.5 million t/y to 126 million t/y by 2028.
QatarEnergy awarded the main EPC contracts for NFE in 2021. The project was intended to raise LNG output to 110 million t/y by 2025. The $13bn EPC package – covering the engineering, procurement, construction and installation of four LNG trains, each with a capacity of 8 million t/y – was awarded in February 2021 to a consortium of Japan’s Chiyoda and France’s Technip Energies.
In May 2023, QatarEnergy awarded the $10bn main EPC contract for NFS to a consortium of Technip Energies and Consolidated Contractors Company (CCC). The contract includes two LNG trains, each with a capacity of 7.8 million t/y.
Once fully operational, the first two phases are expected to add 48 million t/y of LNG supply to the global market.
QatarEnergy took the final investment decision on the third phase, North Field West (NFW), this year, awarding an EPC contract estimated at $8bn to a joint venture comprising Technip Energies, CCC and Gulf Asia Contracting in February.
Chiyoda carried out the feed work for the NFW LNG project.
The NFW scope covers the EPC of two LNG trains with a combined capacity of 16 million t/y, as well as associated facilities for gas treatment, natural gas liquids recovery and helium extraction.
In addition to LNG, NFW is expected to produce about 175,000 barrels of oil equivalent a day of condensate, ethane and liquefied petroleum gas.
With all three phases under EPC execution – and NFE scheduled for commissioning later this year – QatarEnergy is positioning itself to remain one of the world’s largest LNG suppliers in the long term.
 READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDF
Nuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19715235/main5946.jpg -
Design completed for Libyan oil field development
16 September 2026
Register for MEED’s 14-day trial access
Design work has been completed for a project to develop Libya’s I/R oil field, according to industry sources.
The front-end engineering and design work was completed by a team in the London offices of Italy’s EniProgetti and paves the way for the main engineering, procurement and construction contract to be tendered.
One source said: “At the moment, there is no fixed date for when the invitation to bid for the main contract will be issued, but the project has a lot of momentum and is progressing towards tendering.”
The I/R oil field is located in Murzuq Basin in southwestern Libya.
In June this year, Libya's National Oil Corporation (NOC) signed a unified operating agreement for the field.
The I/R field is operated by Akakus Oil Operations, which is a joint venture of NOC in partnership with Spain’s Repsol, France’s TotalEnergies Repsol, Austria’s OMV and Norway’s Equinor.
The agreement in June was signed by NOC as well as its concession partners.
NOC said the agreement would unify operational and administrative procedures related to field management, optimise resource utilisation and support production sustainability.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19711588/main.jpg -
QatarEnergy selects contractors for offshore oil field expansion
16 September 2026
Register for MEED’s 14-day trial access
QatarEnergy has selected contractors for the two main engineering, procurement and construction (EPC) packages of its estimated $4bn-$5bn Maydan Mahzam offshore oil field expansion project in Qatar.
The Qatari energy giant has selected a consortium of state-owned PetroVietnam Technical Services Corporation (PTSC) and Singapore-based Seatrium for package one of the Maydan Mahzam field expansion project, according to sources.
State-owned China Offshore Oil Engineering Company (COOEC) has secured package two of the project, sources told MEED.
Additionally, PTSC has confirmed its contract award for the first engineering, procurement, construction and installation (EPCI) package in a disclosure to the Hanoi Stock Exchange, saying its wholly owned subsidiary PTSC Mechanical & Construction had received a letter of award from QatarEnergy. The company added that “the parties will continue discussions to finalise and execute the definitive contract, which is expected to be signed in October 2026”.
In its filing, PTSC added that its scope of work covers “the provision of engineering, procurement, construction, transportation, offshore installation, hook-up, commissioning and brownfield modification services for the [Maydan Mahzam] project”.
MEED reported in late August that the consortium of PTSC and Seatrium had emerged as the frontrunner for package one of the expansion project.
At the time, US-based McDermott was ahead in the race to win package two. However, COOEC is understood to have presented "better terms to the client in the final rounds of negotiations”, sources said.
QatarEnergy issued the main tender for the Maydan Mahzam oil field expansion project in February 2025, with EPC works divided into four packages, MEED previously reported.
Contractors submitted technical bids for the project’s two main EPC packages in September 2025, sources said.
After QatarEnergy granted several extensions to the deadline for the submission of commercial bids for the two packages – initially set for 1 March – contractors submitted their prices by 21 June, MEED reported.
The following contractors, among others, are understood to have submitted bids for the two main packages of the project:
Package one:
- China Offshore Oil Engineering Company (China)
- Hanwha Ocean (South Korea)
- Hyundai Heavy Industries (South Korea)
- Larsen & Toubro Energy Hydrocarbon (India)
- PetroVietnam Technical Services Corporation (Vietnam) / Seatrium (Singapore)
- Saipem (Italy)
Package two:
- Allseas (Netherlands)
- China Offshore Oil Engineering Company (China)
- Larsen & Toubro Energy Hydrocarbon (India)
- McDermott (US)
- Saipem (Italy)
The Maydan Mahzam oil field lies about 100 kilometres (km) northeast of the Qatari coastline and 28km southeast of Halul Island, located in water depths of about 40 metres. The field, together with the nearby Bul Hanine field, was discovered in the 1960s and has been in production since 1965.
QatarEnergy is undertaking the project to upgrade infrastructure at Maydan Mahzam to extend the life of this maturing asset and maintain productivity over the long term.
The scope of work for package one includes the EPC of seven new topsides, requiring the fabrication of structures weighing more than 78,000 metric tonnes in total. The main process topside will weigh 19,400 metric tonnes, while the other topsides will consist of 10-legged jackets.
The scope also includes modifications to five existing topsides, four new bridges, eight-tonne support platforms with jackets, brownfield work on Halul Island and the installation of pipelines and cables.
The scope of work for package two covers the EPCI of topsides, umbilicals and cables.
ALSO READ: Contractors submit bids for Dukhan field facilities upgrade
In addition to advancing its gas production and liquefied natural gas ambitions, QatarEnergy committed significant capital expenditure last year to increasing oil output capacity from its offshore fields.
In August 2025, QatarEnergy selected contractors for the EPC works on a project to maintain and increase production potential at the Bul Hanine offshore oil field. The EPC scope was divided into three main packages, with COOEC being awarded the first two packages and Qatari contractor Doha Petroleum Construction Company (Dopet) being selected for the third. In addition, COOEC appointed US-based KBR to provide detailed engineering services for the first and second packages.
Separately, last September, QatarEnergy awarded the main EPC contract for a project to add a fifth natural gas liquids (NGL) train at its complex in Mesaieed Industrial City. Indian contractor Larsen & Toubro Energy Hydrocarbon won the contract.
The project, estimated to be worth $2.5bn, aims to build a fifth NGL train with the capacity to process up to 350 million cubic feet a day of rich associated gas from QatarEnergy’s offshore and onshore oil fields.
ALSO READ: Contractors prepare bids for North Field West offshore platforms
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19688942/main3340.jpg -
Contractors prequalify for Bahrain sports stadium
15 September 2026
Register for MEED’s 14-day trial access
Twenty-one local and Saudi Arabia-based contractors have been prequalified for a contract to build the first phase of the Bahrain International Sports City project in the Sakhir area.
The prequalification stage closed on 13 September.
The notice was first issued on 24 May, with an initial submission deadline of 26 July.
The prequalified firms are:
- Alfanar Projects (Saudi Arabia)
- Al-Ayuni Investment & Contracting (Saudi Arabia)
- Nesma Infrastructure & Technology (Saudi Arabia)
- Shar Construction (Saudi Arabia)
- Saudi Binladin Group (Saudi Arabia)
- Kooheji Contractors (local)
- B1 Trading & Services (local)
- Nass Contracting (local)
- RTCC / IC Ictas (Saudi Arabia / Turkiye)
- Moffareh Alharbi & Partners (Saudi Arabia)
- Al-Sharif Group Holding (Saudi Arabia)
- Cebarco (local)
- Midmac Contracting (Qatar)
- BEC Arabia (Saudi Arabia)
- Shibh Al-Jazira Contracting Company (Saudi Arabia)
- Poullaides Construction Poullaides Construction
- Isam Khairi Kabbani Partners (Saudi Arabia)
- El-Seif Engineering Contracting Company (Saudi Arabia)
- AlBawani (Saudi Arabia)
- Nesma & Partners (Saudi Arabia)
- Modern Building Leaders (Saudi Arabia)
The latest development follows US-based engineering firm Populous winning a BD5m ($13.5m) contract for the development, as MEED reported.
Populous’ scope covers pre-contract consultancy services, including finalising the masterplan and internal infrastructure, completing phase 1A design works and preparing tender documents.
The contract was first tendered in 2021, when Populous emerged as the sole bidder.
At the time, it was reported that the Sports City project would include Bahrain’s largest sports stadium and a multipurpose indoor sports arena.
The project is expected to provide renewed impetus to Bahrain’s construction and transport sector, which has struggled in recent years, with the total value of awarded contracts falling for a third consecutive year.
According to regional project tracker MEED Projects, about $400m-worth of contracts had been awarded in Bahrain by the end of October last year – less than half the $1.2bn recorded during the same period the previous year.
The sector has yet to return to pre-pandemic levels. Before 2020, Bahrain consistently awarded more than $2bn in contracts annually, peaking at nearly $4bn in 2016.
Bahrain’s construction industry is forecast to record average annual growth of 4.9% in 2026-29, supported by investments in transport infrastructure and renewable energy projects aligned with Bahrain’s Economic Vision 2030.
Vision 2030 includes the BD11.3bn ($30bn) Strategic Projects Plan, unveiled in October 2021, encompassing 22 national infrastructure projects. It also includes plans to create five new cities by 2030: Fasht Al-Jarm, Suhaila Island, Fasht Al-Azem, Bahrain Bay and Hawar Islands.
Growth over the forecast period is also expected to be driven by investments under the National Renewable Energy Action Plan, which targets a 30% reduction in carbon emissions by 2035, compared to 2015 levels, and aims to achieve net-zero emissions by 2060.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19670426/main.jpg -
Riyadh Expo signs private real estate development deal
15 September 2026
Register for MEED’s 14-day trial access
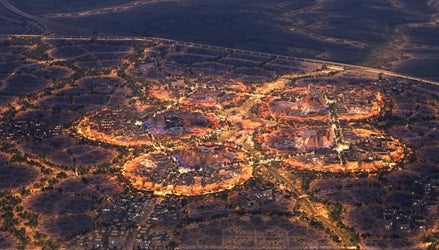
Saudi Arabia's Expo 2030 Riyadh Company (ERC) has signed an agreement with Riyadh-based developer Mohammed Al-Habib Real Estate Company to develop and deliver Expo Village, the event's residential community.
The project will comprise about 2,300 apartments, housing around 5,500 residents, alongside retail and dining outlets, amenities, services and operational facilities.
The community will be connected to the Expo 2030 Riyadh site via the Expo metro station, as well as to King Khalid International airport and the city’s wider transport network.
The deal marks ERC’s first private-sector partnership deal for the site.
The latest agreement comes as ERC is gearing up to deliver several components of the site. Tendering is ongoing for the Saudi Arabia pavilion, and another tender is out for the delivery of the Souq areas within the expo site.
Site progress
Construction activity at the expo site is accelerating, with Riyadh moving to award its first major vertical contracts and advancing infrastructure works across the programme.
Earlier this month, Saudi Arabia’s Royal Commission for Riyadh City awarded a design-and-build contract for the construction of a new metro station catering to the Expo 2030 site.
In April, ERC awarded two contracts for the next phase of infrastructure works at the site to local firm Alyamama Company.
The scope covered the construction of road networks and infrastructure for water, sewage, electricity, telecommunications and electric vehicle (EV) charging.
These awards followed ERC’s January award of an estimated SR1bn ($267m) contract for initial infrastructure works at the site to local firm Nesma & Partners.
That scope covered about 50 kilometres of integrated infrastructure networks, including internal roads and essential utilities such as water, sewage, electrical and communications systems; and EV charging stations.
The masterplan covers 6 square kilometres, making it one of the largest sites ever designated for a World Expo event. Situated to the north of the Saudi capital, the site will be located near the future King Salman International airport and will provide direct access to landmarks within Riyadh.
The Public Investment Fund, Saudi Arabia’s sovereign wealth vehicle, launched ERC – a wholly owned subsidiary – in June 2025, to build and operate facilities for Expo 2030.
READ THE SEPTEMBER 2026 MEED BUSINESS REVIEW – click here to view PDFNuclear power ambitions gather pace; Kuwait keeps dealmaking alive despite war; Region invests in raising gas processing capacity.
Distributed to senior decision-makers in the region and around the world, the September 2026 edition of MEED Business Review includes:
> AGENDA: Gulf nuclear revival takes shape> MARKET FOCUS: Kuwait keeps dealmaking alive under fire> INDUSTRY REPORT: Gas processing takes centre stage in Mena regionTo see previous issues of MEED Business Review, please click herehttps://image.digitalinsightresearch.in/uploads/NewsArticle/19665616/main.jpg